

Quick Answer: Financial stress is no longer just a low-income problem. The New York Federal Reserve’s Q4 2025 data shows U.S. household debt hit $18.8 trillion, and credit counseling agencies report their average client now earns $70,000 a year and carries $35,000 in unsecured debt — double the pre-pandemic ratio. Higher-income Americans are increasingly falling behind on mortgage, credit card, and auto loan payments.
For years, the narrative has been simple: debt problems happen to people who don’t make enough money. But 2026 is shattering that myth. According to The Wall Street Journal, financial stress is spreading up the income ladder, hitting people who thought they were doing everything right.
The math tells the story: prices are 25% higher than five years ago. Wages haven’t kept pace. The labor market is stalling. And even six-figure earners are quietly running up credit card balances to cover the gap.
The Numbers That Should Wake You Up
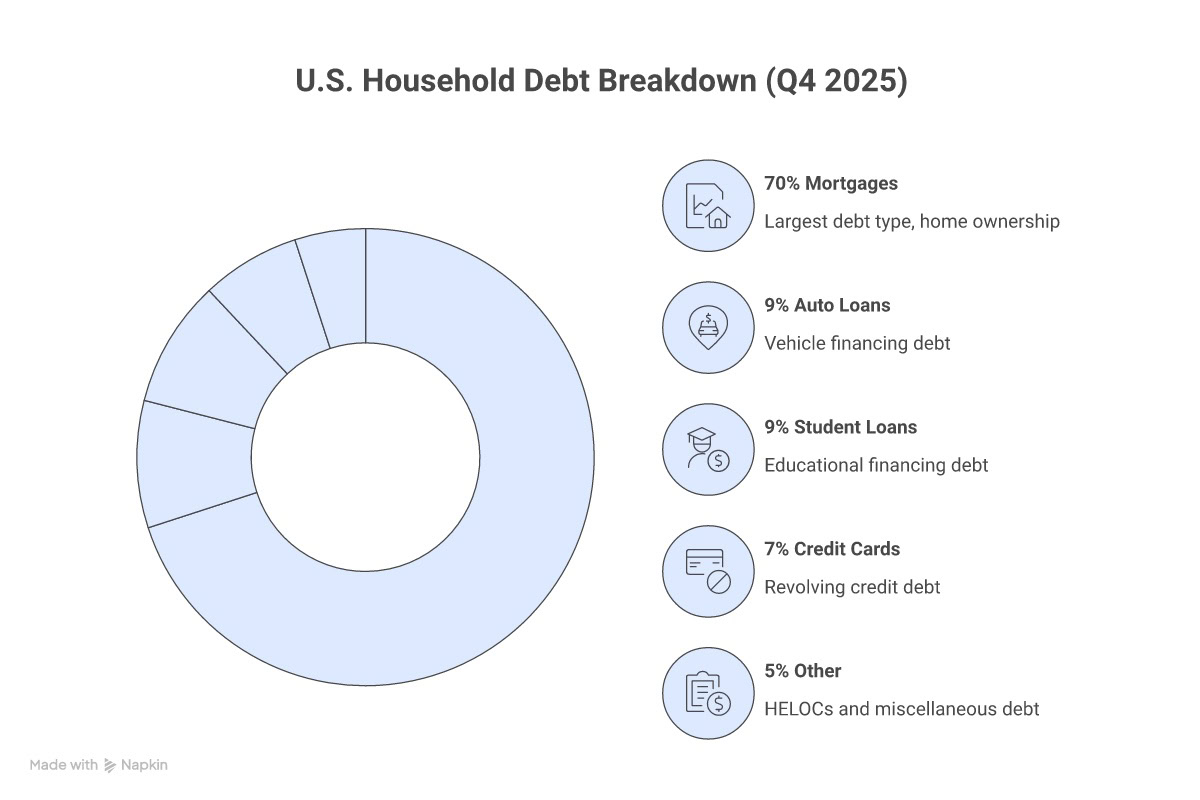
That last number is the headline nobody is talking about. Credit counseling agencies — the organizations people turn to when they can’t keep up — are seeing clients who earn $70,000 a year and carry $35,000 in unsecured debt. That’s double the pre-pandemic ratio. These aren’t people living on minimum wage. These are middle-class professionals whose math stopped working.
Where the Stress Is Showing Up
The New York Fed’s Q4 2025 Household Debt and Credit Report breaks it down by category:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Debt Categories (Q4 2025)
- Mortgages: $13.17 trillion (+$565B year-over-year)
- Credit Cards: $1.28 trillion (+$66B year-over-year)
- Auto Loans: $1.67 trillion
- Student Loans: $1.66 trillion
Delinquency Rates (90+ Days)
- Student Loans: 9.6% — worst level in years
- Credit Cards: 7.13% transition rate
- Auto Loans: 2.95% transition rate
- Mortgages: 1.38% (up from 1.09% a year ago)
According to Wolf Street’s analysis of the data, $586 billion in household debt is now 90 or more days past due. Student loan delinquencies are at historic levels with 16.3% of balances 30+ days late — the worst reading ever recorded.
Key Insight: Mortgage delinquency transitions jumped from 1.09% to 1.38% year-over-year. That doesn’t sound like much until you realize it’s happening against $13.17 trillion in mortgage balances. That small percentage increase represents tens of billions in at-risk payments.
Why Higher-Income Earners Are Struggling Now
This isn’t about people suddenly becoming irresponsible. It’s about math that no longer works:
- Prices are 25% higher than 5 years ago — groceries, insurance, childcare, utilities
- Wages haven’t kept pace with inflation — real purchasing power has declined
- The labor market is stalling — fewer job openings, slower wage growth
- Interest rates remain elevated — mortgage, auto, and credit card rates are all higher
- The “wealth effect” masks the problem — home equity and stock portfolios look fine on paper while cash flow deteriorates
Debt is what’s left over when the math is broken. And right now, the math is broken for a lot more people than anyone wants to admit.— Steve Rhode
Here’s what I see when I look at these numbers: higher-income earners often have higher fixed obligations. Bigger mortgage. Two car payments. Student loans from grad school. Private school tuition. When inflation pushes everyday costs up 25% and income rises maybe 10-15%, the gap gets filled with credit cards. Month after month, that gap compounds.
The K-Shaped Economy Is Real
The data shows a diverging economy. The debt-to-disposable income ratio is currently 81.2% — actually well below the pre-financial crisis peak of over 115%. On the surface, that looks manageable.
But averages lie. If you have a paid-off house and a stock portfolio, your ratio is great. If you’re carrying a $400,000 mortgage, $35,000 in credit cards, and two car notes, your personal ratio might be 150% — and that’s the person starting to miss payments.
The Hidden Story: While delinquencies are rising, bankruptcies are actually below pre-pandemic levels — 123,820 filings in Q4 2025 compared to 186,000-234,000 pre-COVID. That means people are falling behind but not yet seeking the relief that could actually help them. They’re grinding instead of solving.
What This Means for You
If you’re a higher-income earner who’s started relying on credit cards to bridge the gap between paychecks and expenses, you’re not alone. And you’re not failing. The math changed — the economy changed — and your budget didn’t adapt because it couldn’t adapt when costs jumped 25% in five years.
But here’s where I need you to hear something most advisors won’t say:
The Dogma: “You make good money. You should be able to figure this out. Just cut back and pay it off.”
The Reality: If your income is $70,000 and your unsecured debt is $35,000, “cutting back” isn’t going to fix the math. You need to look at ALL your options — including the ones that feel uncomfortable — and make the decision that protects your future, not just your pride.
- Run your own numbers first. Take the free Find Your Path quiz to see which options actually apply to your situation.
- Stop raiding retirement. Whatever you do, do NOT cash out your 401(k) to pay unsecured debt. That’s trading a protected asset for a sinking ship. Federal Reserve research shows bankruptcy filers are better off financially within 2-3 years.
- Understand the opportunity cost. Every dollar you spend grinding through a 5-year repayment plan is a dollar not growing in your retirement account. At 8% returns, the long-term cost can be staggering.
- Consider ALL your options. Debt management plans, settlement, bankruptcy — they all exist for a reason. The right one depends on YOUR numbers, not someone else’s opinion.
Key Takeaways
- U.S. household debt hit $18.8 trillion in Q4 2025, with $740 billion added in one year
- Credit counseling clients now average $70K income with $35K in unsecured debt — double pre-pandemic
- 4.8% of all household debt is delinquent; credit card and student loan delinquencies are at multi-year highs
- Bankruptcies are below pre-pandemic levels — people are suffering instead of solving
- If the math doesn’t work, no amount of budgeting fixes it — look at all your options
FAQ
Why are higher-income Americans falling behind on payments?
Prices have risen approximately 25% over five years while wages haven’t kept pace. Higher-income earners often have larger fixed obligations — bigger mortgages, multiple car payments, student loans — leaving less margin for error when everyday costs increase. The gap is being filled with credit card debt.
How much household debt do Americans have in 2026?
According to the New York Federal Reserve’s Q4 2025 report, total U.S. household debt stands at $18.8 trillion. This includes $13.17 trillion in mortgages, $1.28 trillion in credit cards, $1.67 trillion in auto loans, and $1.66 trillion in student loans. Debt grew by $740 billion in 2025 alone.
What percentage of Americans are behind on payments?
The NY Fed reports 4.8% of outstanding household debt is in some stage of delinquency. Student loan delinquency is worst at 9.6% (90+ days late), followed by credit cards at 7.13% transition rate into delinquency. Mortgage delinquency is rising, with transitions to delinquency jumping from 1.09% to 1.38% year-over-year.
Should I use my retirement savings to pay off debt?
No. Retirement accounts are typically protected in bankruptcy and represent irreplaceable compound growth. A Federal Reserve study found bankruptcy filers are generally better off financially within 2-3 years. Cashing out retirement to pay unsecured debt trades a protected asset for an unprotected one. Explore all options — including bankruptcy — before touching retirement funds.
What should I do if I’m earning good money but falling behind on bills?
First, recognize that this is a math problem, not a personal failure. When costs rise 25% and income doesn’t match, the math breaks for everyone eventually. Take a free assessment like the Find Your Path quiz to understand which debt relief options apply to your specific situation. Consider consulting with a bankruptcy attorney for a free evaluation — it doesn’t commit you to anything, but it gives you information about ALL your options.
(Source: Federal Reserve Bank of New York | Wolf Street | The Wall Street Journal)
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



