

Quick Answer: LVNV Funding LLC is one of the largest debt buyers in the United States. They buy charged-off debts from original creditors — often for pennies on the dollar — and then attempt to collect the full balance from consumers. If LVNV Funding has contacted you or is suing you, you have legal rights: you can demand debt validation within 30 days, dispute inaccurate credit reporting, challenge expired statute of limitations debts, and respond to lawsuits to avoid default judgment. LVNV is owned by Sherman Financial Group and uses Resurgent Capital Services to handle collections.
If a company called LVNV Funding LLC has shown up on your credit report, sent you a collection letter, or filed a lawsuit against you — you’re not alone, and you have more power than you think.
LVNV Funding is one of the country’s largest buyers of charged-off consumer debt. They don’t lend money. They don’t issue credit cards. They buy old debts that the original creditor gave up on — typically for 4 to 10 cents on the dollar — and then pursue consumers for the full amount.
The latest? Another consumer lawsuit has been filed against LVNV Funding in federal court in Florida (Henderson v. LVNV Funding, LLC), alleging violations of consumer protection laws. It’s one of hundreds of such cases filed against the company. Meanwhile, thousands of consumer complaints mentioning LVNV Funding sit in the CFPB’s database.
Who Is LVNV Funding?
LVNV Funding LLC is a debt buyer — not a debt collector in the traditional sense. Here’s the corporate structure you need to understand:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- Sherman Financial Group — The parent company based in New York. They provide the capital to buy massive portfolios of defaulted debt
- LVNV Funding LLC — The entity that legally owns the debt. This is the name that appears on your credit report and on lawsuits
- Resurgent Capital Services — The collection arm, based in Greenville, SC. They make the phone calls, send the letters, and file the lawsuits on LVNV’s behalf
Why This Structure Matters: When LVNV buys your debt, the original creditor (say, a credit card company) has already written it off as a loss and taken a tax deduction. LVNV typically pays pennies on the dollar for these portfolios. If they collect even a fraction of the face value from you, they profit enormously. This is important context when you’re negotiating.
What LVNV Funding Has Been Accused Of
Consumer lawsuits and CFPB complaints against LVNV Funding consistently allege the same problems:
- Collecting on debts already paid — Attempting to collect balances that were settled, paid in full, or discharged in bankruptcy
- Suing on time-barred debts — Filing lawsuits after the statute of limitations has expired, hoping consumers won’t know to raise the defense
- Inflating amounts owed — Adding fees, interest, or charges beyond what the original creditor was owed
- Failing to validate debts — Not providing proper documentation when consumers request verification
- Inaccurate credit reporting — Reporting debts to credit bureaus with wrong amounts, dates, or account information
- Not disclosing dispute rights — Failing to inform consumers of their right to dispute the debt within 30 days
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Your Rights When LVNV Funding Contacts You
The Fair Debt Collection Practices Act (FDCPA) gives you specific protections. Use them.
You Have the Right To
- Demand validation — Within 30 days of first contact, send a written request for debt verification via certified mail
- Stop contact — Send a cease-and-desist letter and they must stop calling (though they can still sue)
- Dispute the debt — Challenge the amount, the ownership, or whether the debt is even yours
- Sue for violations — If they break the FDCPA, you can collect up to $1,000 in statutory damages per violation plus actual damages
They Are Prohibited From
- Calling before 8am or after 9pm
- Threatening jail or arrest (debt is civil, not criminal)
- Using profanity, harassment, or abusive language
- Contacting your employer about the debt
- Misrepresenting the amount owed
- Collecting after the statute of limitations without disclosure
If LVNV Funding Is Suing You
LVNV Funding files thousands of collection lawsuits every year across the country. Here’s what you need to know:
Do NOT Ignore a Lawsuit. If LVNV files a lawsuit and you don’t respond, the court will enter a default judgment against you. That means LVNV wins automatically — and can garnish your wages, freeze your bank accounts, or put a lien on your property. Even if you think the debt isn’t valid, you MUST file an answer within the deadline (usually 20-30 days depending on your state).
- File an answer — Respond to every allegation in the complaint. Deny anything you’re not sure about
- Raise affirmative defenses — Statute of limitations expired? They can’t prove they own the debt? The amount is wrong? These are defenses you must raise in your answer or lose them
- Demand proof of ownership — LVNV bought your debt through a chain of assignments. Make them prove every link in that chain. Many debt buyers can’t
- Check the statute of limitations — Each state has a time limit for filing debt collection lawsuits (typically 3-6 years for credit card debt). If the debt is time-barred, that’s a complete defense
- Consider your options — Settling, fighting, or filing bankruptcy are all valid choices depending on your situation
Should You Settle With LVNV Funding?
Because LVNV bought your debt for pennies, they have room to negotiate. Settlements of 40-60% of the balance are common — and some consumers have settled for even less.
The Settlement Math: If LVNV bought your $5,000 credit card debt for $300 (6 cents on the dollar), and you settle for $2,000 (40% of the balance), LVNV still makes $1,700 profit. They’ll take that deal. But remember: forgiven debt over $600 may be reported on a 1099-C and could be taxable income. Factor that into your math.
If you settle, get the agreement in writing before you send any money. The agreement should state: the exact amount being accepted, that it’s in full satisfaction of the debt, and that LVNV will update credit bureaus to show the account as settled.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
What to Do Right Now
- Don’t panic — A collection letter or lawsuit is stressful, but debt is math. It can be solved
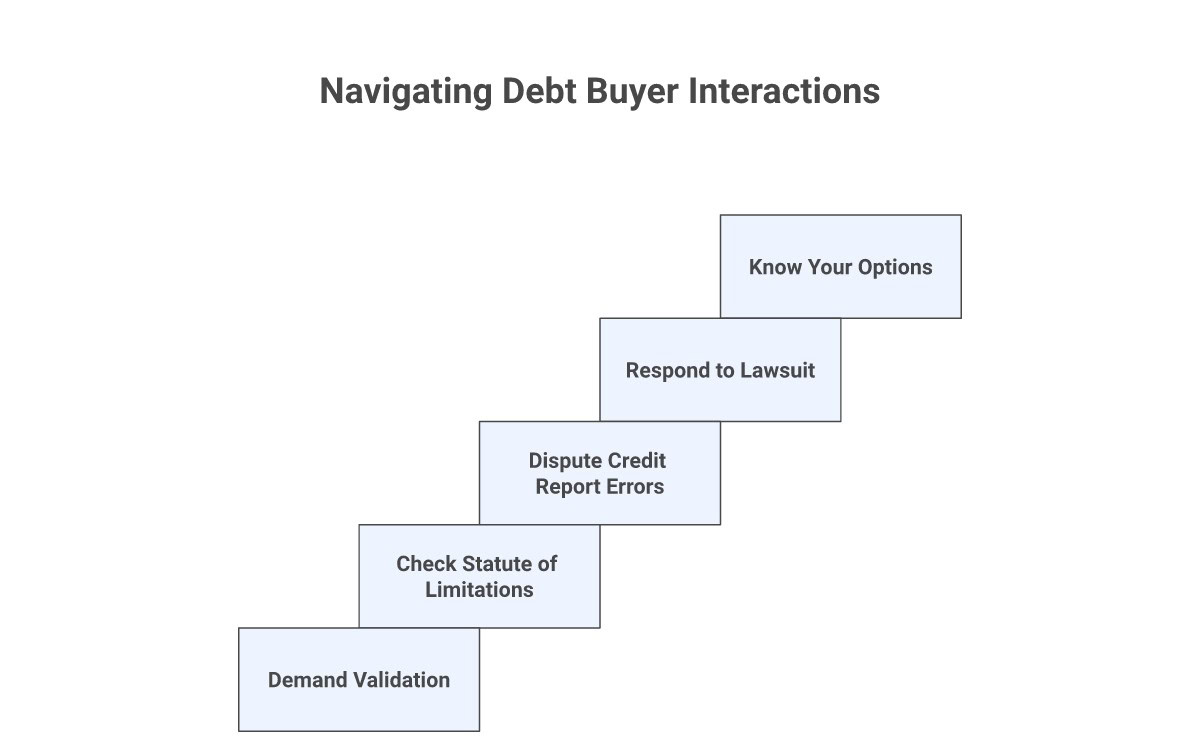
- Send a validation letter — Within 30 days of first contact, demand proof of the debt in writing via certified mail
- Check your credit report — Verify what LVNV is reporting. Dispute any inaccuracies directly with the credit bureaus
- Know your state’s statute of limitations — If the debt is too old, LVNV can’t legally sue you for it
- Consider ALL your options — Take the free Find Your Path quiz to understand what approach works best for your specific situation
- Talk to a consumer attorney — Many FDCPA attorneys offer free consultations and work on contingency (they get paid only if you win)
Before You Sign Anything: If LVNV or Resurgent Capital sends you a settlement offer or payment agreement, run it through the Contract Decoder first. It’s free — and it’s your last chance to spot red flags before you commit.
Debt is math, not morality. A debt buyer paid pennies for your account. Don’t let them collect dollars through fear.— Steve Rhode
Key Takeaways
- LVNV Funding is a debt buyer owned by Sherman Financial Group — they buy charged-off debts for pennies on the dollar
- Over 8,800 CFPB complaints mention LVNV Funding, citing collection on paid debts, time-barred debts, and inaccurate reporting
- You have 30 days from first contact to send a written validation request — use it
- Never ignore a lawsuit — file an answer or risk default judgment with wage garnishment
- Settlements of 40-60% are common because LVNV has huge profit margins on purchased debt
- The FDCPA protects you from harassment, threats, and deceptive practices — violations can be worth $1,000+ per incident
Frequently Asked Questions
Is LVNV Funding a legitimate company?
Yes. LVNV Funding LLC is a legitimate debt buyer owned by Sherman Financial Group. They are registered to do business in most states and hold an A+ BBB rating. However, “legitimate” doesn’t mean every collection attempt is valid. Always demand debt validation and verify the amount owed before paying anything.
Can LVNV Funding sue me for old debt?
They can file a lawsuit, but if the debt is past your state’s statute of limitations, you have a complete defense. Statute of limitations periods vary by state — typically 3 to 6 years for credit card debt. If LVNV sues you on a time-barred debt, you must raise the statute of limitations defense in your answer or the court won’t apply it automatically.
Should I pay LVNV Funding or ignore them?
Ignoring them is the worst option if they’ve filed a lawsuit — you’ll get a default judgment. If they’ve only sent letters, you have options: demand validation, negotiate a settlement (typically 40-60% of the balance), or consult a bankruptcy attorney. The right choice depends on the amount, your financial situation, and whether the debt is within the statute of limitations.
How do I get LVNV Funding off my credit report?
If the information is inaccurate, dispute it directly with the credit bureaus (Equifax, Experian, TransUnion) in writing. If the information is accurate, it will typically fall off after 7 years from the date of first delinquency with the original creditor. You can also negotiate “pay for delete” as part of a settlement, though LVNV is not obligated to agree to this.
What’s the difference between LVNV Funding and Resurgent Capital Services?
LVNV Funding LLC is the legal owner of the debt — their name appears on credit reports and lawsuits. Resurgent Capital Services is the company that actually contacts consumers, makes collection calls, and manages the accounts on LVNV’s behalf. Both are owned by the same parent company, Sherman Financial Group.
(Source: Upsolve – LVNV Funding Guide | CFPB Debt Collection Rights | Top Class Actions)
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



