

Quick Answer: A Georgia woman filed a federal lawsuit on February 12, 2026 accusing Transworld Systems Inc (TSI) of placing a $3,318 debt on her credit reports at all three bureaus — Experian, Equifax, and TransUnion — without any prior notice or validation, allegedly tanking her credit score by 100 points and triggering a utility deposit. The lawsuit alleges violations of the Fair Debt Collection Practices Act (FDCPA) and the Fair Credit Reporting Act (FCRA) — and the tactic it describes has a name: “debt parking.”
If you’ve found Transworld Systems (TSI) on your credit report, this lawsuit tells you a lot about what they’re legally required to do — and what they allegedly didn’t.
TSI has 18,700 complaints filed against them with the Consumer Financial Protection Bureau (CFPB), according to the CFPB complaint database. The federal government has already taken enforcement action against them once, in 2017, resulting in a $2.5 million civil penalty. And now they’re back in federal court.
What the New Lawsuit Says
A Georgia woman (proceeding pro se, meaning without an attorney) filed a complaint on February 12, 2026 in the U.S. District Court for the Northern District of Georgia, Atlanta Division. The case is Butkus v. Transworld Systems Inc (TSI), Case No. 1:26-cv-00816-MHC-JHR.
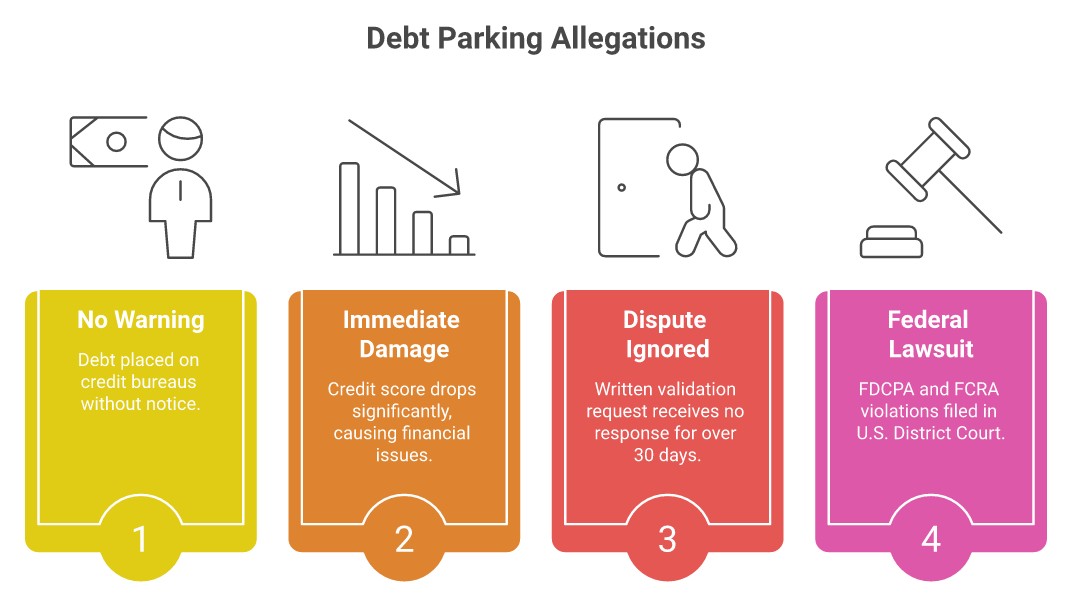
Here’s what the complaint alleges, step by step:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- November 25, 2025: TSI placed a $3,318 alleged debt on the plaintiff’s Experian, Equifax, and TransUnion credit reports. According to the complaint, this was the first communication TSI had with the plaintiff about the debt — no letter, no phone call, no validation notice. Just a tradeline appearing on all three bureaus.
- December 3, 2025: Before she could even respond, the plaintiff was required to pay a $250 deposit to Sawnee EMC for electricity service because of the credit hit from the TSI entry, according to the complaint.
- December 5, 2025: She sent TSI a Notice of Dispute and Request for Validation via USPS certified mail, disputing the alleged debt and requesting competent evidence such as a contract bearing her signature.
- December 9, 2025: TSI marked the account “disputed by consumer” with the credit reporting agencies — but still did not delete it.
- More than 30 days passed without TSI providing any validation, verification, or documentation.
- January 12, 2026: She sent a second certified notice after TSI failed to validate. TSI received it.
- January 27, 2026: TSI pulled her credit report from TransUnion — with no permissible purpose, according to the complaint.
- February 3, 2026: TSI notified the CFPB they had concluded their investigation and requested deletion from consumer reporting agencies — while simultaneously claiming they had “validated” the account, though they provided no original contract, account statements, or signature.
The outcome as of filing? Experian and TransUnion deleted the entry. Equifax, according to the complaint, continued to report based on TSI’s claimed verification. The plaintiff is still fighting one of three bureaus — nine weeks after a debt appeared with no warning.
Key Detail: The complaint states the original creditor had already written off the debt entirely. TSI was not the original creditor — it was attempting to collect a debt that had already been charged off. According to the complaint, the original creditor’s prior write-off should have eliminated the debt’s collectability.
What Is “Debt Parking”?
The complaint uses a specific term that’s worth understanding: “debt parking.”
The CFPB defines debt parking as a practice where collectors report debts to consumer reporting agencies without intent or ability to validate, solely to coerce payment. The logic of the scheme is cold math: a surprise negative entry on your credit report creates pressure. You need a loan. You’re applying for an apartment. A utility is checking your credit. Suddenly a collection account appears. You may not even know if the debt is legitimate — but you pay it to make the problem go away before it costs you more.
The FTC has described debt parking as an illegal debt collection practice. The CFPB has pursued enforcement actions against companies that use it. The lawsuit against TSI directly cites the term and asks the court to declare TSI’s conduct unlawful.
A debt collector hitting your credit report without warning — before a single letter or call — isn’t a coincidence. It’s a tactic. The law was written to stop exactly this.— Steve Rhode, GetOutOfDebt.org
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
What the FDCPA Actually Requires
The Fair Debt Collection Practices Act has been federal law since 1977. It exists specifically because of tactics like the one alleged here. Here’s what it requires that TSI allegedly didn’t do:
✗ What TSI Allegedly Did
- Placed debt on credit reports as first “communication”
- No written validation notice within 5 days
- Continued collection activity (credit reporting) after receiving written dispute
- Failed to validate after 30+ days and multiple demands
- Pulled credit report with no permissible purpose
- Claimed to “validate” without providing any original contract or account statements
✓ What the Law Requires
- Provide written validation notice within 5 days of first direct communication (15 U.S.C. § 1692g(a))
- Cease collection activity — including credit reporting — after receiving written dispute, until validation is provided (15 U.S.C. § 1692g(b))
- Not use false, deceptive, or misleading representations (15 U.S.C. § 1692e)
- Not communicate false credit information (15 U.S.C. § 1692e(8))
- Conduct a reasonable investigation after dispute (15 U.S.C. § 1681s-2)
- Only pull credit report with a permissible purpose (15 U.S.C. § 1681b(f))
The Damages Alleged — Real and Specific
I’ve been helping people with debt since 1994, and one thing I consistently see underestimated is the real-world cost of inaccurate collection tradelines. The Butkus complaint lists hers specifically. According to the complaint, the alleged damages include:
Plus lost funding opportunities, anxiety, depression, loss of sleep, and headaches — all documented in the complaint as damages the court is being asked to remedy.
A 100-point credit score drop from a single unauthorized collection entry can mean the difference between loan approval and denial, a lower interest rate and a higher one, qualifying for an apartment or being turned away. For one tradeline that the original creditor had already written off.
Important Note: This is an active federal lawsuit — not a settlement or a verdict. The allegations are made by the plaintiff. Transworld Systems has not yet filed a response, and the case has not been decided. The court filing is a public document available through CourtListener.
TSI’s History With Regulators
This isn’t TSI’s first time in federal enforcement proceedings. In 2017, the CFPB issued a consent order against Transworld Systems for filing false or misleading affidavits, providing false or misleading testimony, and filing debt collection lawsuits when TSI could not prove the debt was owed. The CFPB ordered a $2.5 million civil penalty.
As of today, 18,700 complaints have been filed against Transworld Systems Inc with the CFPB.
What to Do If TSI Appears on Your Credit Report
- Pull your free credit reports immediately at AnnualCreditReport.com — all three bureaus. See exactly what TSI reported, when, and for how much.
- Send a written debt validation letter to TSI via USPS certified mail with return receipt. This creates a paper trail and legally triggers the validation requirements under 15 U.S.C. § 1692g. Keep the certified mail receipt and return receipt card.
- Dispute with all three bureaus — Experian, Equifax, and TransUnion — in writing, simultaneously. Each bureau has 30 days to investigate under the FCRA.
- File a CFPB complaint at consumerfinance.gov. The CFPB forwards complaints to the company for a response. This creates an official record.
- Document everything — dates, certified mail tracking, dispute confirmation numbers, credit score screenshots. If you need to sue, you’ll need a paper trail.
- Consider consulting an FDCPA attorney — FDCPA violations allow consumers to sue for actual damages, statutory damages up to $1,000, and attorney’s fees. Many consumer rights attorneys take these cases on contingency.
Dealing With a Debt Collector? Before you pay anyone anything or sign any agreement, run it through the Contract Decoder. It’s free and can flag red flags before they cost you more than a utility deposit. Also try the Find Your Path quiz to understand what options make sense for your specific situation.
Key Takeaways
- A federal lawsuit filed Feb 12, 2026 accuses TSI of placing a $3,318 debt on all three credit bureaus without any prior notice — alleged “debt parking”
- Debt parking is a practice the CFPB and FTC have identified as an illegal collection tactic
- Under the FDCPA, collectors must send a written validation notice within 5 days of first contact — credit reporting can itself constitute “first contact”
- TSI has 18,700 CFPB complaints and a prior $2.5 million civil penalty from 2017
- If TSI appears on your credit report, dispute it in writing via certified mail immediately — and document everything
Free Tool — Debt Validation Letter Generator: Being contacted by a debt collector? The free Debt Validation Letter Generator creates a personalized FDCPA validation letter in seconds — forcing the collector to prove the debt is real before they can continue. Generate My Letter →
Frequently Asked Questions
What is debt parking and is it illegal?
Debt parking is when a debt collector reports a debt to the credit bureaus without first notifying the consumer or intending to validate the debt — using the sudden credit hit to pressure payment. The CFPB and FTC have identified debt parking as an illegal debt collection practice that violates the FDCPA. A collector must send a validation notice within five days of first contact, and credit reporting can constitute a first “communication” under the FDCPA.
What should I do if Transworld Systems (TSI) shows up on my credit report?
Pull all three credit reports immediately, send TSI a written debt validation letter via certified mail, and file written disputes with Experian, Equifax, and TransUnion simultaneously. File a complaint with the CFPB at consumerfinance.gov. If TSI cannot validate the debt, it must cease reporting it. If your dispute is ignored, consulting an FDCPA attorney is worth considering — many take these cases on contingency, and violations can entitle you to statutory damages up to $1,000 plus legal fees.
Has Transworld Systems been in trouble with regulators before?
Yes. In 2017, the CFPB issued a consent order against TSI and ordered a $2.5 million civil penalty for filing false or misleading affidavits and pursuing debt collection lawsuits when TSI could not prove the debt was owed. As of February 2026, 18,700 consumer complaints have been filed against TSI with the CFPB.
Can I sue a debt collector who damages my credit without notice?
Under the FDCPA, you can sue a debt collector for actual damages, statutory damages up to $1,000 per violation, and attorney’s fees and costs. Under the FCRA, you can sue furnishers like debt collectors for failing to conduct a reasonable investigation after a dispute. Many consumer rights attorneys take FDCPA cases on contingency, meaning no upfront cost to you. Document everything — dates, amounts, certified mail receipts, credit score screenshots — from the moment you discover the entry.
What is Transworld Systems (TSI)?
Transworld Systems Inc (TSI) is a debt collection agency that collects debts on behalf of original creditors, including student loan servicers, healthcare providers, and other businesses. They operate as a “third-party collector,” meaning they are not the original creditor. As a debt collector under the FDCPA’s definition, they are bound by the FDCPA’s consumer protection requirements. TSI has collected on behalf of National Collegiate Student Loan Trusts and other clients, and has faced both CFPB enforcement action and thousands of consumer complaints.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



