
Part of the Debt After Death Hub: This post is one piece of my complete Debt After Death: Complete Guide — what you actually owe when a family member dies, how to stop collector harassment, joint account rules, community property state rules, and the filial responsibility laws collectors invoke to scare you.
Quick Answer: About 29 states have “filial responsibility” laws that can legally require adult children to pay their parents’ nursing home and medical bills — even if you never signed a thing. Enforcement is rare, but a Pennsylvania court forced one son to pay $93,000 in his mother’s nursing home bills. With nursing home costs now averaging $119,340 per year, these laws are worth understanding before you need to.
You didn’t sign any contract. You didn’t choose the nursing home. You may not even have known how serious the debt was getting. But if you live in one of roughly 29 states, there’s a law on the books — dating back to Elizabethan England — that could make you legally responsible for your parent’s care bill.
Most people have never heard of filial responsibility laws. Estate planning attorneys know about them. Nursing home billing departments know about them. But adult children navigating a parent’s health crisis rarely do — until a lawsuit arrives.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
What Are Filial Responsibility Laws?
The word “filial” comes from Latin meaning “son” or “daughter.” Filial responsibility laws are statutes that impose a legal duty on adult children to support indigent parents — parents who cannot financially support themselves. If you’re wondering about the broader question of whether you’re obligated to support struggling parents at all, I address that in detail in Am I Responsible for Supporting My Broke Parents Financially?.
These laws aren’t a modern invention. They trace directly to the Elizabethan Poor Law of 1601, which required family members to support relatives who could not support themselves. American colonies adopted similar principles. After the welfare state expanded in the 20th century, these laws largely fell dormant — but they were never repealed in most states.
Today, nursing homes and long-term care facilities have discovered they can use these old statutes to recover unpaid bills directly from adult children.
Which States Have These Laws?
Approximately 29 states (plus Puerto Rico) have some form of filial responsibility statute. The laws are not identical — each state defines “indigent,” “sufficient ability,” and covered expenses differently.
States with filial responsibility laws include: Alaska, Arkansas, California, Connecticut, Delaware, Georgia, Indiana, Kentucky, Louisiana, Massachusetts, Mississippi, Nevada, New Hampshire, New Jersey, North Carolina, North Dakota, Ohio, Oregon, Pennsylvania, Rhode Island, South Dakota, Tennessee, Vermont, Virginia, and West Virginia, among others.
If Your State Is on This List: That doesn’t mean you’ll automatically get sued. It means the legal mechanism exists. Whether a nursing home pursues it depends on the circumstances — primarily whether your parent qualifies for Medicaid (which typically eliminates the risk) and whether you have enough income to be worth suing.
The Pittas Case: A $93,000 Wake-Up Call
For years, filial responsibility laws were considered legal curiosities — on the books, rarely enforced. Then Pennsylvania changed that.
In 2012, the Pennsylvania Superior Court issued a ruling in Health Care & Retirement Corp. of America v. Pittas that sent shockwaves through elder law circles.
Here’s what happened: A Pennsylvania woman received skilled nursing care from September 2007 through March 2008, then moved to Greece without paying her bill. The nursing home went after her son, John Pittas. His income exceeded $85,000 per year. The court held him personally liable for the full $93,000 balance.
The court ruled that Pennsylvania’s filial responsibility statute did not require the nursing home to exhaust other possible sources of income first. John Pittas could be sued directly, regardless of whether other resources existed.
A second Pennsylvania case, involving the Linderkamp family, resulted in an adult son being held liable for $104,000 in nursing home debt after a court found he had received property from his parents at below-market value — essentially an attempted asset shield that didn’t hold up.
Pennsylvania is the primary state where filial responsibility is actually enforced. But 28 other states have the same power on their books — and nursing home billing departments are increasingly aware of it.— Steve Rhode
What These Laws Actually Cover
Filial responsibility laws most commonly apply to:
- Nursing home and long-term care costs — The most frequently pursued category
- Hospital and medical care bills — When parents cannot pay
- Basic necessities — Food, clothing, shelter (in some states)
- Mental health services — Covered in a few states, including Arkansas
What these laws don’t typically cover: credit card debt, personal loans, or other consumer debts your parents accumulated. This is specifically about care and support obligations — not general financial liability for your parents’ choices.
Why Enforcement Is Still Rare — But Growing
Most seniors who need nursing home care qualify for Medicaid, the joint federal-state program for low-income individuals. Once a parent qualifies for Medicaid, the state pays for care, and filial responsibility law becomes essentially moot — nursing homes can’t pursue adult children for Medicaid-covered costs.
The Pittas case arose specifically because the mother earned just enough income that she didn’t qualify for Medicaid. That gap — too much money for Medicaid, not enough to pay the bills — is exactly where filial responsibility laws get weaponized.
As nursing home costs continue climbing ($119,340 per year on average, and over $386,000 per year in states like Alaska), more families are landing in that gap. More nursing homes — which operate on thin margins and have become increasingly aggressive about collections — are discovering these old statutes can plug the hole.
The Math Is Getting Worse: In 2007, the Pittas family accumulated $93,000 in debt over six months. At 2026 rates, that same six-month stay would cost roughly $60,000 — still substantial, but inflation in nursing home costs has outpaced most other sectors. A full year of private-room nursing home care now approaches $135,000.
How to Protect Your Family
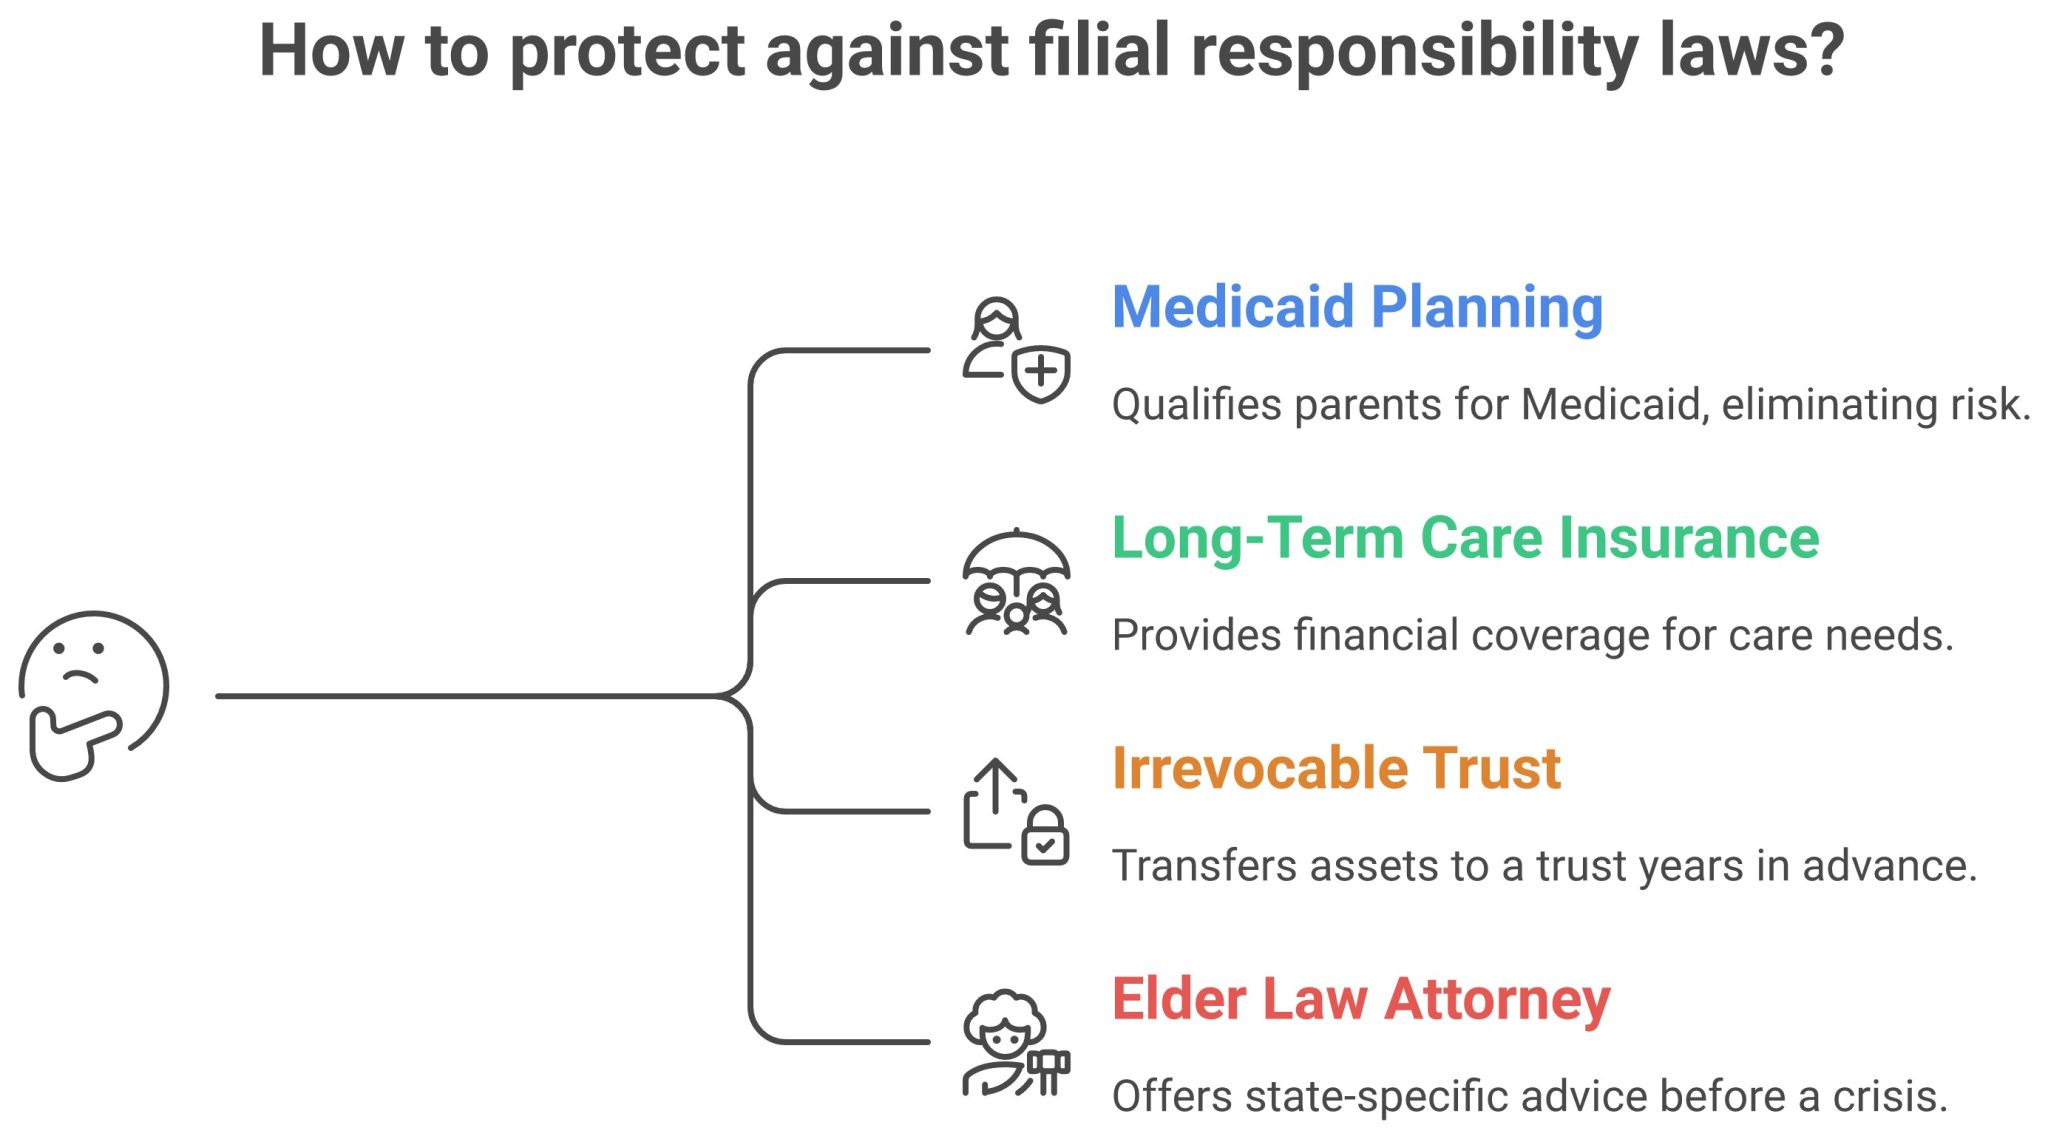
There are meaningful steps you can take to reduce this risk — but the key word is “early.” These strategies work best when put in place before a crisis, not after the nursing home bills start accumulating.
✓ Effective Protection Strategies
- Medicaid planning — Work with an elder law attorney to legally structure your parents’ finances for Medicaid eligibility. This is the most effective protection because Medicaid eliminates the debt nursing homes would otherwise pursue.
- Long-term care insurance — Encourage parents to purchase long-term care insurance or a life insurance policy with a long-term care rider. This keeps care costs off the table entirely.
- Irrevocable trusts — Structured well in advance (years, not weeks), certain trusts can legally protect assets. Courts scrutinize recent transfers as potential fraud.
- Elder law attorney consultation — Especially if parents have significant assets, health conditions that suggest future care needs, or live in Pennsylvania or other states with active enforcement.
✗ What Won’t Protect You
- Last-minute asset transfers — Courts treat sudden transfers as fraudulent conveyance. Moving money days before a nursing home admission won’t help and may make things worse.
- Assuming you’re safe because you didn’t sign anything — Filial responsibility doesn’t require your signature. Statutes impose the duty.
- Ignoring it and hoping for the best — Pennsylvania enforcement is active. Other states may follow as nursing home debt grows.
Not Sure Where to Start? Use the Find Your Path quiz to get personalized guidance on your financial situation — including conversations about family financial obligations and protection strategies.
Key Takeaways
- About 29 states have laws that can hold adult children responsible for parents’ nursing home and medical debt — even without signing anything
- The 2012 Pittas case established that nursing homes can sue adult children directly, resulting in a $93,000 judgment
- Enforcement remains rare nationwide but is real in Pennsylvania, and nursing homes are increasingly aware these laws exist
- The most effective protection: ensure parents qualify for Medicaid through legitimate elder law planning, or carry long-term care insurance
- Medicaid qualification eliminates the risk — these laws primarily bite families in the “gap” between qualifying for Medicaid and being able to afford care
Frequently Asked Questions
Can a nursing home sue me for my parent’s bills even if I never agreed to pay?
Yes, in states with filial responsibility laws. These statutes impose a legal duty regardless of whether you signed anything. Pennsylvania courts have confirmed this directly — in the Pittas case, the son never signed a guaranty agreement, yet was held liable for $93,000. The legal obligation comes from the statute, not from a contract.
If my parent qualifies for Medicaid, am I still at risk?
No — Medicaid eliminates this risk. When Medicaid pays for care, nursing homes cannot pursue adult children under filial responsibility laws for those covered costs. The Pittas case happened specifically because the mother earned too much to qualify for Medicaid, leaving her bills uninsured. Getting parents properly enrolled in Medicaid through elder law planning is the most effective protection available.
How do I know if my state has a filial responsibility law?
Consult an elder law attorney in your state — this is worth a one-hour consultation fee. States with filial responsibility laws include Pennsylvania, California, North Carolina, Virginia, New Jersey, Massachusetts, Connecticut, and more than 20 others. The law in each state differs in what it covers and how “ability to pay” is defined, so state-specific advice matters.
My parent recently transferred assets to me. Does that make me more vulnerable?
Potentially, yes. Courts examining filial responsibility cases scrutinize asset transfers, particularly recent ones. If a court finds your parent transferred assets to you at below-market value or specifically to avoid paying for care, it can factor that into your liability. The Linderkamp case in North Dakota involved exactly this scenario, resulting in a $104,000 judgment. Plan years in advance, not after a health crisis begins.
What is the statute of limitations on these claims?
It varies by state. In Pennsylvania, nursing homes generally have four years to file under the statute of limitations for contract actions. In other states, the timeframe differs. Importantly, the clock may not start running until the debt becomes certain — meaning years of nursing home care could accumulate before the limitation period even begins. Consult an elder law attorney in your state for current rules.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If your parent has already died and the nursing home is now billing you personally, see my crisis guide on what to check before you pay a nursing home bill after your parent’s death — including the admission-agreement clause facilities use to blur agent versus guarantor.



