

Quick Answer: Credit card companies are required by federal law to file their marketing contracts with colleges and alumni groups with the CFPB. My AI engine read them. The contracts reveal your school is obligated to hand over student mailing lists, required to send a minimum number of marketing emails per year, and in some cases prohibited from even telling you who their next card partner will be without the bank’s approval.
See the full payment picture: Credit card companies paid U.S. colleges and alumni groups $576 million between 2009 and 2024. My AI engine analyzed 15 years of CFPB data to find out exactly which schools collected the most — and why the pipeline never fully closed.
My AI engine analyzed 126 college credit card marketing contracts filed with the Consumer Financial Protection Bureau. What’s inside those contracts is more revealing than any dollar figure — and most people have no idea these documents are public.
The Credit CARD Act of 2009 requires every credit card issuer that has a marketing arrangement with a college or university to file that contract with the CFPB. The filings sit in a public database. Almost nobody reads them.
Here is what your alumni association agreed to on your behalf.
Your School Has a Minimum Quota of Marketing Messages It Must Send You
The Bank of America agreement with the University of Michigan Alumni Association does not leave the volume of marketing up to the alumni association’s discretion. It mandates it.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Under the contract, the Michigan alumni association is required to:
- Send a minimum of 6 direct mail campaigns per year promoting the Bank of America credit card
- Send a minimum of 4 email campaigns per year — including 2 standalone dedicated emails, not bundled with other content
- Run quarterly full-page ads in the alumni magazine
- Maintain a permanent credit card offer on the alumni association website
- Provide 6 banner ad placements in the alumni newsletter
The penalty for falling short: Bank of America can claw back the royalty advance it already paid.
The alumni association does not send you credit card emails because it thinks you might benefit from one. It sends them because there is a contract that requires a minimum number of sends, with financial consequences for missing the quota.
The Bank of America / Michigan contract also requires the alumni association to maintain a mailing list of at least 423,000 names and addresses, provided to Bank of America free of charge. The Bank embeds fake “dummy” records in the list to detect if the alumni association shares it with anyone unauthorized. If the association causes a data breach exposing those 423,000 records, the contractual cap on Bank of America’s damages is $150,000 — about 35 cents per person.
Purdue’s Contract Explicitly Includes Incoming Freshmen
Most college credit card agreements involve alumni — graduates who are years removed from campus. The Purdue for Life Foundation’s agreement with Purdue Federal Credit Union is different.
The contract requires Purdue for Life to provide a mailing list of a minimum of 300,000 individuals. The agreement specifies exactly who must be on that list:
“incoming freshmen students, undergraduate students and graduate students”
Not alumni. Current students. Including students who have not yet started their first semester.
The contract notes FERPA compliance. But the explicit inclusion of freshmen, undergraduates, and graduate students — not just alumni — in the credit card marketing pipeline is written directly into the agreement as a contractual obligation.
The contract also includes a $3,000 per day financial penalty against the Purdue for Life Foundation if it fails to deliver those lists within 10 business days of a request, or if it fails to approve credit union marketing materials within 10 business days. The penalty accrues daily until the obligation is fulfilled and is deducted from the foundation’s next royalty payment.
The $3,000/day penalty tells you something important about priorities. The credit union cares about speed of list delivery and marketing approval more than almost anything else in the contract. Fast access to student data is valuable enough to enforce with financial penalties.
Bank of America Controls What Your School Can Say When It Leaves
When the University of Texas Ex-Students Association or USC’s alumni association decides to end its Bank of America relationship and move to a different card issuer, you might expect they could announce that to their members freely. They cannot.
Both Bank of America agreements contain a provision giving the bank approval rights over all termination communications. The alumni association cannot notify its own members about the program ending — or name a replacement issuer — without Bank of America’s blessing.
This is not a standard confidentiality provision. It is a clause that gives the departing bank control over the narrative of its own departure. A school that wants to tell its alumni “we’re moving to a new card partner” must first get the outgoing bank to agree to that message.
Both Bank of America agreements also contain a one-year post-termination non-compete: for 12 months after the agreement ends, the alumni association cannot directly target former cardholders with competing financial products. The relationship ends; the restriction does not.
Penn State Isn’t Selling Credit Cards — It’s Selling Seats on the Team Plane
Penn State-affiliated entities top the 15-year payment database at over $37 million. Looking at the 2024 data, Penn State Sports Properties LLC received $2.55 million from Pennsylvania State Employees Credit Union for just 217 new credit card accounts — a figure that works out to roughly $11,764 per account, the highest in the dataset.
That number is misleading, and the contract explains why.
Penn State Sports Properties’ agreement is not structured as an affinity card royalty at all. It is a 10-year, $25.4 million flat-fee athletic sponsorship. For roughly $2.2 million per year, the credit union receives:
- Scoreboard, field-level, concourse, and suite signage at Beaver Stadium
- Courtside, scoreboard, and concourse signage at the Bryce Jordan Center
- Signage at Pegula Ice Arena
- Radio advertising on the Penn State Sports Network
- TV commercial placement during Penn State broadcasts
- Social media campaigns
- Access to the head football coach for endorsements
- Luxury suite access for football and basketball games
- Season tickets to football and basketball
- Three seats on the Penn State football team’s charter plane for one away game per season
The credit card is attached to a sponsorship deal that was primarily about stadium signage and sports access. When the CFPB data shows 217 new accounts and $2.55 million paid, it is reporting the credit card portion of a much larger contract that was never primarily about credit cards.
Stanford’s Contract Forbids Telling Other Schools What the Deal Is Worth
Stanford Alumni Association’s 10-year agreement with Stanford Federal Credit Union contains a confidentiality clause with unusual specificity. It prohibits Stanford from disclosing the financial terms of the agreement to:
“other colleges, universities, and alumni associations”
This is not standard non-disclosure language. Standard NDAs prevent disclosure to the general public and competitors. This clause is written specifically to prevent Stanford from sharing deal terms with other schools that might use that information in their own negotiations.
The effect is to suppress competition in the market for alumni association credit card deals. If Stanford cannot tell Stanford that it receives $800,000 per year guaranteed — or that it covers mortgages and auto loans in addition to credit cards — other schools cannot use that benchmark when negotiating their own agreements.
The Stanford agreement also covers something no other contract in the dataset does: Stanford alumni mortgage loans and auto loans, not just credit cards. The Stanford Federal Credit Union locked up exclusive financial institution sponsorship rights across credit cards, debit cards, home buying, and car buying in a single 10-year contract.
The Stanford agreement also contains a financial disincentive to leave. If Stanford terminates the agreement, the alumni association must pay the credit union $3.00 per active cardholder account for card reissuance costs. The larger the cardholder base, the more expensive it becomes to switch to a different financial partner. The confidentiality clause suppresses knowledge of alternatives; the exit fee increases the cost of pursuing them.
The University of Michigan Gets Paid Separately From Its Own Alumni Association
In most agreements, the alumni association is the contracting party and receives all payments. The University of Michigan’s Bank of America arrangement is structured differently: both the alumni association and the University itself are co-parties to the contract, with separate payment streams.
Under the agreement, the University of Michigan Alumni Association is required to pay the Regents of the University of Michigan $200,000 per year — a fixed royalty flowing from the alumni association to the university itself, separate from whatever the alumni association retains from Bank of America’s per-account and spend-based royalty payments.
The structure means both entities benefit from the same credit card program. The bank pays the alumni association; the alumni association pays the university. The school’s academic brand and the alumni network are monetized through a single contract but generate two distinct income streams.
Seven Military Academy Contracts Hide All Financial Terms From Public View
USAA Federal Savings Bank has active credit card marketing agreements with alumni associations of all five U.S. military service academies — West Point, the Naval Academy, the Air Force Academy, the Coast Guard Academy, and the Merchant Marine Academy — plus Norwich University and the Texas Aggie Corps of Cadets.
All seven agreements were filed with the CFPB as required by law.
In every single one, the actual payment terms — royalty rates, per-account fees, guarantee amounts, everything financial — are contained in Project Addenda that were not included in the filed documents.
The CFPB disclosure requirement is technically satisfied. The master agreements are on file. The financial terms are not. Seven contracts covering the alumni networks of America’s military academies, and the public cannot determine what any of them pay.
This is the most significant transparency gap in the CFPB’s college credit card disclosure program. The regulation requires filing agreements. It does not appear to require that the agreements be complete enough to be meaningful. USAA filed the frameworks; the money stayed hidden.
BYU Can Exit in 10 Days. The Credit Union Cannot.
The Brigham Young University Alumni Association’s agreement with Mountain America Federal Credit Union contains a clause found in no other contract in the dataset: a unilateral 10-day termination right based on institutional values.
BYU can terminate the agreement with only 10 days written notice if Mountain America engages in conduct “inconsistent with BYU’s values or mission.” No cure period. No financial penalty. Ten days.
Mountain America has no equivalent right. If BYU does something Mountain America objects to, the credit union has no 10-day exit. The clause is one-sided by design.
It reflects something real about the power dynamic in some of these negotiations. BYU’s institutional identity — its relationship with the LDS Church, its values-based reputation — is an asset it was unwilling to fully subordinate to a financial contract. The 10-day clause preserves the ability to act on that identity immediately if needed.
Boeing’s Credit Union Gets to Hire University of Washington Students
The agreement between BECU (Boeing Employees Credit Union) and the University of Washington is worth approximately $9.94 million over six years. Unlike most agreements in the dataset, it was filed under Washington’s Public Records Act obligations — meaning its full terms are disclosed.
Among the benefits BECU receives beyond marketing access:
- “Husky Signature Employer” designation at UW’s Career and Internship Center
- Preferred BECU brand presence at UW career fairs
- Recruiting access to UW students through institutional career programming
- First year only: a co-branded “BECU Fintech Incubator @ CoMotion Labs” innovation space on campus
The credit union is paying $9.94 million for the right to market financial products to UW alumni — and receiving, as part of that same deal, preferred access to recruit UW students as employees. The hiring benefit does not appear as a financial figure anywhere in the agreement. It is compensation that bypasses the payment disclosures entirely.
The Pattern Across All of Them
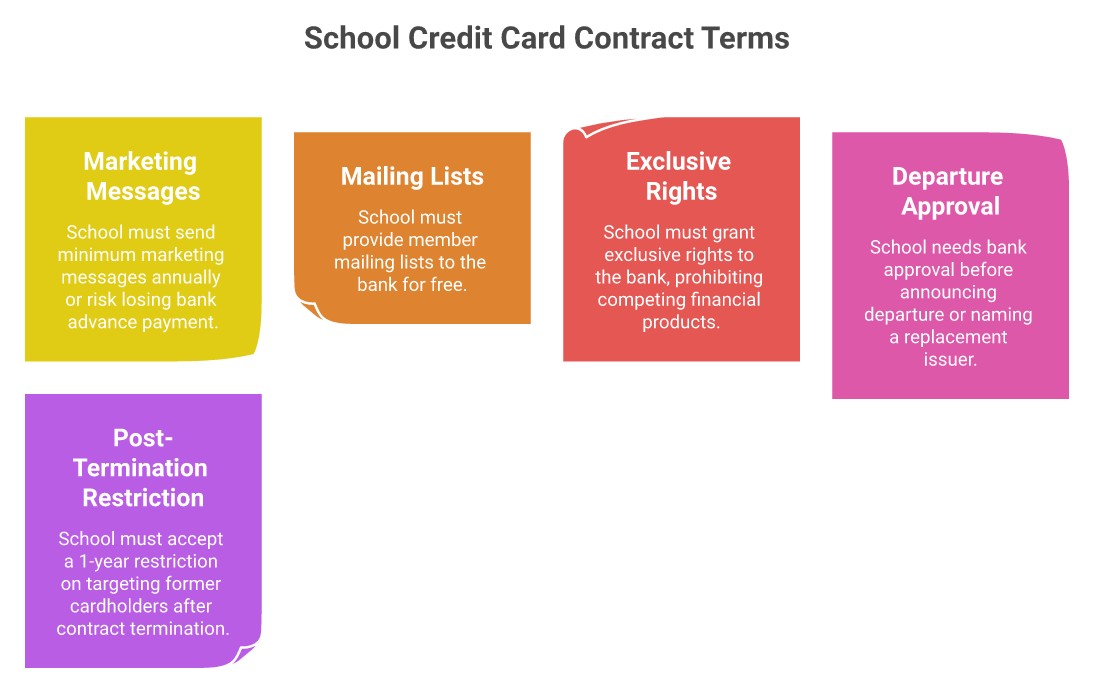
These contracts are different in their details but consistent in their structure. In every case:
- The school agrees to actively promote the financial product — not just permit its logo to appear on a card
- The school provides member data, often to a specified minimum volume, free of charge
- The financial institution receives exclusive rights, preventing the school from offering members a competing product
- The school accepts restrictions on what it can say and do even after the relationship ends
The alumni association’s job, under these contracts, is to be a marketing channel. It has agreed — in writing, with financial penalties for non-performance — to deliver its members to a financial institution on a regular schedule.
That does not make the cards themselves bad products. Some of them may be competitive and genuinely useful. But the recommendation is not neutral. The institution sending you the offer has a contract. It has a quota. It has a financial consequence if it misses that quota.
When your alumni association sends you a credit card email, it is not acting as your financial advisor. It is performing a contractual obligation with financial penalties attached.— GetOutOfDebt.org
What You Can Do With This
- Look up your school’s agreement at the CFPB’s College Credit Card Agreements database — the contracts are public and searchable as PDFs
- Compare the actual card against non-affiliated alternatives before applying — an alumni card marketed under quota is not necessarily the best product available to you
- Understand that exclusivity means your school chose one partner and is contractually prevented from offering you alternatives during the agreement term
- Ask your alumni association what it receives and what it agreed to — the answer is now public record
Key Takeaways
- College credit card contracts require schools to send minimum numbers of marketing emails and mailings per year — with financial penalties for missing quotas
- Purdue’s contract explicitly includes incoming freshmen in its 300,000-minimum marketing list, with $3,000/day penalties for slow delivery
- Bank of America contracts require alumni associations to get bank approval before announcing a switch to a new card issuer
- Penn State’s $25.4M deal is a sports sponsorship that includes team plane seats and football coach endorsements — not a traditional per-account royalty
- Stanford’s contract prohibits sharing terms with other colleges to suppress competitive benchmarking
- All seven USAA military academy contracts hide financial terms in unfiled addenda — technically compliant, practically opaque
- All 126 current contracts are public record at the CFPB’s website
Frequently Asked Questions
- Where can I find my school’s actual contract?
- The CFPB College Credit Card Agreements and Data page lists all currently active agreements. The page is searchable by institution name. Filed contracts are downloadable as PDFs. Not all contracts include complete financial terms — several, particularly USAA’s military academy agreements, place financial specifics in addenda that were not filed.
- Is it illegal for schools to require marketing minimums?
- No. The Credit CARD Act of 2009 requires disclosure of these agreements but does not restrict their terms. Schools can contractually agree to send minimum numbers of marketing messages, provide member data, and accept exclusivity restrictions. The law requires transparency; it does not prohibit the underlying arrangements.
- Do all college credit card contracts work the same way?
- No. The 126 contracts in the 2024 filing represent a wide range of structures. Some use per-account royalties (Bank of America’s typical structure). Some use flat annual fees regardless of card performance (Penn State, Purdue, BECU/UW). Some are narrow logo licenses with no marketing obligations (University of Florida/Commerce Bank at $25,000/year). Scale and sophistication vary dramatically.
- What happened to student credit card marketing after the CARD Act?
- Active agreements dropped from 1,045 in 2009 to 133 in 2024 — an 87% reduction. But the surviving agreements shifted primarily to alumni associations rather than universities directly. Alumni associations are separate legal entities not bound by on-campus marketing restrictions. The pipeline moved off campus; it did not close.
- Are credit unions different from banks in these deals?
- In legal terms, credit unions must file the same CFPB disclosures as banks. In practice, credit union deals in this dataset tend to use flat-fee structures rather than per-account royalties, and are generally smaller in dollar value than the Bank of America agreements. BECU’s $9.94M UW deal is the largest credit union contract in the 2024 filings.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



