
Quick Answer: The Department of Justice announced on February 23, 2026 that CarMax will pay nearly $500,000 to resolve allegations it illegally repossessed vehicles from at least 28 servicemembers without obtaining the court orders required by federal law. Each affected servicemember is entitled to at least $15,000 plus any lost vehicle equity. Under the Servicemembers Civil Relief Act, no lender can repossess a vehicle from an active-duty military member without a court order — period.
If you’re in the military and a lender repossessed your vehicle: This may have been illegal. The SCRA requires a court order before any repossession of a vehicle with a pre-service loan obligation. CarMax’s settlement covers March 2018 through October 2023 — if your vehicle was repossessed during that window, you may be owed compensation. The DOJ will notify affected servicemembers directly, but you should also contact the DOJ’s Military Lending Enforcement Team at servicemembers.gov.
| Case Detail | Information |
|---|---|
| Company | CarMax Auto Finance |
| Announced | February 23, 2026 |
| Law Violated | Servicemembers Civil Relief Act (SCRA), 50 U.S.C. § 3952 |
| Total Settlement | Nearly $500,000 |
| Servicemember Damages | At least $420,000 |
| Civil Penalty | $79,380 |
| Per-Victim Payment | $15,000 + lost vehicle equity |
| Affected Servicemembers | At least 28 |
| Violation Period | March 1, 2018 – October 24, 2023 |
| Enforcement Agencies | DOJ Civil Rights Division + U.S. Attorney’s Office, Eastern District of Virginia |
CarMax Auto Finance illegally repossessed the vehicles of at least 28 servicemembers over more than five years — in some cases, even after those servicemembers told CarMax they were on active military duty.
Federal law couldn’t be clearer on this point. The Servicemembers Civil Relief Act prohibits any lender from repossessing a vehicle without first obtaining a court order if the borrower is on active duty. CarMax skipped that step — repeatedly, and in some cases knowingly.
Three Things CarMax Did Wrong
The DOJ’s investigation found three distinct categories of SCRA violations:
- Repossessed vehicles without court orders — The baseline SCRA requirement is that lenders must get a judge to sign off before taking a servicemember’s vehicle. CarMax bypassed this requirement entirely in at least 28 cases.
- Repossessed vehicles after servicemembers disclosed their military status — This is the most damning finding. Some servicemembers told CarMax they were on active duty. CarMax repossessed anyway.
- Failed to extend protections to reservists with active duty orders — SCRA protections apply the moment a reservist receives orders to report for active duty — not only after they’ve reported. CarMax wasn’t extending protections at that critical window.
“Federal law prohibits businesses from repossessing service members’ vehicles without a court order.”— Assistant Attorney General Harmeet K. Dhillon, DOJ Civil Rights Division
What CarMax Must Pay and Do
Beyond writing checks, CarMax must:
- Notify each affected servicemember within 30 days
- Create a dedicated toll-free phone, email, and website contact point for military members
- Request credit bureaus delete all negative information tied to the illegal repossessions
- Submit revised SCRA compliance policies to the Justice Department for review
- Submit to four years of monitoring and ongoing reporting requirements
CarMax said it “cooperated fully with the DOJ” and that it has already “further strengthened” its compliance program. The company also noted it has provided SCRA relief to more than 26,000 servicemembers since 2003 — a claim that makes the 28 illegal repossessions over five years harder to explain. (Source: DOJ Eastern Virginia)
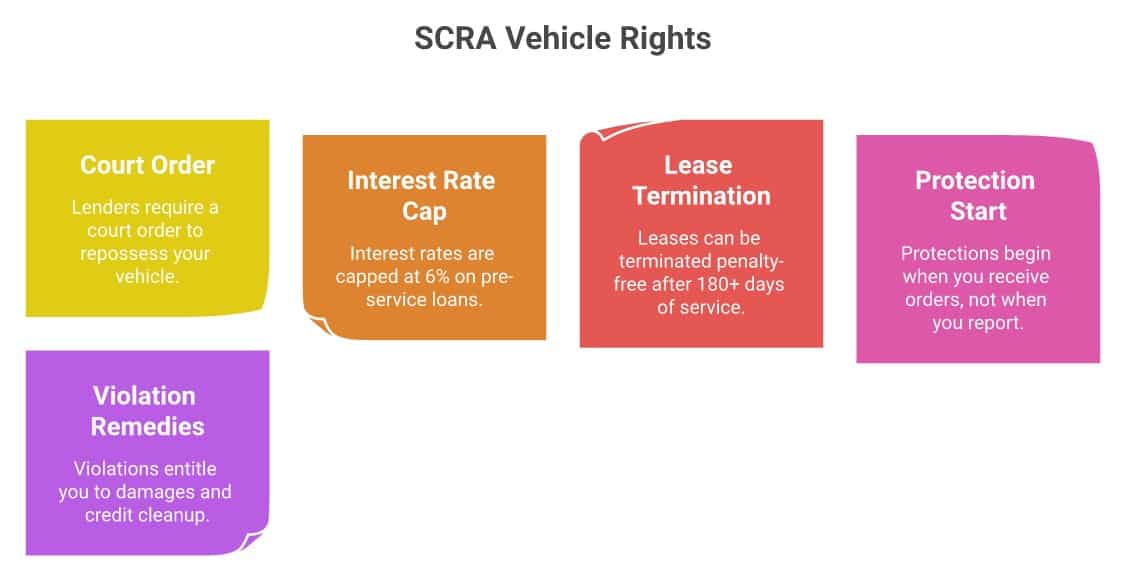
What the SCRA Actually Protects — and What It Doesn’t
The Servicemembers Civil Relief Act doesn’t make military members immune from debt — it controls how creditors can enforce debts. Here’s what it actually does for vehicle loans:
What SCRA Protects
- Lender must obtain a court order before repossessing any vehicle on a pre-service loan
- Interest rate cap: pre-service loans are capped at 6% APR while on active duty
- If you entered the lease before active duty, you can terminate it penalty-free (with 180+ days of service)
- Protections kick in when you receive orders — not when you physically report
- Violations entitle you to damages, and lenders can face civil penalties
What SCRA Does Not Do
- Does not eliminate your payment obligation — you still owe the money
- Does not prevent a lender from pursuing a court order — it just requires one
- Does not cap interest on loans taken out after active duty begins
- Does not protect family members’ debts unless they’re co-signers on your accounts
- Does not cover business debts — only personal obligations
This isn’t a one-time problem. The DOJ has recovered over $484 million for more than 149,000 servicemembers through SCRA enforcement since 2011. CarMax joins a pattern of auto lenders — including New City Funding Corp. (2023) and BayPort Credit Union (2022) — who were caught doing the same thing. The pattern is consistent: lenders fail to screen for military status before repossessing. (CFPB: Military auto loan rights)
Federal prosecutors are also going after individuals — a Chicago man just received 27 months for a scam targeting active-duty troops through social media.
If You’re in the Military and Worried About Your Auto Loan
- Tell your lender immediately when you receive orders. Put it in writing. Keep a copy. This creates a paper trail that protects you if they fail to apply SCRA protections.
- Request the 6% interest rate cap in writing. Send a written request plus a copy of your military orders to your lender. They must apply it retroactively from the date you entered service.
- If your car was repossessed while you were on active duty, consult a JAG attorney immediately. Military legal assistance offices provide free legal services. They handle SCRA cases regularly.
- File a complaint with the DOJ if you believe your SCRA rights were violated. Visit servicemembers.gov or call 1-800-514-0301.
- Check your credit report. If a lender repossessed your vehicle without a court order, they must clean up your credit. If they didn’t, dispute it and reference the SCRA violation.
Key Takeaways
- CarMax will pay nearly $500,000 after illegally repossessing at least 28 servicemembers’ vehicles without court orders
- At least $420,000 goes directly to affected servicemembers — $15,000 minimum each, plus lost equity
- CarMax continued repossessing vehicles even after some owners disclosed they were on active duty
- The SCRA requires a court order before any vehicle repossession of an active-duty servicemember — no exceptions
- DOJ has recovered $484M+ for 149,000+ servicemembers since 2011 — this is an ongoing, systemic problem
- If your vehicle was illegally repossessed, contact the DOJ or your base’s JAG office immediately
Related: can a debt collector take my car.
Frequently Asked Questions
Can a lender repossess my car while I’m on active military duty?
Only with a court order. The Servicemembers Civil Relief Act requires any lender to obtain a court order before repossessing a vehicle if the borrower has an obligation that originated before or during active duty service. CarMax’s $500,000 DOJ settlement in February 2026 resulted from bypassing this requirement at least 28 times between March 2018 and October 2023. If a lender repossesses your vehicle without a court order while you’re on active duty, that is a federal SCRA violation.
Who qualifies for SCRA vehicle repossession protections?
Active duty servicemembers in all branches of the military, including the Army, Navy, Marine Corps, Air Force, Space Force, and Coast Guard. Reservists and National Guard members are protected from the moment they receive orders to report for active duty — not just after they’ve physically reported. This distinction was specifically identified in the CarMax settlement: CarMax failed to protect reservists who had received orders but hadn’t yet reported.
What happens if I was affected by CarMax’s illegal repossessions?
The DOJ settlement requires CarMax to notify each of the at least 28 affected servicemembers within 30 days. Each affected person is entitled to at least $15,000 plus compensation for any lost vehicle equity. CarMax must also request that credit bureaus delete all negative information associated with the illegal repossessions. If you believe you were affected and haven’t been contacted, reach out to the DOJ’s Military Lending Enforcement program at servicemembers.gov.
Does the SCRA protect reservists when they receive orders?
Yes — and this was one of the specific violations in the CarMax case. SCRA protections begin the moment a reservist receives orders to report for active duty, not when they physically arrive. This is a commonly misunderstood provision. If a lender waits until you’ve already reported before applying protections, they may have already missed the window during which your vehicle could have been illegally repossessed.
What’s the difference between an SCRA violation and a breach of contract?
An SCRA violation is a federal law violation — it triggers DOJ enforcement authority, civil penalties payable to the U.S. government, and mandatory damages to the affected servicemember. A breach of contract is a civil matter between you and the lender. In the CarMax case, the $79,380 civil penalty went to the government; the $420,000+ in damages went to the 28 servicemembers. Both remedies run simultaneously — and the DOJ can enforce on behalf of servicemembers who would otherwise have to navigate the courts themselves.
Source: DOJ Eastern District of Virginia: CarMax to Pay Nearly $500,000 | CFPB: Military Auto Loan Rights Under the SCRA
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Claiming money you are owed is one good day. What you do over the following year is what actually changes your position.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



