

Quick Answer: The Trump administration confirmed in February 2026 that it is actively exploring the sale of portions of the $1.7 trillion federal student loan portfolio to private companies. No final decision has been made, but the plan would transfer ownership — and potentially collection rights — of your federal loans to private lenders. If it happens, key borrower protections like income-driven repayment and Public Service Loan Forgiveness could be at serious risk.
What’s at stake: Private student loans make up only 8% of all student debt but account for 40% of student loan complaints filed with the Consumer Financial Protection Bureau, according to a letter signed by more than 40 members of Congress. That ratio tells you something important about what borrowers gain by keeping loans in the federal system — and what they stand to lose if this goes through.
The Department of Education’s Under Secretary Nicholas Kent confirmed on February 23, 2026 that the administration is in discussions about selling some or all of the federal loan portfolio. “We continue to explore all viable options to reduce the burden on taxpayers by restoring the health of the portfolio,” Kent told reporters. He added that the department has “not taken any final actions or made final decisions.” (Source: The Center Square, Feb. 23, 2026)
The Politico report from October 2025 first surfaced this plan, noting that administration officials had already met with finance executives to discuss it. This wasn’t a rumor — it was a working conversation.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
What the Law Actually Says
Selling federal student loans isn’t legally simple. Under the Higher Education Act of 1965, the Secretary of Education can sell existing Direct Loans — but only with Treasury Department consultation, and only if the sale imposes no net cost to the federal government. That’s a meaningful constraint, and it means any sale would require careful structuring.
The administration’s argument is that federal loans are currently a drain on taxpayers — and that private ownership could generate immediate revenue, reduce federal administrative burden, and create “innovative refinancing options.” Critics say that framing ignores why federal student loans have lower complaint rates in the first place: they come with protections private lenders don’t offer and aren’t required to match.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Borrower Protections That Could Disappear
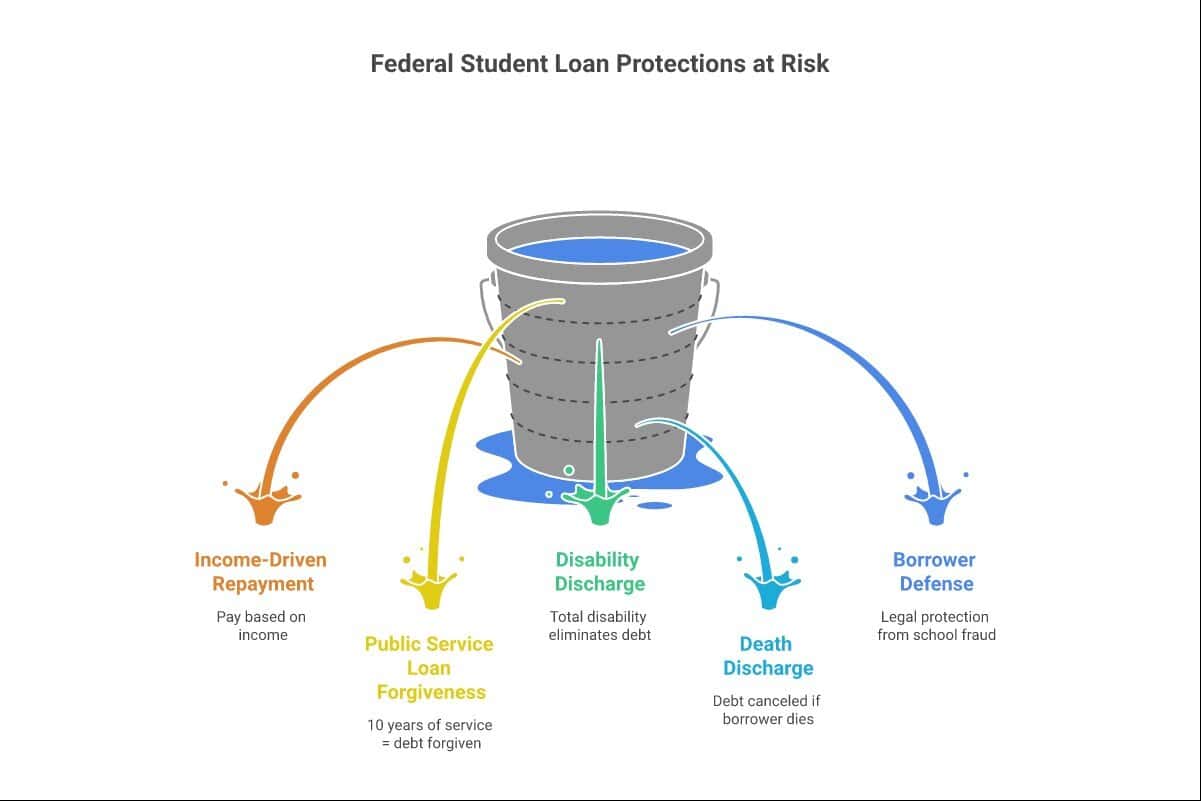
The administration says that “original federal terms of the loans would theoretically remain unchanged” under private ownership. The word “theoretically” is doing a lot of work there. Congressional opponents — including Senators Elizabeth Warren and Bernie Sanders — are not persuaded. In their November 2025 letter, they identified six specific protections that could be at risk:
Protections You Have Now (Federal Loans)
- Income-Driven Repayment (IDR): Pay based on what you earn, not a fixed amount
- Public Service Loan Forgiveness (PSLF): 10 years of payments in qualifying public service = loan forgiven
- Disability discharge: Total and permanent disability eliminates the debt
- Death discharge: Debt is canceled if borrower dies
- Borrower defense to repayment: Defrauded by a predatory school? You can get relief
- Pause and deferment options: Federally guaranteed forbearance during hardship
What Private Lenders Offer (Generally)
- No IDR requirement: Payment plans are contractual, not income-based
- No PSLF equivalents: Private lenders are not required to offer forgiveness programs
- Death/disability at lender’s discretion: Some offer it; many don’t
- No borrower defense: No federal mechanism to dispute a fraudulent institution
- Limited forbearance: What you get is what’s in your contract
- Potentially lower rates: Only if you refinance with strong credit — most can’t
The PSLF question is particularly sharp: If you’ve been making 120 qualifying payments toward Public Service Loan Forgiveness, what happens to that count if your loan is sold? The administration says terms remain unchanged. Legal scholars point out that PSLF is a federal program requiring federal loan ownership — and there’s no private sector equivalent. The administration’s assurance has no enforcement mechanism behind it.
Where This Stands Right Now
As of late February 2026:
- Confirmed: The administration has met with finance executives to discuss the plan
- Confirmed: The Education Department publicly acknowledged the plan is under active exploration
- Not decided: Which loans would be sold, which companies would buy them, timeline, or terms
- Opposition: 40+ members of Congress sent a formal letter in November 2025 demanding details
- Legal question: Whether a sale can satisfy the “no net cost” requirement of the Higher Education Act
What You Should Do Right Now
- Do not refinance your federal loans with a private lender. Refinancing converts your federal loan to a private one permanently — you lose all federal protections immediately and irreversibly. This was bad advice before this news. It’s worse advice now.
- If you’re working toward PSLF, keep documentation. Track your qualifying employer certifications and payment counts. If this sale ever moves forward, documentation of your existing qualifying payments may be critical to any future legal challenge.
- Know your current servicer and loan type. Log in to StudentAid.gov to see exactly what loans you have, what type they are, and who services them. Having this information protects you against any abrupt changes in servicing.
- Contact your senators and representatives. This plan requires no Congressional approval under current law — but Congressional pressure has already shaped how publicly the administration is willing to discuss it. The 40-member opposition letter mattered.
- Watch for any communications about servicer changes. If this moves forward, your servicer would likely notify you. Treat any notification about a servicer transfer as requiring immediate verification through StudentAid.gov — not just the letter you received.
Already struggling with federal student loans? If you’re unable to pay, student loans can be discharged in bankruptcy more often than most people realize. Before you make any decisions about refinancing or repayment, use the free Find Your Path quiz — it walks through your specific situation and identifies which federal options are available to you right now.
Key Takeaways
- The Trump administration confirmed in February 2026 it is actively exploring selling portions of the $1.7 trillion federal student loan portfolio to private companies
- No final decisions have been made — but the Education Department has already met with finance executives about the plan
- Private student loans = 8% of all debt, but 40% of CFPB student loan complaints — the protection gap is real
- At-risk protections include IDR, PSLF, disability discharge, death discharge, and borrower defense
- Do not refinance federal loans with a private lender — that conversion is permanent and eliminates all federal protections immediately
- 40+ members of Congress have formally opposed the plan; it has not yet advanced to final action
Frequently Asked Questions
Could my federal student loans actually be sold to a private company?
Possibly, but no final decision has been made. The Trump administration confirmed in February 2026 that it is “actively exploring” the sale of portions of the $1.7 trillion federal student loan portfolio. Under the Higher Education Act of 1965, the Education Secretary can sell Direct Loans if the sale imposes no net cost to the federal government — meaning a legal pathway exists. What hasn’t been decided is which loans would be sold, to whom, on what timeline, or under what terms.
What happens to Public Service Loan Forgiveness if my loans are sold?
This is the critical unanswered question. PSLF is a federal program that applies only to federal loans — there is no private sector equivalent. The administration has said original loan terms “would theoretically remain unchanged,” but PSLF isn’t a loan term; it’s a federal program. More than 40 members of Congress, including Senators Warren and Sanders, specifically cited PSLF as a program at risk in their November 2025 letter opposing the sale. If you are working toward PSLF, document every qualifying payment and employer certification now.
Should I refinance my federal loans before any sale happens?
No. Refinancing converts your federal loan to a private loan permanently and immediately — you lose income-driven repayment, PSLF eligibility, disability discharge, death discharge, and all other federal protections the moment you refinance. If your loans are later sold to private companies, you still have the federal terms until that happens. Refinancing now gives up those protections voluntarily, with no upside unless you have very strong credit and a significantly lower interest rate on offer. The math rarely works in borrowers’ favor.
Are income-driven repayment plans protected if loans are sold?
Not automatically. Income-driven repayment plans are federal programs tied to the federal loan system. Private lenders can offer flexible payment plans, but they are not required to match IDR terms, and payment amounts are set by contract rather than income. The administration has asserted that original terms would be preserved, but there is currently no legal mechanism requiring private buyers to maintain federal repayment programs indefinitely. Congress has been unable to get specifics from the administration about how borrower protections would be enforced post-sale.
Why does the government want to sell student loans in the first place?
The administration’s stated rationale is to reduce the taxpayer burden and “restore the health of the portfolio.” Selling $1.7 trillion in loans would generate immediate federal revenue and transfer future default risk to private buyers. Critics argue the portfolio’s current “poor health” is partly a policy choice — driven by forgiveness programs and payment pauses — and that selling the loans removes the federal safety net for borrowers without addressing the underlying cost of college. The 8% of private loans generating 40% of CFPB complaints suggests private ownership does not historically produce better outcomes for borrowers.
Sources: The Center Square — Trump Admin Confirms Exploring Student Loan Sale (Feb. 23, 2026) | Rep. Pressley — Congressional Opposition Letter (Nov. 2025) | Higher Ed Dive — Democrats Warn Against Sale
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



