
Quick Answer: To stop a wage garnishment, you have four options: negotiate a settlement directly with the creditor, claim a legal exemption (head of household, low income, or state protections), challenge the underlying judgment if it was improper, or file bankruptcy — which triggers an automatic stay that stops garnishment the same day you file. If you live in Texas, Pennsylvania, North Carolina, or South Carolina, private creditors can’t garnish your wages at all. Social Security cannot be garnished by credit card companies or private debt collectors.
If your paycheck just got hit, stop and breathe for a second. I know it feels like the money is gone and there’s nothing you can do — but that’s not true. A wage garnishment is not the end of the story. It’s actually the beginning of a negotiation, and you have more leverage than you think.
I’ve helped people navigate wage garnishment for three decades. The first thing I tell every single one of them: the creditor got a court judgment, which means they already won that battle. But knowing how to stop a wage garnishment — or at minimum reduce what’s being taken — is a completely different fight, and it’s one you can win.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What Is Wage Garnishment and How Does It Work?
Wage garnishment is a court-ordered process where a creditor — after winning a lawsuit against you — instructs your employer to withhold a portion of your paycheck before you ever see it. The money goes directly to the creditor.
The process typically works like this: a creditor sues you, wins a judgment, then files a writ of garnishment with the court, which gets served on your employer. Your employer is legally required to comply — they have no choice in the matter, and you can’t ask them to ignore it.
Related: what to do if the state says you were overpaid unemployment.
One important protection: Federal law (Title III of the Consumer Credit Protection Act) prohibits your employer from firing you because your wages are being garnished — for any single debt. They can’t retaliate. If they do, that’s a federal violation.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
How Much Can They Actually Take? Federal Garnishment Limits
This surprises a lot of people: federal law caps how much any creditor can garnish. For most consumer debts (credit cards, personal loans, medical bills), the limit is the lesser of:
- 25% of your disposable earnings (take-home after taxes and required deductions), OR
- The amount your weekly earnings exceed 30× the federal minimum wage (currently $217.50/week is fully protected)
Disposable earnings means after mandatory deductions — taxes, Social Security, Medicare. Not after your health insurance premium or 401(k) contribution.
Child support and alimony garnishments follow different rules — up to 50–60% of disposable earnings can be taken. Student loan garnishment (federal loans) can reach 15%. The 25% cap applies to consumer debts from private creditors.
Some states set lower limits than the federal cap. Whatever protects you more — state or federal — applies.
Social Security Garnishment: The Rule Most People Get Wrong
The single biggest misconception I see — and collectors absolutely exploit it — is the idea that Social Security can be seized for credit card debt or private loans. It cannot.
According to the Social Security Administration and the CFPB: Social Security benefits are generally exempt from garnishment, levy, or seizure by private creditors. Credit card companies, debt buyers, medical providers — none of them can touch it.
There are narrow exceptions where Social Security can be reduced or offset:
- Federal student loan debt (Department of Education)
- Federal tax debt (IRS)
- Child support or alimony obligations
- Other federal debts
The direct deposit protection: If you use direct deposit for Social Security, your bank is legally required to protect two months’ worth of benefits from garnishment — automatically. If you still receive paper checks and deposit them manually, that protection is weaker. Switch to direct deposit if you haven’t.
States That Prohibit Wage Garnishment Entirely for Private Debt
Four states give you near-complete protection from wage garnishment by private creditors:
Fully Protected States
- Texas — private creditors cannot garnish wages
- Pennsylvania — same protection
- North Carolina — same protection
- South Carolina — same protection
Exceptions still apply for child support, taxes, and student loans in these states.
What Creditors Can Do Instead
- Seize money from bank accounts
- Place liens on property
- Report the judgment to credit bureaus
- Wait for a property sale to collect
- Continue collecting interest on the judgment
Living in a protected state doesn’t make the debt go away — it limits the collection tools.
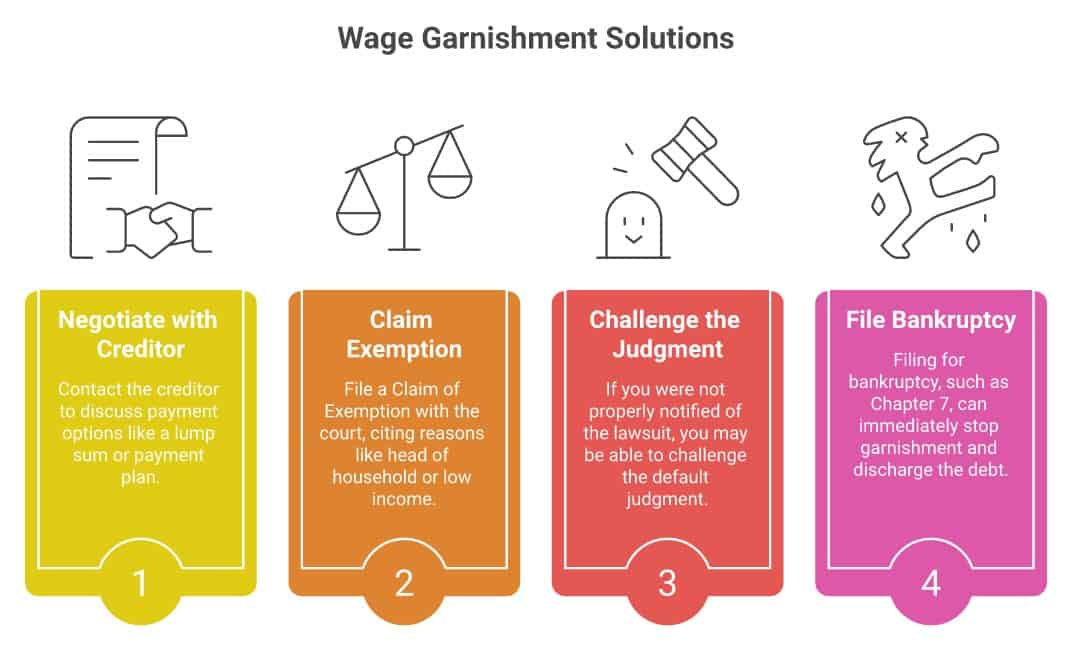
How to Stop a Wage Garnishment: All Four Options
Here’s the honest picture. You have four real paths. Each has trade-offs.
Option 1: Negotiate Directly With the Creditor
Once a creditor has a garnishment running, they’re already collecting. But they will often negotiate — especially if you can offer a lump sum or structured payment. A creditor getting 25% of your check for two years is less appealing to them than getting 60% of the balance right now.
Call them. Tell them you want to discuss resolving the judgment. You’d be surprised how many times a garnishment stops the moment you pick up the phone with a serious offer. Get any agreement in writing before you pay anything, and make sure it includes language releasing the garnishment.
Option 2: Claim a Legal Exemption
Depending on your state, you may qualify for exemptions that reduce or eliminate what can be taken:
- Head of household exemption: If you provide more than 50% of financial support for a child or dependent, many states protect all or most of your wages. Florida fully exempts head-of-household disposable earnings under $750/week.
- Low-income exemption: If your income is near or below poverty level, some states prohibit garnishment entirely.
- State-specific exemptions: Many states protect a higher percentage than the federal 25% cap.
To claim an exemption, you typically file a Claim of Exemption form with the court that issued the garnishment order. The creditor can challenge it, but many don’t. Check with a local consumer law attorney — this is often a one-hour consultation that pays for itself immediately.
Option 3: Challenge the Underlying Judgment
If you were never properly served with the lawsuit (called a “default judgment”), you may be able to vacate the judgment and force the creditor to start over. This doesn’t help everyone, but if you genuinely never received notice of the lawsuit, you have grounds to fight it.
This requires an attorney. Don’t try to navigate a motion to vacate a judgment alone.
Option 4: File Bankruptcy — The Immediate Stop
This is the option nobody wants to mention, but it’s the most powerful tool available. When you file bankruptcy, an automatic stay goes into effect the moment your petition is filed — before any judge reviews it, before any hearing is scheduled. Per the U.S. Courts, the automatic stay immediately halts wage garnishments, lawsuits, and collection calls.
If you file on a Monday, your garnishment stops Monday. You notify your employer and the garnishing creditor, and they must comply immediately.
Bankruptcy isn’t the nuclear option. It’s the legal tool Congress created for exactly this situation — when debt has broken the math of your life and you need a reset.— Steve Rhode, GetOutOfDebt.org
I filed bankruptcy myself in 1990. I went on to rebuild completely. The Federal Reserve has studied this — people who file bankruptcy do measurably better financially than insolvent people who don’t file. The shame around it is manufactured by an industry that profits from keeping you in debt.
Chapter 7 typically takes about 90 days. Most unsecured debts — credit cards, medical bills, personal loans — are discharged entirely. The garnishment doesn’t just stop; the underlying debt goes away.
Not sure which option fits your situation? My free Find Your Path tool walks through your specific numbers and points you toward the options that actually make sense for you — in about two minutes.
How to Check Your Wage Garnishment Balance
A common question I get: how do you know how much is left on a garnishment? There’s no single national database — you have to go to the source.
- Check your pay stubs: Each stub should show the garnishment amount deducted that period
- Contact the court: The court that issued the writ can tell you the original judgment amount and interest accruing
- Contact the creditor or their attorney: Ask for a payoff statement — the remaining balance plus any interest and fees
- Ask your employer’s payroll department: They have the garnishment order and may know the total amount
Keep in mind that judgments typically accrue interest — often at a statutory rate set by state law. What started as a $5,000 judgment may now be $7,000 by the time you check. Get a current payoff figure in writing before assuming you know the balance.
Part of the Chapter 7 Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
Key Takeaways
- Federal law caps garnishment at 25% of disposable earnings for most consumer debts
- Social Security cannot be garnished by private creditors — credit cards, debt collectors, medical providers cannot touch it
- Texas, Pennsylvania, North Carolina, and South Carolina prohibit wage garnishment for private debt entirely
- Negotiating directly with the creditor often stops a garnishment faster than people expect
- Bankruptcy triggers an automatic stay the same day you file — garnishment stops immediately
- Head of household and low-income exemptions may protect your wages in many states
- Judgments accrue interest — check your current payoff balance, not the original debt amount
Frequently Asked Questions
How can I stop a wage garnishment immediately?
The fastest legal option is filing bankruptcy, which triggers an automatic stay the same day your petition is filed — stopping the garnishment before any court hearing occurs. You then notify your employer and the creditor in writing. Alternatively, if you live in Texas, Pennsylvania, North Carolina, or South Carolina, private creditors cannot garnish wages at all, and you can challenge the garnishment through the court. Negotiating a settlement directly with the creditor can also stop the garnishment if they agree to release the writ.
Can bankruptcy stop wage garnishment?
Yes — bankruptcy is the most immediate and complete way to stop a wage garnishment. Filing a Chapter 7 or Chapter 13 petition creates an automatic stay under federal bankruptcy law, which halts all garnishments, lawsuits, and collection actions the moment you file. The garnishment stops the same day. In Chapter 7, the underlying debt is typically discharged entirely within 90 days, meaning it is gone permanently.
Can social security be garnished for credit card debt?
No. Social Security benefits are protected from garnishment by private creditors including credit card companies, debt collectors, and medical providers. Federal law exempts Social Security from private debt collection. The only entities that can offset or reduce Social Security are the federal government itself — for unpaid federal taxes, federal student loans, or child support obligations. Private creditors cannot touch Social Security benefits.
What is wage garnishment?
Wage garnishment is a court-ordered process where a creditor who has won a judgment against you directs your employer to withhold a portion of your paycheck and send it to the creditor before you receive it. It requires a court judgment first — a creditor cannot garnish your wages simply because you owe them money. They must sue you, win, and then obtain a separate court order for the garnishment. Federal law limits the amount to 25% of disposable earnings for most consumer debts.
How does wage garnishment work?
A creditor first sues you and obtains a court judgment. They then file a writ of garnishment with the court, which is served on your employer. Your employer is legally required to withhold the specified amount from each paycheck and send it to the creditor or court. Your employer cannot fire you because of a single garnishment — federal law prohibits that retaliation. The garnishment continues until the debt is paid in full, you negotiate a settlement, a court grants an exemption, or you file bankruptcy.
How to check wage garnishment balance?
Contact the creditor or their attorney and request a current payoff statement showing the remaining principal plus accrued interest. You can also check the court record where the judgment was entered — the original judgment amount is public record. Your pay stubs show each deduction, which you can add up to calculate how much has been paid so far. Remember that most judgments accrue interest at a state-set rate, so the balance may be higher than the original judgment.
What is social security garnishment?
Social security garnishment refers to when a portion of your Social Security benefits is withheld to repay a debt. Private creditors — including credit card companies, medical providers, and debt collectors — cannot garnish Social Security. Federal agencies can, for specific debts: unpaid federal income taxes (IRS), defaulted federal student loans, and overdue child support or alimony. If you receive Social Security by direct deposit, your bank is legally required to protect two months of benefits from any garnishment order.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



