

Quick Answer: Closing a credit card account almost always hurts your credit score — sometimes by a lot. It raises your credit utilization ratio by shrinking your available credit limit, and it can lower your average account age over time. A card with a high interest rate costs you nothing if you pay the balance in full every month and simply stop using it. Before you close that account, run the math.
Part of the Credit Cards Hub: This post is one piece of my complete Credit Cards: The Complete Guide — how credit cards actually work, what they cost, how they affect your score, and every option when the debt gets out of hand.
I get the impulse. You want to close the account because it carries a painful memory, a high rate, or it feels like something you should eliminate when you’re trying to clean up your finances.
But that impulse is emotional, not mathematical. And credit scores are built on math.
Closing a credit card account can trigger a drop in your score in ways most people don’t anticipate — and for years after the closure. Before you cut up that card or call to cancel, I want you to understand exactly what happens to your score when you do, and why keeping that account open might cost you absolutely nothing.
How Your FICO Score Works — And Which Parts Closing a Card Hits
Your FICO credit score — the one most lenders use — is built from five factors, each carrying a different weight. According to myfico.com:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
When you close a credit card account, you don’t touch payment history. But you potentially damage three of the other four factors: amounts owed (utilization), length of credit history, and credit mix. That’s 55% of your score in the crosshairs from a single account closure.
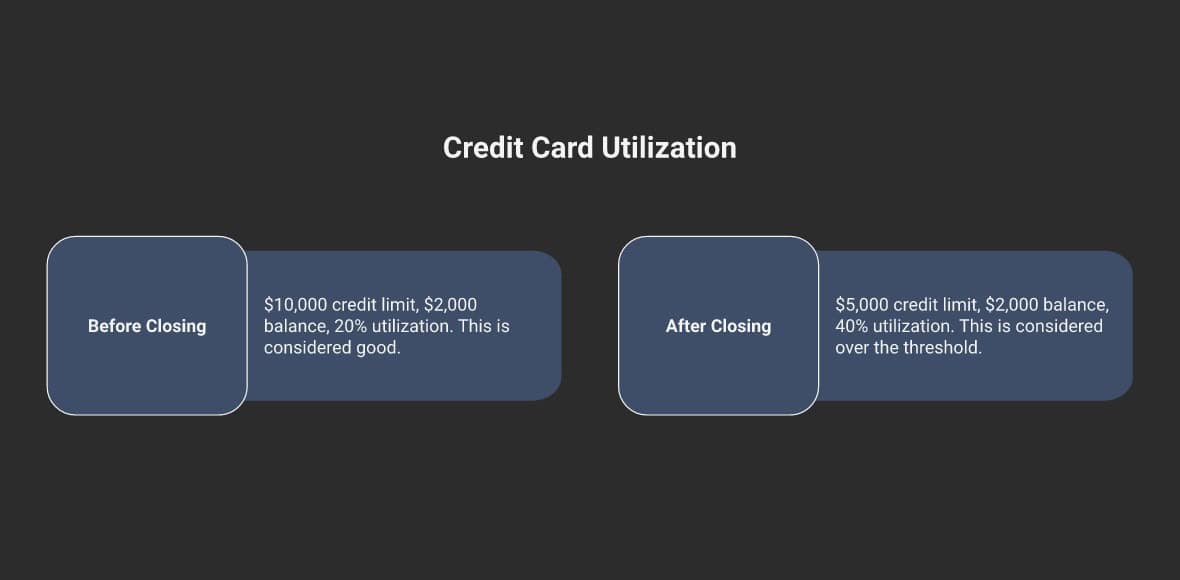
The Utilization Bomb (This One Hits Immediately)
Credit utilization is the ratio of your total credit card balances to your total available credit limit. The Consumer Financial Protection Bureau advises keeping this below 30%. Most credit experts consider below 10% ideal for top scores.
Here’s where closing an account becomes a math problem you can’t escape:
The Utilization Math:
You have two cards. Card A: $5,000 limit. Card B: $5,000 limit. Total available credit: $10,000.
You carry $2,000 on Card A. Credit utilization: 20%. Solid.
Now you close Card B (no balance, high rate, “don’t need it”).
Total available credit drops to $5,000. You still owe $2,000.
Credit utilization is now: 40%. Above the recommended threshold.
You did not borrow a single dollar more. You did not miss a single payment. You closed one account — and your utilization doubled.
This is why the CFPB specifically warns: avoid closing cards with low balances, as this reduces your total available credit and raises utilization ratios. This isn’t opinion — it’s the direct mechanism that causes score drops after account closures.
The Credit History Hit (This One Hits Later — and Lingers)
The second damage comes from the length of your credit history, which accounts for 15% of your FICO score. Lenders want to see a long, stable track record of responsible account management — not a short one.
Here’s the part that surprises people: when you close a positive account, it doesn’t disappear from your credit report immediately. It typically remains visible for up to 10 years after closing. During those 10 years, it continues to contribute to your average account age calculation.
But the day that old account finally ages off your report? Your average account age can drop significantly — especially if it was your oldest account or one of a few older accounts. And at that point, you could be dealing with a score impact years after you made the decision to close it.
The Oldest Card Problem: If the card you want to close is your oldest account, the damage is amplified. Your oldest account anchors your entire credit history length. Closing it doesn’t just affect utilization — it permanently caps how long your credit history can eventually grow.
The High-Interest Rate Myth You Need to Let Go Of
The most common reason I hear for wanting to close a credit card is the interest rate. “It’s 29% APR — I don’t want that thing.”
I understand the feeling. But the math doesn’t work the way people think it does.
A 29% APR card charges you 29% annually on balances you carry from month to month. It charges you zero percent on balances you pay in full before the due date. Zero. The interest rate is irrelevant if there is no balance to charge it against.
A high-rate card sitting in a drawer with a zero balance costs you exactly nothing in interest. It does, however, cost you plenty if you close it and watch your credit score drop.— Steve Rhode
The CFPB confirms: “You need not carry balances to maintain good credit. Paying off cards completely monthly both improves scores and minimizes interest costs.” The credit score benefit comes from having the available credit limit — not from using it or paying interest on it.
So the move, if you’re worried about a high-rate card, isn’t to close it. It’s to stop using it for purchases you can’t pay off immediately, toss it in a drawer, and set up one small automatic monthly charge (a streaming subscription, a utility bill) with autopay. That keeps the account active and in good standing. The interest rate never enters the picture.
What Closing a Card Actually Costs You — Beyond the Score
A lower credit score doesn’t just affect your ego. It affects your wallet. Interest rates on mortgages, auto loans, and personal loans are all tied to your credit score. According to FICO, the difference between a 700 and a 760 score on a 30-year mortgage can mean tens of thousands of dollars in additional interest over the life of the loan.
You closed a card that cost you $0 in interest. The resulting score drop could cost you real money every year on real debt.
When Closing a Card IS the Right Call
I’m not saying never close a credit card. Sometimes it’s the right move. But it’s a trade-off, not a freebie. Here are the scenarios where closing makes legitimate sense — along with the acknowledgment that there’s a score cost to accept:
When Closing May Be Worth It
- Annual fee you can’t justify — if the fee exceeds any rewards or benefits, cancel
- Preventing fraud on a forgotten card — an account you don’t monitor is a security risk
- You’re in active debt payoff — removing temptation to charge more, accepting the score trade-off knowingly
- Authorized user situation — removing yourself from someone else’s account you don’t control
When Closing Hurts More Than It Helps
- High interest rate on a card you don’t carry a balance on — zero cost to keep open
- Old account you “never use” — age is an asset, not a liability
- Emotional reaction to a debt you’ve now paid off — keep the account, lose the balance
- You’re about to apply for a mortgage or car loan — wait until after approval
What to Do Instead of Closing
If you genuinely don’t want to use a card but want to protect your score, here’s the alternative strategy that costs nothing:
- Put it in the freezer — literally. Put the card in a bag of water and freeze it. You won’t use it impulsively, but the account stays open.
- Set one small recurring charge. A $5–$15 monthly service on autopay keeps the account active and shows usage — some card issuers close inactive accounts after 12–24 months, which causes the same score hit without you choosing it.
- Call and negotiate the annual fee away. Many card issuers will waive or reduce annual fees for long-term customers who call and ask. You’d be surprised how often this works.
- Downgrade, don’t close. If your card has an annual fee and the issuer has a no-fee version, ask to product-change (downgrade) to the lower card. You keep the account age, keep the credit limit, lose the fee.
Key Takeaways
- Closing a credit card raises your utilization ratio immediately — sometimes enough to push you past the 30% threshold that hurts your score
- A high-rate card charges zero interest if you carry a zero balance — the rate is irrelevant if you pay in full
- Old accounts are assets, not liabilities — closing your oldest card removes your longest credit history anchor
- Closed positive accounts age off your report in ~10 years, creating a delayed score hit years after the decision
- Instead of closing: freeze it, add one autopay charge, downgrade to a no-fee version, or just stop using it
If you’re trying to figure out the best approach to managing your credit as part of a broader debt strategy, take the Find Your Path quiz — it helps you understand which options actually fit your situation rather than following generic advice.
Frequently Asked Questions
Does closing a credit card hurt your credit score?
Yes, in most cases closing a credit card account hurts your credit score. The primary damage comes from your credit utilization ratio: when you close an account, you lose that card’s credit limit from your total available credit, which means your existing balances represent a larger percentage of available credit. If you carry any balances on other cards, your utilization ratio rises immediately — sometimes dramatically. The Consumer Financial Protection Bureau specifically advises against closing cards with low balances for this reason.
How much can closing a credit card drop your credit score?
The exact impact varies by person and credit profile, but the damage is proportional to how much available credit you lose and how old the account being closed is. According to FICO, amounts owed (which includes credit utilization) makes up 30% of your score, and length of credit history makes up 15%. Closing one account can affect both. Someone with limited credit history or high existing balances will typically see a larger drop than someone with many open accounts and low utilization.
Should I close a credit card with a high interest rate?
Generally no — if you’re not carrying a balance on it. A high interest rate only costs you money when you carry a balance from month to month. A card sitting in a drawer with a zero balance costs you nothing in interest regardless of its rate. If you close it, you lose the credit limit (raising your utilization ratio) and the account’s age contribution to your credit history, for zero financial benefit. The better approach: stop using it for purchases you can’t pay off immediately, set a small recurring autopay charge to keep the account active, and put the card away.
How long does a closed credit card account stay on your credit report?
A closed credit card account in good standing typically stays on your credit report for up to 10 years from the date of closure. During this time it continues to contribute positively to your credit history. However, once it falls off after 10 years, your average account age can drop significantly — especially if it was one of your older accounts. This delayed impact is one reason why the score consequences of closing an account aren’t always felt immediately.
Is it better to close a credit card or leave it open with a zero balance?
Leaving it open with a zero balance is almost always better for your credit score. An open account with a zero balance contributes positively to your available credit (lowering your utilization ratio), maintains your credit history length, and costs you nothing if you’re not using it and there’s no annual fee. The only scenario where closing makes clear financial sense over keeping is when an annual fee isn’t justified by any benefits — and even then, try downgrading to a no-fee version of the same card first to preserve the account age and credit limit.
Sources: myFICO — What’s in Your Credit Score; Consumer Financial Protection Bureau — How Do I Get and Keep a Good Credit Score
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



