

Quick Answer: Symple Lending is a for-profit personal loan lender. To evaluate whether they’re right for you, I’d encourage you to check their complaint history with the CFPB, read their reviews on Trustpilot, and check their enforcement history. Here’s how to do each of those.
Before You Read This: I want to be upfront about what this page is and isn’t. I’m not a financial advisor, and I’m not rendering a verdict on Symple Lending. This is a research guide — I’m showing you where to look so you can reach your own conclusions based on current information.
If you find something in the public record that concerns you, post it in the comments below. If you’re evaluating their contract, use my free Contract Decoder tool.
If you represent Symple Lending and something here is inaccurate, contact me and I’ll review it promptly.
If you have inside information you feel you need to share with me privately: don’t. Whatever you want to share should be posted in the comments — by you, with your name attached. I’m not willing to be anyone’s conduit for information they won’t stand behind themselves.
The most valuable thing on this page may not be what I’ve written — it’s the comments section below. People who’ve actually worked with Symple Lending share their experiences there. I’d encourage you to read them and add your own.
Who Is Symple Lending?
An educated consumer is our best customer.— Sy Syms
New here? My Ultimate Consumer Guide to Checking Out a Debt Relief Company walks through how to vet any debt relief company before you sign anything.
Symple Lending is a for-profit personal loan lender company. Rather than repeat what they say about themselves here, I’d encourage you to read their own website and state business filings — that way you’re seeing it directly from primary sources, not filtered through me.
Step 1: Check Their Credentials
Before anything else, verify they have the credentials they claim. Here’s what to check:
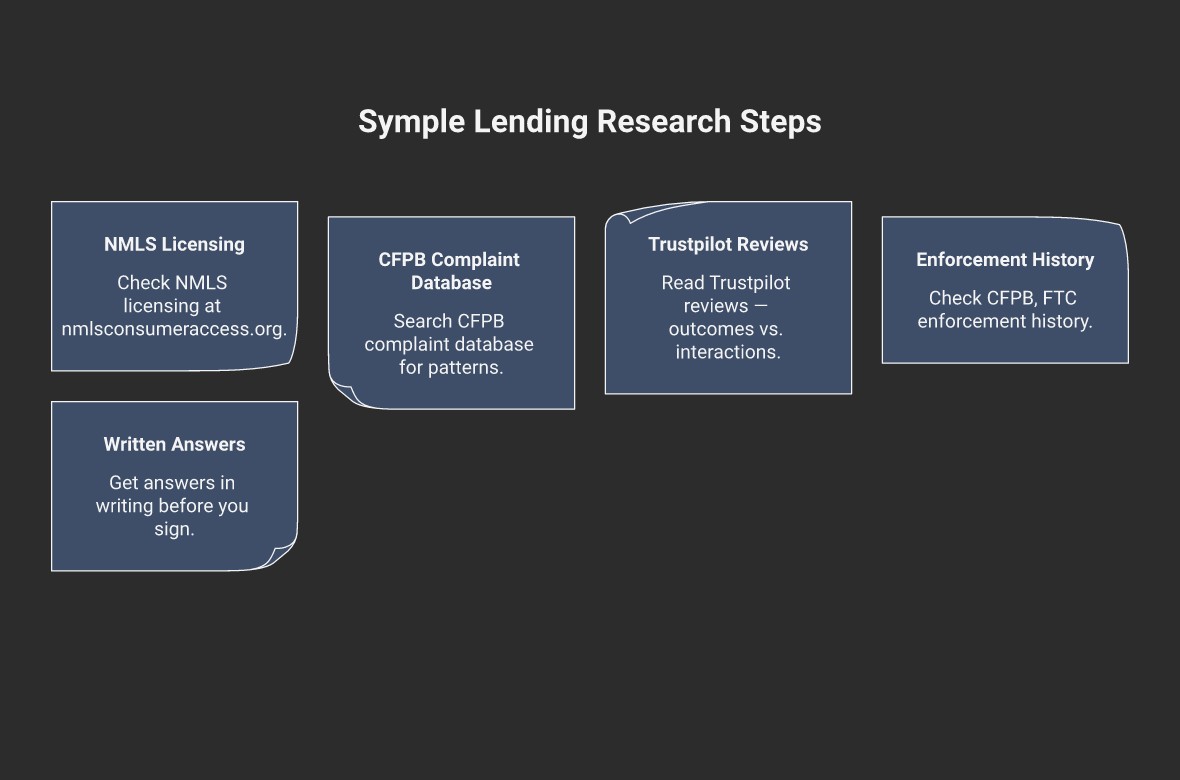
- NMLS Licensing: Personal loan lenders must be licensed in each state they operate in. Check Symple Lending’s NMLS profile (ID #2508833) at NMLS Consumer Access — verify active licenses in your state.
- BBB Profile: Check their Better Business Bureau profile — look at the rating, years in business, and especially the complaint history and how they responded.
- State Lending License: Search your state’s financial regulator website for Symple Lending’s licensing status — requirements vary by state.
A Note on BBB Grades: A high BBB grade doesn’t necessarily mean a company is right for you — it means they respond to complaints filed through the BBB. Read the actual complaint text and the company’s responses. That’s the useful part. See my full guide to what BBB letter grades actually mean →
Step 2: Check Consumer Complaints
The Consumer Financial Protection Bureau maintains a public database of complaints filed against financial companies. You can search for Symple Lending directly:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Search Symple Lending’s complaint history in the CFPB database →
When you’re reading complaints, look for:
- What the complaints are about — fees, loan terms, communication problems?
- How the company responded — did they resolve issues or just close them?
- Whether the same issue appears repeatedly — a pattern matters more than a single complaint
- The ratio of complaints to customers — a larger company will have more complaints in raw numbers
Step 3: Read Their Trustpilot Reviews
You can find Symple Lending’s Trustpilot reviews here. A few things to keep in mind as you read:
How to read Trustpilot like a pro: My complete guide to spotting red flags in Trustpilot reviews breaks down exactly what to look for — including how to identify review solicitation campaigns and reputation management tactics.
- Pay attention to what the 5-star reviews are actually about. If they’re praising a friendly phone call or easy application — that’s interaction quality, not loan performance. Compare those against reviews that specifically mention outcomes: rate received, final loan terms, any surprises at closing.
- Read the 2- and 3-star reviews carefully — these tend to be the most honest, from people who had mixed experiences and aren’t trying to tear the company apart
- Look at how the company responds to negative reviews — a defensive or dismissive response tells you something
- Check the review dates — a flood of 5-star reviews in a short period can indicate a solicitation campaign
Step 4: Check Their Legal and Enforcement History
For-profit personal loan lenders are subject to enforcement actions from federal and state regulators. Here’s where to look:
- CFPB Enforcement Actions: Search the CFPB’s enforcement action database for the company name
- FTC Actions: The FTC publishes all enforcement cases — search for the company or its principals
- State Attorney General: Search “Symple Lending attorney general” or “Symple Lending settlement” — many enforcement actions happen at the state level
- Federal Court Records: CourtListener searches 1.3 billion federal court documents for free — no registration required. For the official PACER system with complete case filings, see my guide to using PACER.gov.
Context Matters: A company that has faced enforcement action isn’t automatically disqualified — what matters is what the action was for, whether they resolved it, and whether the behavior continued. A company that’s never faced any scrutiny in a highly regulated industry may just not have been looked at yet.
Step 5: Ask the Right Questions Before You Proceed
Before signing anything: Run their contract through my free Contract Decoder tool. Paste it in and get a plain-English breakdown of what you’re agreeing to.
Before you commit to any personal loan, get clear answers — in writing — to these questions:
- What is the APR — the actual annual percentage rate including all fees — not just the interest rate?
- Are there origination fees, prepayment penalties, or other charges not included in the advertised rate?
- What are the exact repayment terms — monthly payment, total interest paid over the life of the loan?
- What happens if I miss a payment — grace period, late fees, impact on my credit?
- Is the rate fixed or variable — and if variable, what is the cap?
- What is the approval process, and will applying result in a hard credit pull?
Before You Commit: A personal loan used for debt consolidation isn’t right for everyone. Run your situation through my Find Your Path tool to see whether a personal loan, debt management plan, bankruptcy, or another option fits your situation better.
Key Takeaways
- Verify NMLS licensing and BBB profile before anything else
- Read CFPB complaints for patterns — not just raw numbers
- On Trustpilot, compare 5-star reviews about interactions vs. reviews about actual loan outcomes
- Check CFPB and FTC enforcement history
- Get the APR, all fees, and repayment terms in writing before you sign
- The comments section below contains real experiences from real customers — read them
Want the full research playbook? My Ultimate Consumer Guide to Checking Out a Debt Relief Company covers every tool and source in this guide — plus detailed walkthroughs for reading BBB profiles, spotting Trustpilot red flags, and searching federal court records on CourtListener.
Frequently Asked Questions
Is Symple Lending a legitimate company?
Symple Lending is a registered for-profit personal loan company. Whether they’re the right fit depends on your situation. Check their CFPB complaint history, BBB profile, and Trustpilot reviews before deciding.
How do I file a complaint against Symple Lending?
You can file a complaint directly with the CFPB at consumerfinance.gov/complaint. You can also file with your state attorney general’s office and the BBB. Filing with the CFPB creates a public record and triggers a required company response.
Is Symple Lending licensed in my state?
Check Symple Lending’s NMLS profile for a current list of state licenses. Requirements and licensing status vary by state.
What is a personal loan and how does it work?
A personal loan is an unsecured loan repaid in fixed monthly installments over a set term. Lenders evaluate creditworthiness to determine your rate and loan amount. The funds are typically deposited directly to your bank account and can be used for debt consolidation, home improvements, or other expenses.
Should I work with Symple Lending?
That depends on your situation. Run it through my Find Your Path tool before committing to any loan or debt solution.
Share Your Experience with Symple Lending
If you’ve worked with Symple Lending — as a customer, former employee, or someone who looked into them and decided not to apply — I’d encourage you to share your experience in the comments. Your perspective helps others make a more informed decision.
To share your experience: Scroll to the bottom of this page — the comments box is there.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.
Browse all Lenders reviews, or see the full Company Reviews directory.



