

Quick Answer: Wakefield & Associates is a for-profit debt collection agency specializing in medical debt, based in Aurora, Colorado.
Before You Read This: I’m not rendering a verdict on Wakefield & Associates. This is a research guide — I’m showing you where to look so you can reach your own conclusions.
Post concerns in the comments. Evaluating their contract? Use my free Contract Decoder tool.
If you represent Wakefield & Associates and something here is inaccurate, contact me promptly.
Inside information? Post it publicly in the comments with your name attached.
The most valuable thing here may be the comments below. Read them and add your own.
Who Is Wakefield & Associates?
An educated consumer is our best customer.— Sy Syms
New here? My Ultimate Consumer Guide to Checking Out a Debt Relief Company walks through vetting any company.
Wakefield & Associates is a for-profit debt collection agency that works primarily with healthcare providers to collect medical debt. Rather than repeat what they say about themselves, I’d encourage you to read their website directly at wakefieldinc.com.
Step 1: Check Their Credentials
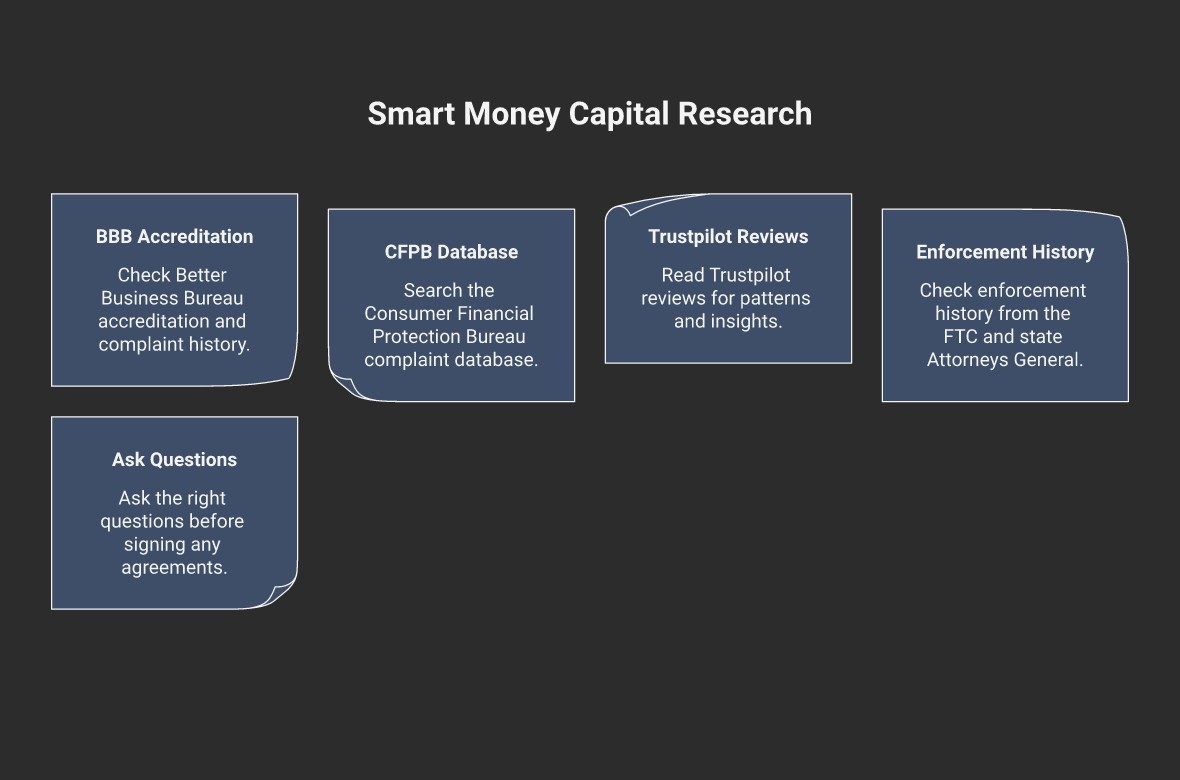
- BBB Profile: Better Business Bureau profile for Wakefield & Associates — rating, complaint history, and company responses.
- State Collection License: Debt collectors must be licensed in most states. Verify Wakefield & Associates is authorized to collect in your state before making any payment or agreement.
- FDCPA Compliance: Wakefield & Associates is bound by the Fair Debt Collection Practices Act. You have the right to request written validation of any debt they claim you owe before making any payment.
A Note on BBB Grades: A letter grade tells you little. Read the actual complaint text — specific patterns in complaints are far more useful than the overall grade.
Step 2: Check Consumer Complaints
Search Wakefield & Associates’ complaint history in the CFPB database →
- What types of complaints have been filed?
- How did the company respond to each one?
- Are there recurring patterns — wrong amounts, wrong consumers, medical billing disputes?
- Is complaint volume proportional to the size of the company?
Step 3: Read Their Trustpilot Reviews
Find Wakefield & Associates’ Trustpilot reviews here:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- What do consumers report about their collection tactics?
- Two- and three-star reviews tend to be the most honest — read those carefully
- How does the company respond to negative reviews?
- Look for patterns around medical debt disputes, incorrect balances, or billing errors
Step 4: Check Their Legal and Enforcement History
- CFPB: CFPB enforcement actions database
- FTC: FTC cases and proceedings — including FDCPA actions
- State AG: Search “Wakefield Associates attorney general” in your state
- PACER: Federal court records via PACER — search for class action lawsuits
Context Matters: An enforcement action doesn’t automatically mean the company is acting illegally today. What matters is what it was for and whether the behavior changed. FDCPA lawsuits are common in the medical debt collection space — look for patterns, not just individual cases.
Step 5: Ask the Right Questions Before You Respond
Before signing anything: Run any agreement through my Contract Decoder tool.
- Request debt validation in writing before making any payment — this is your legal right under the FDCPA
- Is the medical debt accurate — match it against your Explanation of Benefits (EOB) from your insurer
- Has your insurance carrier been correctly billed and paid their portion?
- Is the debt within the statute of limitations in your state?
- If settling, get the full settlement agreement in writing before sending any money
- Will they report the settled debt as “paid in full” or “settled for less than the full amount”?
Before You Respond: Run your situation through my Find Your Path tool to understand all your options before making any payment or agreement with a debt collector.
Key Takeaways
- Request written debt validation before making any payment — it’s your right
- CFPB: look for patterns in complaints, not just raw numbers
- Trustpilot: watch for patterns around medical billing errors and incorrect balances
- Check enforcement history — FDCPA violations are serious and worth knowing about
- Verify the medical debt against your EOB before paying anything
- Read the comments on this page — consumer experiences are often more revealing than any official record
Want the full research playbook? My Ultimate Consumer Guide to Checking Out a Debt Relief Company covers every tool and source in this guide — plus detailed walkthroughs for reading BBB profiles, spotting Trustpilot red flags, and searching federal court records on CourtListener.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Frequently Asked Questions
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
Is Wakefield & Associates a legitimate debt collector?
Wakefield & Associates is a registered debt collection agency operating primarily in the medical debt space. Whether any specific debt they are attempting to collect is valid is a separate question — always request written validation before making any payment.
How do I file a complaint against Wakefield & Associates?
File with the CFPB at consumerfinance.gov/complaint, the FTC at reportfraud.ftc.gov, your state attorney general’s office, and the Better Business Bureau.
Is Wakefield & Associates a nonprofit?
No. Wakefield & Associates is a for-profit debt collection agency.
What does Wakefield & Associates collect?
Wakefield & Associates specializes in medical debt collection, working directly with healthcare providers including hospitals, physician groups, and other medical facilities to recover outstanding patient balances.
Should I pay Wakefield & Associates?
Before paying any debt collector, run your situation through my Find Your Path tool. For medical debt specifically, verify the amount against your Explanation of Benefits, confirm your insurance was correctly billed, and check the statute of limitations in your state before making any payment.
Share Your Experience with Wakefield & Associates
Have you been contacted by Wakefield & Associates? Your experience — positive or negative — helps other consumers make informed decisions. Share it in the comments.
To share: Scroll to the bottom of this page — the comments box is there.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.
Browse all Debt Collectors & Debt Buyers reviews, or see the full Company Reviews directory.



