

Quick Answer: The D.C. Circuit’s full bench of 11 judges heard arguments on the CFPB shutdown on February 24, 2026 — and appeared deeply skeptical of the Trump administration’s position. Even the government’s own attorney acknowledged that the executive branch cannot fully eliminate the CFPB, because Congress mandated it exists. The case isn’t over, but the signals from the nation’s second-highest court suggest the CFPB is likely to survive in some form.
The battle over the Consumer Financial Protection Bureau has reached the nation’s second-highest court — and the Trump administration’s case appears to be in serious trouble.
On February 24, 2026, the full 11-judge bench of the U.S. Court of Appeals for the D.C. Circuit heard oral arguments in the fight over whether the administration can effectively shut down the CFPB by firing up to 1,400 of its employees. Based on the court’s pointed questions, legal experts and the coverage suggest the administration is unlikely to prevail. (Source: Missouri Lawyers Media)
Update on Prior Coverage: In February 2026, a district court blocked an earlier attempt to defund the CFPB. This hearing at the D.C. Circuit is the Trump administration’s appeal of that ruling — a higher-stakes battle before a higher court.
Each weekday I send one short email: one story that caught my attention, why it might matter to you, and one manageable thing you can do with it. A couple of minutes, and a dad joke.
In the latest issue (Oct 16): The check that looks like a scam may be real
Free. I sell nothing. Unsubscribe any time.
What Happened at the Hearing
The administration’s core argument: federal courts have no business blocking the executive branch from firing federal employees. Deputy Assistant Attorney General Eric McArthur told the court that the Merit Systems Protection Board — not the judiciary — is the proper place to challenge federal firings.
The judges weren’t buying it.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Judge Cornelia Pillard pressed McArthur directly: “If we were to affirm the district court’s finding that the government intended to shut down the agency, that changes the landscape doesn’t it?”
Most revealing: McArthur himself acknowledged that the administration “must observe the law” — and that it did not have the power to shut the CFPB down entirely, because Congress created and mandated it. That concession undercut the administration’s strongest argument. (Source: American Banker)
What the CFPB Actually Does for You
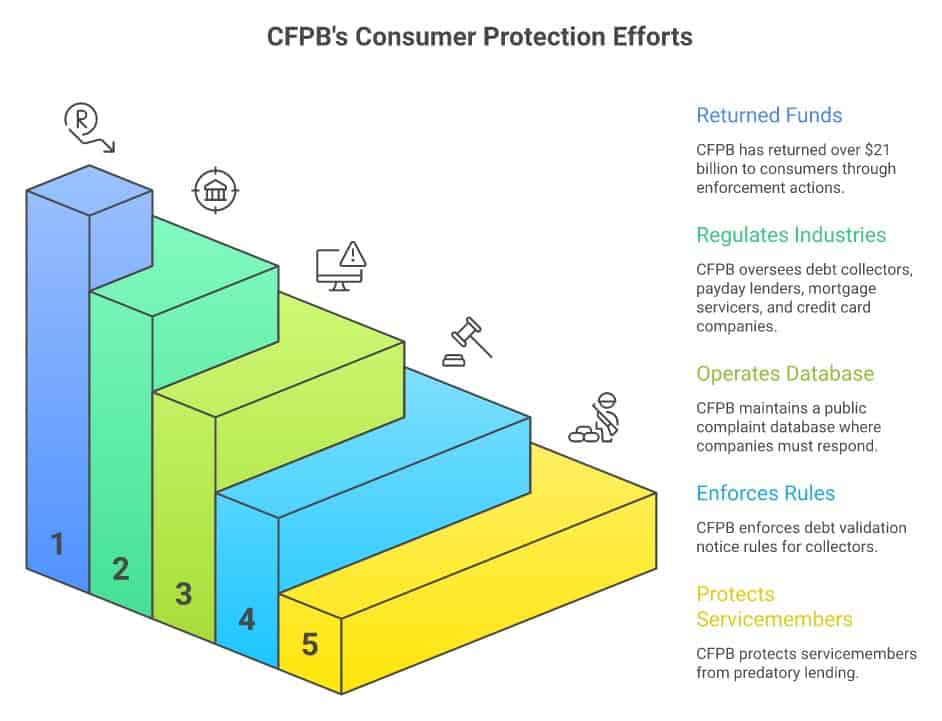
If you’ve ever wondered why you get a chance to dispute a debt collector’s claim, or why your mortgage lender has to give you a clear disclosure of your loan terms, the CFPB is a major reason why. Since its creation in 2011, it has:
- Returned over $21 billion to consumers through enforcement actions
- Supervised and regulated debt collectors, payday lenders, mortgage servicers, and credit card companies
- Created the public consumer complaint database — a tool I’ve used to research hundreds of debt relief companies
- Enforced rules requiring debt collectors to provide written validation notices
- Stopped predatory practices by companies that targeted servicemembers and their families
An agency that’s “largely on ice” means all of that is stalled. Enforcement actions don’t get filed. Investigations sit open. Companies that know the watchdog is distracted take more risks.
The CFPB is imperfect and political — but it’s one of the few places where consumers can fight back against companies with far more legal firepower than they have.— Steve Rhode
What Comes Next
The D.C. Circuit has not yet issued a ruling — oral arguments are just the beginning of the decision process. But the composition of the court and the tenor of the hearing give consumer advocates reason for cautious optimism. Legal experts expect the union representing CFPB employees to prevail at the D.C. Circuit, with any final showdown likely reaching the Supreme Court in its 2027-2028 term. (Source: Bloomberg Law)
For consumers dealing with debt right now, the practical reality is that CFPB enforcement remains limited. That doesn’t mean you’re without options:
- State attorneys general have stepped up enforcement where the CFPB has pulled back — especially in large states like California, New York, and Illinois
- The CFPB complaint database is still operating — you can still file complaints at ConsumerFinance.gov
- The FTC retains authority over debt collectors and credit practices
- Private lawsuits under the FDCPA and other consumer protection laws remain an option regardless of the CFPB’s status
- Use the Find Your Path quiz to understand your full set of options in your current debt situation
Don’t Count on the CFPB Right Now: Even if the court ultimately rules in the CFPB’s favor, enforcement capacity remains limited while the litigation continues. If you’re being harassed by a debt collector or dealing with a predatory lender, don’t wait for the federal watchdog — pursue your state AG, the FTC, or a private attorney now.
Key Takeaways
- The D.C. Circuit’s full 11-judge bench heard CFPB shutdown arguments Feb 24, 2026 — and appeared skeptical of the administration
- Even the government conceded it cannot fully eliminate the CFPB — Congress mandated it exists
- No ruling yet — decision expected in the coming months, with Supreme Court as a possible next step
- CFPB has been largely inactive since February 2025 — enforcement is limited regardless of outcome
- State AGs, FTC, and private lawsuits remain available consumer tools while the battle continues
Your Rights When Sued for Debt. With the CFPB’s future uncertain, knowing your rights matters more than ever. The free Sued for Debt Guide explains your FDCPA protections and what to do if a collector files a lawsuit.
Force Collectors to Prove the Debt. Under the FDCPA — regardless of CFPB enforcement — you have the right to demand proof. The free Debt Validation Letter Generator builds a personalized letter in seconds, no email required.
Frequently Asked Questions About the CFPB Shutdown Fight
What is the CFPB and why does the Trump administration want to shut it down?
The Consumer Financial Protection Bureau is an independent federal agency created in 2011 to regulate financial products and protect consumers from predatory practices by lenders, debt collectors, and credit card companies. The Trump administration has sought to sharply reduce its operations — firing up to 1,400 of its approximately 1,700 employees — arguing that its structure is unconstitutional and its scope too broad. Consumer advocates argue eliminating it would remove a key protection for millions of Americans dealing with debt and financial products.
What did the D.C. Circuit hear on February 24, 2026?
The full bench of 11 judges heard the administration’s appeal of a lower court ruling that blocked the mass firings. The administration argued courts cannot intervene in executive branch employment decisions. Judges pushed back sharply, and the administration’s own attorney conceded the executive cannot fully eliminate the CFPB because Congress created and mandated it. No ruling has been issued yet.
Does this mean the CFPB is safe?
Not yet — a skeptical hearing doesn’t guarantee a favorable ruling. The D.C. Circuit has not issued its decision. If it rules against the administration, the case may go to the Supreme Court. Legal experts expect the CFPB to survive in some form, but the agency’s capacity remains limited while litigation continues.
Can I still file a complaint with the CFPB?
Yes. The CFPB’s consumer complaint database is still operational at ConsumerFinance.gov/complaint/. Filing a complaint creates an official record and companies are required to respond. However, enforcement actions based on those complaints are proceeding more slowly while the agency’s staffing battle continues.
What can I do if I need consumer protection help right now?
Contact your state attorney general’s consumer protection office — state AGs have significantly ramped up enforcement to fill the gap left by a limited CFPB. The FTC also has jurisdiction over debt collectors and many financial products. For specific debt questions, use the Find Your Path quiz to identify which options make sense for your situation.
Sources: Missouri Lawyers Media | American Banker | Bloomberg Law (February 24–25, 2026)
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



