

Quick Answer: A new poll from Groundwork Collaborative finds that 63% of voters prefer a 10% credit card interest rate cap — even if it means losing their rewards programs. Nearly half of cardholders don’t pay their balance in full each month, meaning for most people, rewards points are a distraction from an interest bill that’s costing them far more.
Credit card rewards are designed for the 51% of cardholders who pay in full every month. If you carry a balance, you’re not earning rewards — you’re subsidizing them for someone else.— Steve Rhode
A new poll just put a number on what I’ve been saying for years: most Americans know the game is rigged on credit card interest rates, and they want it changed.
According to a survey conducted by Groundwork Collaborative and Protect Borrowers in partnership with Data for Progress, 63% of voters prefer a 10% credit card interest rate cap — even if that cap would result in rewards programs being reduced or credit card eligibility being tightened. (Source: Groundwork Collaborative)
That’s not a close call. And the support is bipartisan: Democrats (61%), Independents (64%), and Republicans (64%) all responded similarly. An 8-to-1 margin of voters support government action to cap credit card interest rates.
Why 63% Is Actually the Rational Majority
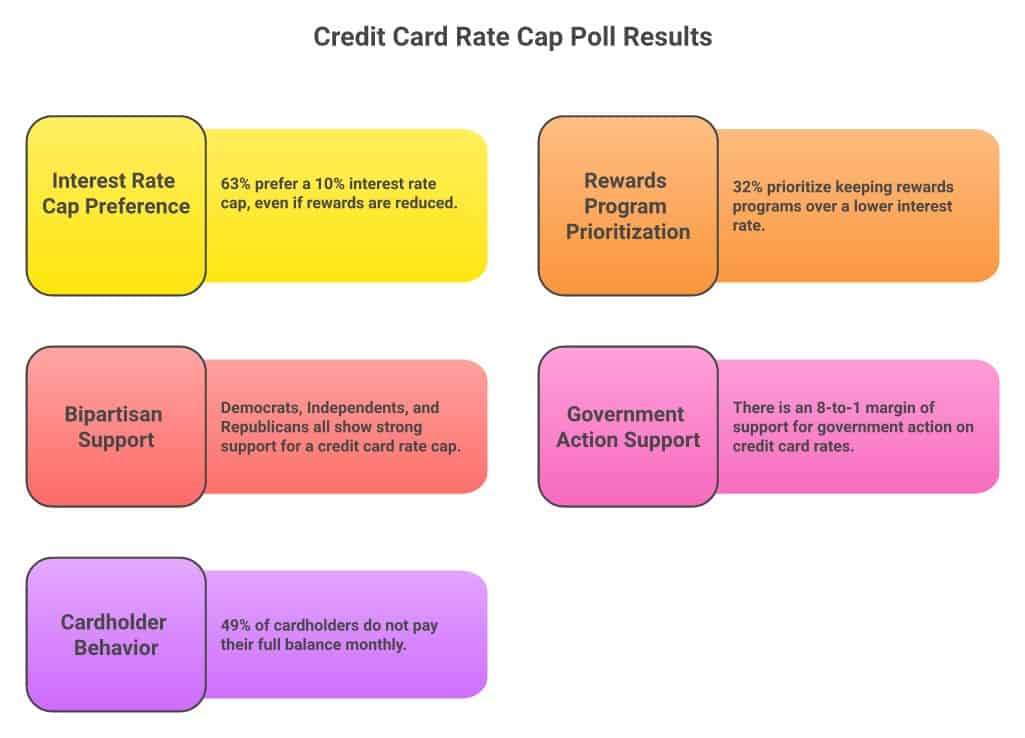
Here’s the math that explains why the majority got it right.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Nearly half of credit cardholders — 49% — don’t pay their full balance every month. They carry a balance. And if you carry a balance on a card charging 20–29% APR, your rewards program isn’t earning you anything. You’re paying more in interest than you’ll ever earn in points.
Think about that. You earn 2% cash back on your grocery spending. You pay 24% APR on the balance you carry. You’re netting negative 22 cents on every dollar that sits on that card. The rewards program is marketing, not math. (Source: Groundwork Collaborative poll)
The Myth: “I use my credit card for everything and earn great rewards.”
The Reality: Rewards programs are profitable for card issuers because they assume you’ll carry a balance. If you pay in full every month, rewards can genuinely benefit you. If you carry a balance — even occasionally — the interest you pay exceeds the rewards you earn, often by a large margin.
How Americans Are Actually Using Credit Cards
The poll data reveals something important about how credit cards have become embedded in everyday financial life — not as a luxury tool, but as a necessity:
- 76% use credit cards for groceries — not luxury spending, but food
- 75% use them for personal items like clothing and toiletries
- 52% use them for utilities — electric, gas, internet
- 34% of under-45 cardholders use credit cards to pay other debts
- 20% of under-45 cardholders use them for rent or housing costs
When you’re using a 24% APR credit card to pay your electric bill because your paycheck doesn’t stretch far enough, that’s not a rewards opportunity. That’s a crisis with a monthly fee attached.
Education Divide in Rewards: The poll found college graduates prioritize rewards in their card choices significantly more than non-college-educated cardholders (40% vs. 30%). Higher-income cardholders are more likely to pay in full and actually benefit from rewards. For everyone else, the reward math often doesn’t work in their favor.
The Rate Cap Debate: What Would Actually Happen
Supporters of a 10% interest rate cap — including Trump, who has floated the idea — argue it would force banks to offer credit more affordably.
Opponents, primarily in the banking industry, argue a rate cap would cause banks to restrict credit access — fewer people would qualify for cards, and rewards programs would be eliminated or gutted.
Both sides are partially right. But here’s the question nobody asks: if you’re carrying a balance at 24% APR, does losing a 2% cash-back rewards program actually hurt you? No. A 10% rate cap would save you 14 percentage points in annual interest. The math overwhelmingly favors the cap for the majority of cardholders who carry balances.
The 49% of cardholders who don’t pay in full every month would almost universally be better off with lower rates and no rewards than current rates with rewards. The 51% who pay in full would be the ones who lose.
Who Benefits From Rate Cap
- The 49% who carry balances
- Lower-income households using cards for essentials
- Under-45 borrowers using cards to cover rent and debt
- Anyone at 20%+ APR on current cards
Who Benefits From Current System
- The 51% who pay in full each month
- High-income “rewards maximizers”
- College-educated cardholders prioritizing perks
- Banks earning spread on revolving balances
What You Can Do Right Now (Without Waiting for Congress)
Whether or not a rate cap passes, you don’t have to wait for legislation to change your personal math. Here’s what’s available to you today:
- Balance transfer to 0% APR — If your credit qualifies, many cards offer 12-21 months with zero interest on transferred balances. That’s a DIY rate cap while you pay down the balance.
- Negotiate your rate — Most people don’t know this, but you can call your card issuer and ask for a rate reduction. If you have a solid payment history, they often say yes. It costs you a 5-minute phone call.
- Stop using high-rate cards for carrying balances — If you can’t pay in full, use a card with the lowest rate you have, not the best rewards. Rewards on a carried balance are mathematically negative.
- Consolidation loan at a lower rate — A personal loan at 10-12% to pay off cards at 22-24% is an immediate win on interest cost.
Not Sure Which Debt Strategy Fits Your Situation? The Find Your Path quiz helps you identify the right approach for your specific income, balance, and credit situation. It’s free and takes 2 minutes.
FAQ: Credit Card Interest Rates vs. Rewards
Are credit card rewards worth it if you carry a balance?
Almost never, mathematically. If you earn 2% cash back but pay 20% APR on a balance you carry, you’re losing approximately 18 cents on every dollar that sits on that card. The only exception: if you put a purchase on the card, pay it off immediately before any interest accrues, and earn a sign-up bonus in the process. The moment you carry a balance month to month, the math on rewards inverts completely.
What would a 10% credit card interest rate cap mean for my rewards points?
Banking industry analysts and credit card companies have warned that a rate cap would reduce or eliminate rewards programs, since interchange fees and revolving interest income fund reward payouts. If you currently pay off your balance in full each month and depend on those rewards, a rate cap could genuinely reduce the value of your card. If you carry a balance, you’d almost certainly come out ahead on the interest savings even without rewards.
Why are credit card interest rates still so high when the Fed has cut rates?
Credit card rates don’t follow Fed rate cuts as reliably as mortgage or auto loan rates. Card issuers set rates based on their risk assessment of revolving credit portfolios, not just the federal funds rate. The spread between the prime rate and average credit card APR has widened significantly over the past decade. Current average credit card APR is near record highs even after Fed rate cuts — which is exactly what the Groundwork Collaborative poll is responding to.
Can I actually negotiate a lower interest rate on my credit card?
Yes. Many people don’t realize this works. Call the number on the back of your card, ask to speak to a retention specialist, and say something like: “I’ve been a customer for X years with a good payment history, and I’ve received offers for lower-rate cards from other banks. Can you match a lower rate?” The worst they can say is no. If you have a long history and consistent payments, many issuers will reduce your rate by 3-5 percentage points without closing your account or affecting your credit score.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



