

Quick Answer: The “Clean Slate” credit repair method being promoted on social media — which promises to erase negative credit history through synthetic identities or mass false disputes — is a federal crime. It’s not new, not a secret, and not legal. People have gone to prison for it. Here’s what you need to know before you fall for it.
For the underlying rule the whole industry runs on, see why paying a credit repair company before it does the work is a federal violation.
Expert Context: I’ve been tracking illegal credit repair schemes since 1994, when I founded Debt Counselors of America (later renamed Myvesta) — one of the first comprehensive consumer debt assistance organizations in the United States, with 70 employees including staff psychologists, attorneys, and CPAs. I have personally documented dozens of federal prosecutions for synthetic identity fraud and Credit Profile Number (CPN) schemes over three decades — I broke down exactly why the CPN “fresh credit file” pitch is a federal crime. This is not theory. I watched this industry from the inside, and I watched operators get prosecuted. Every. Single. Time.
Every few years, a “new” illegal credit repair trick gets rebranded and marketed as a secret the credit bureaus don’t want you to know. Right now, it’s being called “Clean Slate.” The name changes. The crime doesn’t.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
The name changes every few years. The federal fraud charges don’t.— Steve Rhode
Warning: If someone is offering to create a “new credit file,” help you get a “Credit Profile Number” (CPN), or promising to legally erase accurate negative information from your credit report — walk away. These are federal crimes. The person selling it may end up in prison. So might you if you participate.
What the “Clean Slate” Scheme Actually Does
The scheme goes by several names — Clean Slate, credit washing, credit profile numbers (CPNs), new credit file. The mechanics typically involve one or more of these illegal tactics:
- Synthetic identity creation — Slightly altering your Social Security number or date of birth to generate a new credit file with no history
- Mass false disputes — Filing inaccurate dispute statements en masse to force credit bureaus to remove items automatically before they can verify them
- Falsifying personal identifiers — Misrepresenting your name, address, or other information to bypass verification systems
- Using another person’s information — Outright identity theft dressed up as “credit repair”
Key Terms Defined
Synthetic Identity: A fabricated identity created by combining real and false information — typically a real Social Security number (often a child’s or deceased person’s) with a different name and date of birth — to generate a new credit file. A federal crime under 18 U.S.C. § 1028 (Identity Fraud).
Credit Profile Number (CPN): A nine-digit number marketed by scammers as a legal substitute for your Social Security number on credit applications. There is no legal basis for CPNs. The Federal Trade Commission and Department of Justice have both prosecuted sellers and users of CPNs. Using one is federal fraud.
Credit Washing: The practice of mass-filing inaccurate dispute letters to force credit bureaus to delete negative items before they can be verified — exploiting a procedural requirement in the Fair Credit Reporting Act. Also referred to as “credit cleaning” or “credit sweeping.” A direct violation of the FCRA.
Promoters of these schemes post on social media claiming these approaches are “loopholes” or “legal methods the credit bureaus don’t want you to know.” That claim is false. The Fair Credit Reporting Act (FCRA) explicitly prohibits submitting false information to credit reporting agencies.
Why This Is a Federal Crime — Not a Gray Area
There is no legal interpretation under which creating a synthetic identity or filing false disputes is permissible. Federal law is clear:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Claim: “There’s a legal way to start fresh with a new credit profile that’s completely separate from your old one.”
The Reality: There is no legal “new credit profile.” Your Social Security number is permanently linked to your credit history. Creating a synthetic identity — even by altering one digit of your SSN — is federal fraud. The FTC has taken action against these operations, and the DOJ has prosecuted and sentenced individuals for exactly this type of synthetic identity fraud.
The federal statutes involved include:
- Fair Credit Reporting Act (FCRA) — Prohibits knowingly submitting false information to credit reporting agencies
- 18 U.S.C. § 1028 (Identity Fraud) — Creating a synthetic identity constitutes fraud
- 18 U.S.C. § 1343 (Wire Fraud) — Using electronic communication (social media, email) to promote the scheme
- 18 U.S.C. § 1344 (Bank Fraud) — Using the fraudulent credit file to obtain loans or credit
Before You Sign Anything: If a company is offering to repair your credit or help you start fresh, run their contract through the Contract Decoder first. It’s free — and it’s your last chance to spot red flags before you hand over money and risk federal criminal liability.
Why It Keeps Getting Sold as “New”
Here’s what I find most infuriating about this cycle: the people marketing these schemes know exactly what they’re doing. They rebrand it constantly — “Clean Slate,” “Credit Washing,” “Fresh Start Profile,” “Second Chance Credit” — because the old names get associated with prosecutions and the scheme needs fresh packaging.
And when you challenge them and say “this is illegal,” they do exactly what they’ve always done: they dig in. They claim you don’t know what you’re talking about. They insist it’s legal. They produce fake “legal opinions.” They point to supposed satisfied customers.
How do I know this? Because that’s what has always happened — right up until they fall. Every time.
The Real Damage Beyond Legal Risk: Beyond the criminal exposure, mass false disputes actually harm your ability to make legitimate disputes in the future. Credit bureaus flag consumers who file large numbers of disputes as potential fraud risks, making it harder to correct genuine errors. You can poison your own well for years trying to cheat the system.
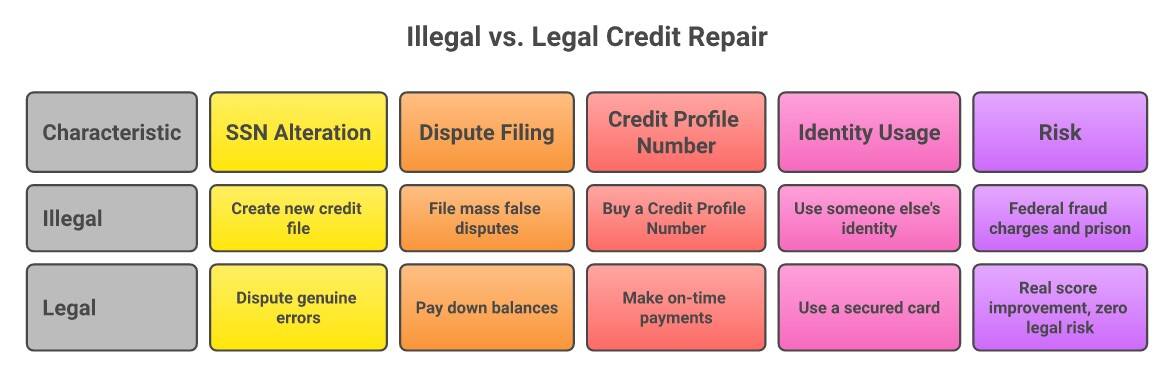
What Legitimate Credit Repair Actually Looks Like
There are real, legal ways to rebuild and improve your credit. None of them involve creating a fake identity or filing false documents. They’re less exciting to market, but they work — and they don’t come with federal prison risk:
✓ Legal Credit Repair
- Pull your free credit reports at AnnualCreditReport.com and dispute genuine errors
- Pay down balances — credit utilization is 30% of your score
- Make every payment on time going forward — payment history is 35% of your score
- Use a secured credit card or credit-builder loan to establish positive history
- Work with a nonprofit credit counselor through the NFCC
✗ “Clean Slate” Schemes
- Creating or using a synthetic identity (SSN alteration)
- Filing mass false disputes to force removal
- Paying for a “Credit Profile Number” (CPN)
- Claiming to legally separate your credit history from your SSN
- Any service promising to erase accurate negative information
I understand the appeal of a fresh start. I filed bankruptcy in 1990 and rebuilt everything. The difference is that bankruptcy is a legitimate, legal fresh start built into federal law for exactly that reason. If your debt situation has become unmanageable, there are real legal options — including bankruptcy — that actually solve the problem without criminal exposure. The Find Your Path quiz can help you figure out which approach fits your situation.
Key Takeaways
- “Clean Slate,” credit washing, and CPN schemes are federal crimes — not loopholes
- This scheme has been prosecuted for decades; the name just keeps changing
- Marketers will insist it’s legal right up until federal charges are filed
- Mass false disputes can damage your ability to make legitimate disputes later
- Legitimate credit rebuilding takes time but carries no criminal liability
- If your debt is the real problem, bankruptcy may be a faster, legal path to a genuine fresh start
The Bottom Line
The “Clean Slate” credit repair scheme is not a loophole. It is not a secret the credit bureaus are hiding from you. It is not a gray area. It is federal fraud — the same federal fraud that has been prosecuted since before social media existed. The name changes every few years because the old name becomes associated with criminal charges. That is the only thing that changes. If someone is selling you a “Clean Slate” today, they are selling you a scheme that was prosecuted in the 1990s, the 2000s, the 2010s, and the 2020s. The outcome for the people selling it is always the same.
Frequently Asked Questions
What is the “Clean Slate” credit repair method?
The “Clean Slate” method refers to schemes that claim to create a new, clean credit profile by altering your Social Security number, filing mass false disputes, or creating synthetic identities. It’s being heavily marketed on social media as a secret or loophole. It is a federal crime under the Fair Credit Reporting Act and identity fraud statutes.
Is it legal to get a Credit Profile Number (CPN)?
No. A Credit Profile Number (CPN) is a nine-digit number that scammers sell as a substitute for your Social Security number on credit applications. Using one is federal fraud. There is no legal basis for CPNs despite what sellers claim. The FTC and DOJ have prosecuted people who sell and use them.
Can accurate negative information be legally removed from my credit report?
No. Accurate negative information — late payments, collections, bankruptcy — stays on your credit report for the legally specified period (typically 7 years for most items, 10 years for Chapter 7 bankruptcy). The only information you can legally dispute is information that is genuinely inaccurate or unverifiable. Anyone claiming to remove accurate negative information through legal means is lying to you.
What happens if I pay a company to do “Clean Slate” credit repair for me?
You may face federal criminal charges. Participating in the scheme — even as the consumer, not the marketer — can expose you to fraud charges, particularly if you then use the fraudulent credit file to apply for loans or credit. The FTC has repeatedly warned consumers that hiring a credit repair company does not protect you from liability for the company’s illegal acts if you knowingly participate.
What is a legitimate way to rebuild credit after financial hardship?
Legitimate credit rebuilding involves disputing genuine errors, paying on time, reducing balances, and establishing new positive credit through secured cards or credit-builder loans. It takes time — typically 12 to 24 months to see meaningful improvement. If debt is the underlying problem rather than credit score alone, exploring debt management plans, consolidation, or bankruptcy may address the root issue. Use the Find Your Path quiz to explore your options.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
The same goes for another viral “hack” — the “609 letter” that supposedly forces bureaus to delete any debt. It’s a disclosure right, not a delete button.



