

Part of the Credit Counseling Hub: This post is one piece of my complete Credit Counseling: The Complete Guide — what a DMP costs, who it helps, the agency financial stability risk, and how to verify any agency before enrolling.
Quick Answer: Analysis of IRS Form 990 filings from 43 nonprofit credit counseling agencies — including both NFCC members and independent agencies — shows that roughly half operate at a financial deficit in any given year. The sector got a temporary boost from COVID-era stimulus in 2020–2021, then returned to its structural pattern of thin margins and widespread deficits by 2022. If you’re considering a debt management plan, understanding the financial health of the organization holding your money matters.
Expert Context: I founded Debt Counselors of America in 1994 — later renamed Myvesta — and ran it as president for a decade. I watched credit counseling agency finances from the inside: the fair share revenue dependencies, the enrollment pressure on counselors, the merger conversations when reserves ran low. I eventually shut the organization down in 2006 because I loved helping people and hated running a large organization. This analysis isn’t academic — it’s what I always suspected the numbers would show.
To build a data-driven picture of where this industry stands, I analyzed IRS Form 990 filings from 43 nonprofit credit counseling agencies across the country — 32 members of the National Foundation for Credit Counseling (NFCC) and 11 independent agencies operating outside the NFCC network. The data covers 2019 through 2023, with early 2024 data from the first agencies to file. Source: ProPublica’s Nonprofit Explorer.
What I found should matter to anyone currently enrolled in a debt management program — or considering one.
About half of all credit counseling agencies spend more than they bring in every year. That’s not a crisis — but it’s not the stability picture the industry projects to consumers.— Steve Rhode, The Get Out of Debt Guy
The Complete Five-Year Picture: 43 Agencies, $242M–$275M in Annual Revenue
| Year | Agencies Reporting | Combined Revenue | Combined Expenses | Net Surplus / (Deficit) | % Agencies in Deficit |
|---|---|---|---|---|---|
| 2019 | 43 | $242.0M | $248.1M | ($6.2M) | 51% |
| 2020 | 42 | $246.0M | $240.2M | $5.8M | 33% |
| 2021 | 43 | $277.0M | $248.4M | $28.6M | 21% |
| 2022 | 42 | $257.3M | $258.9M | ($1.6M) | 50% |
| 2023 | 40 | $274.8M | $267.9M | $6.9M | 50% |
| 2024 (2 orgs, partial) | 2 | $16.3M | $16.8M | ($515K) | 100% |
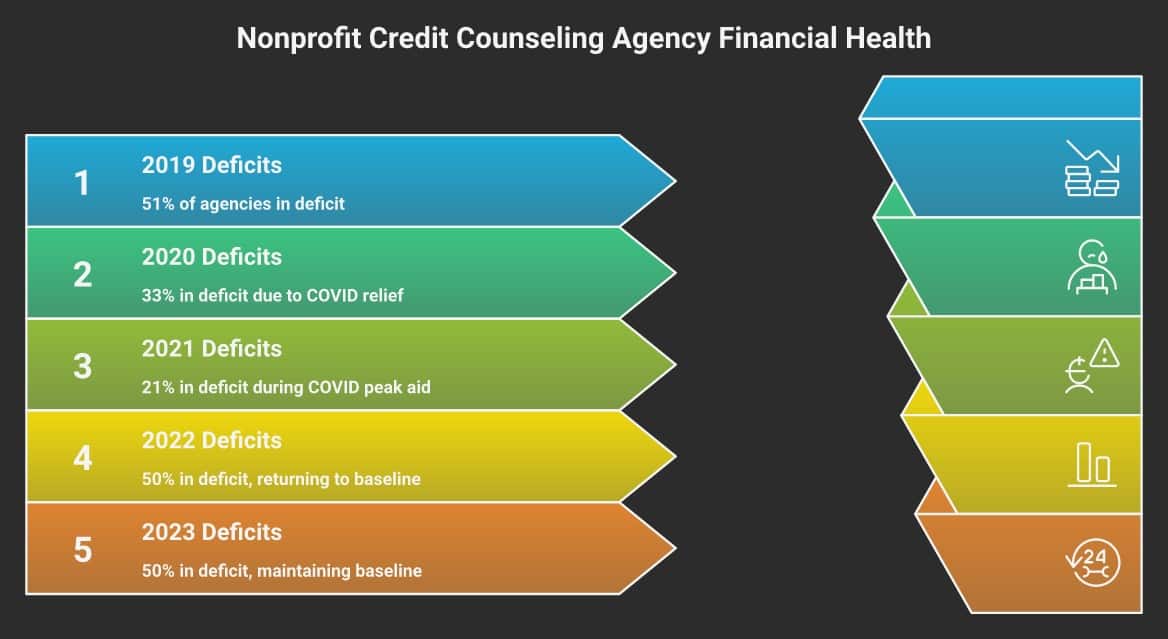
What “In Deficit” Means: When a nonprofit spends more than it collects, it draws down reserves, takes on debt, or cuts services. For agencies holding client payments destined for creditors each month, even temporary financial strain creates real operational risk for enrolled clients.
NFCC Members vs. Independent Agencies: Does Accreditation Make a Difference?
One question worth asking: do NFCC-accredited agencies, which must meet minimum financial standards to maintain membership, fare better than their independent counterparts? The data tells a nuanced story.
NFCC Members (32 agencies)
- 2019: 56% in deficit
- 2020: 34% in deficit
- 2021: 19% in deficit (COVID peak)
- 2022: 48% in deficit
- 2023: 50% in deficit
- Avg revenue/org 2023: ~$7.5M
Non-NFCC Independent Agencies (11 agencies)
- 2019: 36% in deficit
- 2020: 30% in deficit
- 2021: 27% in deficit
- 2022: 55% in deficit
- 2023: 50% in deficit
- Avg revenue/org 2023: ~$5.0M

NFCC membership does not appear to provide meaningful protection against operating deficits. In 2022 and 2023, both groups converged at roughly 50% deficit rates. Independent agencies actually had lower deficit rates in 2019–2021, though by 2022 both groups were equally stressed. NFCC accreditation standards appear to filter for organizational age and infrastructure more than financial sustainability.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
What NFCC Membership Does and Doesn’t Guarantee: NFCC membership requires agencies to use certified counselors, maintain certain operational standards, and participate in peer review. It does not guarantee the agency will be financially solvent in any given year, or that it won’t merge, consolidate, or close. Verify the financial health of any specific agency separately from its membership status.
The COVID Mirage That Masked a Structural Problem
If you look only at 2021, the credit counseling industry looks healthy. Combined revenue hit $277 million — its best year in the study period. Only 21% of agencies ran deficits. Net assets grew substantially across the sector.
But that picture is misleading. In 2021, several forces converged that had nothing to do with sustainable business improvement:
- Federal stimulus payments reduced financial distress — agencies collected fair share fees on existing enrollments without the cost of onboarding new distressed clients
- Consumer spending dropped, which paradoxically helped DMP clients stick to repayment plans and reduced program dropouts
- Remote operations compressed overhead and staffing costs industry-wide
- Some agencies received pandemic-related federal relief funding that appeared as revenue in their 990s

The minute those tailwinds ended, the industry reverted to form. In 2022, revenue dropped back while expenses held, and 50% of agencies returned to deficit — nearly identical to the pre-pandemic baseline. The 2021 surplus was a windfall, not a structural transformation.
The Claim: “Nonprofit credit counseling agencies are stable, government-approved alternatives to debt settlement companies.”
The Reality: Roughly half of all nonprofit credit counseling agencies — both NFCC members and independents — operate at a spending deficit in any given year outside of the COVID anomaly. The sector’s structural baseline has been about 50% of agencies spending more than they earn since at least 2019.
The Size Gap: Most Agencies Are Smaller Than You Think
The credit counseling industry’s combined revenue sounds substantial at $275 million. But that figure is spread across dozens of relatively small regional nonprofits. The median agency in this analysis is far smaller than the headline numbers suggest.
Eleven agencies in this analysis operate on annual revenues under $1 million. At that scale, a single large creditor contract loss or one unexpected legal expense eliminates the margin entirely. These are the agencies most likely to close, merge, or significantly cut services when financial pressure hits.
The Consolidation Story Hidden in the Data
The NFCC lists 49 U.S. member agencies on its website. Despite exhaustive research — cross-referencing brand names, former names, parent organizations, and IRS databases — I could only confirm active, independently-filed IRS 990s for 32 of them.
The missing 17 fall into distinct categories:
- Rebranded agencies that never updated their IRS registration — several NFCC members file 990s under names the public has never heard of, a legacy of acquisitions and rebrands from the 1990s–2000s CCCS network
- Programs buried inside larger parent organizations — at least one NFCC member’s credit counseling division is a program inside a $160M statewide social services organization; the credit counseling revenue is invisible in the consolidated 990
- Agencies with no active IRS filings — some NFCC members appear to have ceased independent operations but remain on the membership list
- Agencies absorbed by larger members — addresses in the IRS database for several defunct regional agencies now match the headquarters of Money Management International, the sector’s largest operator
What Consolidation Means for DMP Clients: When an agency is acquired, your debt management plan account transfers to the acquiring organization — often without adequate notification. Payment routing instructions can change. If you miss a creditor payment during a transition, the creditor can revoke the reduced interest rate that makes your DMP worthwhile. You could be years into a plan and lose the benefit because of an administrative handoff you didn’t know was happening.
The Liability-to-Asset Ratio: Signs of Recovery
Not all findings point in the same direction. The industry’s liability-to-asset ratio — the share of total assets funded by debt rather than reserves — improved over the study period, from 43.1% in 2019 to 41.4% in 2023. This suggests the agencies that survived built somewhat stronger balance sheets.
Combined net assets (the sector’s financial reserves) grew from roughly $282 million in 2019 to an estimated $340+ million by 2023, largely because the 2020–2021 COVID surplus allowed stronger agencies to build cushions before the deficit years returned.
Industry Strengths (2019–2023)
- Combined revenue grew ~14% over the period
- Liability-to-asset ratio improved from 43% to 41%
- COVID windfall years allowed reserve building
- Larger agencies (NFCC members) average $7.5M revenue — not fragile
Industry Concerns (2019–2023)
- ~50% deficit rate is the persistent structural baseline
- Operating margins under 3% in good years
- Sector is consolidating — fewer independent agencies
- Smallest agencies (under $1M) are financially precarious
- 2024 early data: both filing agencies already in deficit
- Membership lists include dormant/absorbed agencies
What This Means If You’re Considering a Debt Management Plan
I am not telling you to avoid credit counseling agencies. For the right situation, a debt management plan is a legitimate tool. Reduced interest rates — typically 6–9% versus the 20–29% you’re paying now — can save you real money on unsecured debt.
Not sure whether a debt management plan is even the right fit for your situation? My Find Your Path quiz walks through your specific circumstances and helps you understand all your options — including whether something like bankruptcy might actually serve your future better than a 4-5 year DMP.
But the picture sold to consumers in enrollment conversations is often incomplete. You’re told you’re joining a stable nonprofit alternative to predatory debt settlement. The IRS data tells a more complicated story about what “stable” actually means in this sector.
- Search your agency on ProPublica Nonprofit Explorer — look at 3+ years of 990 filings before enrolling
- Ask whether the agency is NFCC-accredited — it won’t prevent deficits, but it provides transition protocols if the agency closes or merges
- Keep your own records of every payment confirmation the agency sends to creditors
- If you receive notice of a merger or acquisition, contact each creditor directly to confirm your payment setup transferred correctly
- Ask what the agency’s process is if it can no longer service your account
The Risk Nobody Mentions at Enrollment: A single missed creditor payment on a DMP can cause the creditor to cancel the interest rate concession permanently. You can be years into a plan and lose the reduced rate because of your agency’s administrative failure — not yours. This risk is real when 50% of agencies are under financial stress in any given year.

What I Saw from the Inside
When I ran Myvesta — the organization I founded in 1994 — the financial pressure these organizations operate under was constant. The mission is genuine. The counselors who work in this sector largely care deeply about their clients.
But mission and financial sustainability are different things. The data shows that about half of credit counseling agencies, whether NFCC-accredited or independent, operate at a deficit in a typical year. Deficits are funded by reserves — and when reserves run out, agencies cut counselors, raise fees, merge, or close.
The consumer enrolled in a DMP usually doesn’t know any of this is happening. They’re making their monthly payment and assuming everything is fine.
The IRS 990 data now lets you see what was previously invisible. Use it.
Key Takeaways
- 43 nonprofit credit counseling agencies analyzed via IRS Form 990 (2019–2023): 32 NFCC members + 11 independent
- Roughly 50% of agencies — both NFCC and non-NFCC — run annual deficits in a typical year
- NFCC membership does not protect against operating deficits; deficit rates converged at ~50% for both groups by 2022–2023
- The 2021 surplus was COVID-driven stimulus, not structural improvement; deficits returned in 2022
- Sector consolidation is ongoing — at least 17 NFCC members have no verifiable independent IRS filings
- Smallest agencies (under $1M revenue) are financially precarious and represent real risk for enrolled clients
- Verify any agency’s financial health via ProPublica before enrolling; keep your own payment records throughout
The Bottom Line
IRS Form 990 data on 43 nonprofit credit counseling agencies shows that roughly half spend more than they earn in a typical year — a structural pattern that existed before COVID and returned immediately after the pandemic stimulus ended. NFCC accreditation doesn’t change this baseline; NFCC members and independent agencies converged at identical ~50% deficit rates by 2022–2023. Before enrolling in a debt management plan, verify the financial health of your specific agency through ProPublica’s Nonprofit Explorer, keep your own records of every creditor payment, and understand that a single missed payment — due to your agency’s administrative failure, not yours — can permanently revoke the interest rate concession that makes a DMP worthwhile in the first place.
Frequently Asked Questions
Is credit counseling worth it even if agencies have financial difficulties?
Yes, in the right circumstances. A debt management plan through an accredited agency can reduce your interest rates to 6–9% and consolidate payments. The financial instability I describe is real, but the benefit for the right type of debt is also real. Research the specific agency you’re considering — their 990 filings are publicly available — before enrolling.
What happens to my debt management plan if my agency closes?
Your DMP can be severely disrupted. If an agency closes without an orderly transition, creditor payments can be missed and interest rate concessions revoked. NFCC-accredited agencies have transition protocols requiring notification and account transfer assistance; non-NFCC agencies have no such safety net. Stick with NFCC-accredited agencies when possible, and keep your own payment records regardless.
How do credit counseling agencies make money?
Their primary revenue is “fair share” fees — typically 8–15% of your monthly payment, paid by creditors for collecting on their behalf. This creates an inherent tension: agency revenue depends on keeping you enrolled in the program, not necessarily graduating you from debt as quickly as possible. Secondary revenue comes from setup fees ($30–$75) and monthly client administrative fees charged directly to you.
Does NFCC membership mean an agency is financially healthy?
No. NFCC membership requires certified counselors and minimum operational standards, but the data shows NFCC members run deficits at roughly the same rate as independent agencies — about 50% in any given year. Membership is a credential for service standards, not a financial health guarantee. Always check the agency’s Form 990 separately.
How can I find out if my credit counseling agency is financially healthy?
Search your agency’s legal name (not just its brand name — many agencies file under different legal names) on ProPublica’s Nonprofit Explorer. Look at: total revenue vs. expenses (deficit years?), net assets trend (growing or declining cushion?), and total liabilities (rising debt burden?). Any nonprofit is legally required to provide its three most recent 990s upon request.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



