

Quick Answer: Minnesota lost 1,300 farms in 2025, and Chapter 12 farm bankruptcies jumped 46% nationally — but the story most farmers aren’t hearing is that Chapter 12 bankruptcy was specifically designed to keep farms operating, not shut them down. Filing is not failure. For many farmers, it’s the tool that buys time to restructure debt while keeping the land.
Expert Context: I filed bankruptcy myself in 1990 after my real estate business collapsed during an economic downturn I didn’t cause and couldn’t control. What I hear from farmers today — breakeven prices higher than what they can sell for, debt compounding while income shrinks — is the same math I lived through. The shame around filing is a luxury that costs more than the filing itself.
Minnesota lost 1,300 farms between 2024 and 2025, and the state’s Chapter 12 farm bankruptcy filings jumped 300% — from just 4 in 2024 to 13 in 2025, according to data from the American Farm Bureau Federation and reporting by KSTP. Nationally, 315 farms filed Chapter 12 bankruptcy in 2025 — a 46% increase — as costs outpaced income for the third straight year.
Key Terms Defined
Chapter 12 Bankruptcy: A federal bankruptcy chapter created specifically for family farmers (and fishermen). Unlike Chapter 7, which liquidates assets, Chapter 12 lets a farmer reorganize debt while continuing to operate the farm. It also allows discharge of certain tax debts — a feature unavailable under other bankruptcy chapters.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Working Capital: The cash and liquid assets a farm has on hand after short-term obligations. When working capital shrinks below debt-service requirements, the farm is operating in the danger zone — the math is broken even if the crops are growing.
Chapter 12 vs. Chapter 7: Chapter 7 wipes the slate but forces liquidation. Chapter 12 restructures the debt load, freezes collection, and gives the farmer 3–5 years to reorganize — often including converting short-term operating loans into longer-term land-secured debt.
What’s Breaking the Math for Minnesota Farmers
“Our breakeven price is higher than what we’re able to sell for,” said Darin Johnson, president of the Minnesota Soybean Growers Association. That’s a sentence I’ve heard from people in financial crisis across every industry I’ve ever worked with. When revenue can’t cover costs, debt fills the gap — and once you’re borrowing to survive rather than to grow, the math starts to compound against you.
According to the Federal Reserve Bank of Minneapolis, about 75% of projected 2025 farm income growth came from government payments — not market gains. Corn prices averaged $4.29 per bushel, approximately the break-even point. Operating loans in 2025 averaged 30% larger than prior years, and farmers are taking longer to repay them.
Rob Tate of the Minnesota Corn Growers Association put it plainly: it’s “the difference between breaking even and losing money.” For farmers already deep in multi-year debt cycles, that margin isn’t theoretical. It’s existential.
The National Chapter 12 Farm Bankruptcy Crisis
Minnesota’s 300% jump in filings looks dramatic, but it’s part of a nationwide pattern. According to the American Farm Bureau Federation, Chapter 12 filings rose to 315 nationally in 2025, making this the third consecutive year of increases. Over 160,000 farms closed between 2017 and 2024 — the current crisis didn’t start last year.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
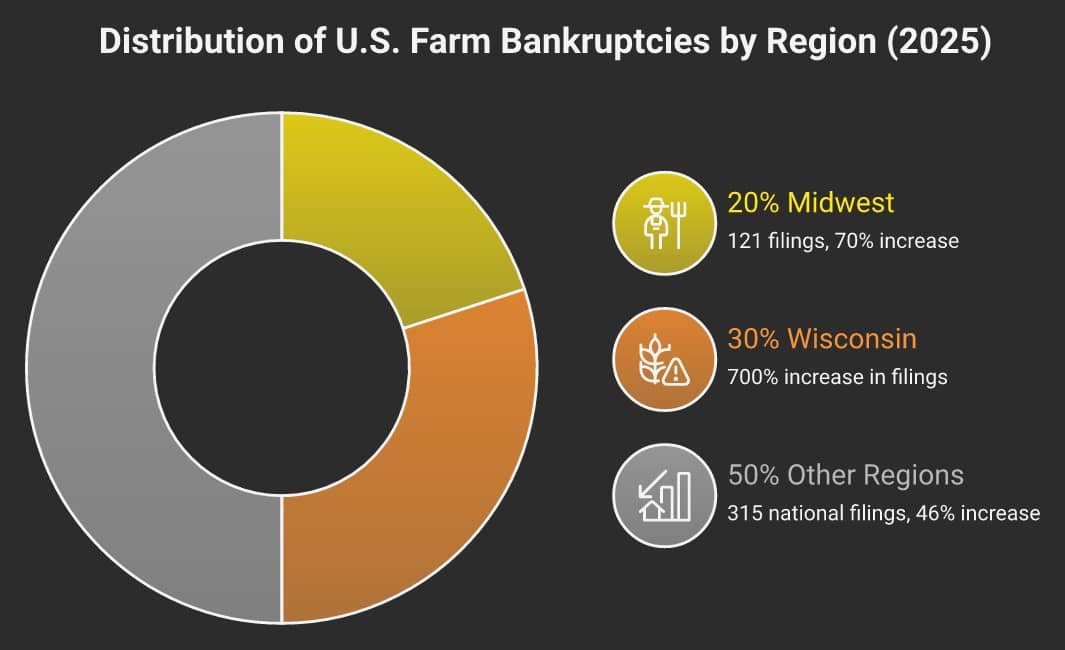
The Worst-Hit States in 2025: Wisconsin saw a 700% increase in Chapter 12 filings. Missouri, 167%. Iowa, 220%. Georgia, 145%. The Midwest filed 121 cases total — up 70% — and the Southeast filed 105. No region was spared.
Total U.S. farm debt is projected to hit $624.7 billion in 2026, with interest expenses alone reaching $33 billion. The Investigate Midwest analysis found that U.S. farmers faced $44 billion in losses in 2025 as costs rose and markets shrank.
Why Chapter 12 Is a Tool, Not a Death Sentence
The Assumption: “Filing bankruptcy means losing the farm.”
The Reality: Chapter 12 was specifically designed to let farmers reorganize debt while continuing to operate. Farms can sell partial assets, convert operating loans to land-secured debt, and discharge qualifying tax obligations — all while staying in business. The goal is restructuring, not liquidation.
As the Minneapolis Fed notes, an Iowa bankruptcy attorney described what many farmers are doing in Chapter 12: “borrowing money on the land” — converting high-pressure short-term operating loans into longer-term, land-secured debt. That restructuring buys years of breathing room that informal negotiations with a lender rarely provide.
Chapter 12 also uniquely allows discharge of certain tax debts — a feature not available under Chapter 7 or Chapter 13. For a farm that has had multiple years of losses with associated tax complications, this alone can change the financial picture significantly. The 2017 federal legislation that clarified these provisions made Chapter 12 considerably more powerful than it was before.
Who’s Most at Risk — and Who Can Still Be Saved
The Minneapolis Fed flags crop-only producers as facing the weakest working capital ratios compared to diversified operations. Farms that rely entirely on a single commodity — corn, soybeans, rice — with no livestock or diversification have no buffer when that commodity market collapses. They’re the most likely to hit a wall before they reach out for help.
There’s also an eligibility gap worth knowing: many struggling farms don’t qualify for Chapter 12 because they rely on off-farm income to support the family. That off-farm income can disqualify them from the debt-to-income ratios Chapter 12 requires. If that’s your situation, Chapter 13 or Chapter 11 may be alternatives worth discussing with a farm bankruptcy attorney.
Not Sure Which Path Is Right? I built a free tool to help people in financial stress think through their options. Find Your Path takes about 5 minutes and helps you see the full picture — including whether bankruptcy makes sense for your situation.
Federal Assistance: The USDA Farmer Bridge Program
The USDA has allocated $11 billion for its Farmer Bridge Assistance Program. If you’re a Minnesota farmer in distress, document your situation now — not later. Federal assistance programs have application windows, income thresholds, and eligibility requirements that catch people off guard. Waiting until the crisis is acute often means waiting past the deadline.
Minnesota also has a state-level agricultural mediation program that can serve as an early warning system before bankruptcy becomes the only option. According to Agweek, Minnesota mediation cases were actually signaling this crisis years before the bankruptcy numbers hit — and mediation is almost always less costly and faster than formal bankruptcy.
Don’t Wait Until the Land Is Gone: The biggest mistake I see in debt situations — farming or otherwise — is waiting until options narrow to one. Chapter 12 protection freezes collection actions and gives you time to negotiate from a position of legal protection. That protection evaporates if you wait until a lender has already initiated foreclosure proceedings.
The Outlook: It Gets Harder Before It Gets Easier
A North Dakota lender told the Minneapolis Fed: “If prolonged into 2026, we could see some fail.” The USDA’s own projections show farm income will be lower over the next 10 months than in 2025 — which was itself weaker than it initially appeared. The Minnesota Reformer reports that Midwest bankruptcies rose 70% in 2025 following years of compounding financial stress.
That’s not a crisis that resolves on its own. For farmers who are already in the danger zone, the math points one direction. Getting ahead of it — with legal protection, with restructuring, with a clear view of the options — is always better than reacting after the crisis hits.
Key Takeaways
- Minnesota lost 1,300 farms in 2025; state Chapter 12 filings jumped 300% year over year
- Nationally, 315 Chapter 12 farm bankruptcies were filed in 2025 — a 46% increase — making this the third straight year of increases
- Total U.S. farm debt is on track to hit $624.7 billion in 2026, with $33 billion in interest expense alone
- Chapter 12 was designed to keep farms operating through debt restructuring — not to force liquidation
- Crop-only producers and single-commodity farms face the highest risk; diversified operations have more cushion
- USDA’s $11 billion Farmer Bridge Assistance Program and Minnesota’s mediation program are available — but have windows
The Bottom Line
The farm crisis in Minnesota — and across the Midwest — is real, structural, and worsening. It’s the predictable result when costs outpace income for years running and debt fills the gap. Chapter 12 bankruptcy is not a surrender; it is a legally protected restructuring tool specifically designed for family farmers to keep operating while reorganizing unworkable debt. Farmers who wait too long lose the protection Chapter 12 provides. The math of farming — like all debt math — doesn’t lie, and the math right now says early action beats reactive crisis management. If federal programs, mediation, or bankruptcy are on the table, the time to explore them is before a lender forces the conversation.
Frequently Asked Questions
What is Chapter 12 bankruptcy and how is it different from other bankruptcies?
Chapter 12 is a specialized federal bankruptcy chapter created specifically for family farmers and fishermen. Unlike Chapter 7, which liquidates assets to pay creditors, Chapter 12 allows farmers to reorganize their debts while continuing to operate the farm. It also allows discharge of certain tax debts — a feature not available under Chapter 7 or 13 — and gives farmers 3–5 years to repay debts under a court-approved plan. According to the Federal Reserve Bank of Minneapolis, it is the primary tool keeping some farmers in business during the current crisis.
How many farms filed Chapter 12 bankruptcy in 2025?
According to the American Farm Bureau Federation, 315 farms filed Chapter 12 nationally in 2025, a 46% increase from 2024. The Midwest saw 121 filings (up 70%) and the Southeast saw 105 filings (up 69%). Minnesota specifically had 13 filings — a 300% increase from just 4 in 2024. This marks the third consecutive year of rising farm bankruptcy filings in the U.S.
Will filing Chapter 12 bankruptcy mean losing my farm?
Not necessarily — and that’s the key distinction most people miss. Chapter 12 is specifically designed to prevent farm liquidation by giving farmers legal protection while they restructure debt. Farms can continue operating, partial asset sales are allowed, and collection actions are frozen while the reorganization plan is implemented. Many farm bankruptcy attorneys describe Chapter 12 as converting short-term, high-pressure operating loans into longer-term land-secured debt — which changes the repayment timeline significantly without forcing a sale.
What USDA assistance is available for struggling Minnesota farmers?
The USDA has allocated $11 billion for the Farmer Bridge Assistance Program for farmers facing financial distress. Minnesota also has a state agricultural mediation program that can help farmers negotiate with lenders before the situation reaches bankruptcy. According to Agweek, Minnesota mediation cases were an early warning signal for the current crisis — meaning farmers who used mediation early had more options than those who waited.
Why are farm bankruptcies rising so sharply now?
The American Farm Bureau Federation points to a combination of declining farm income, rising operational costs, and increasing debt loads compounding over multiple years. Operating loans averaged 30% larger in 2025, and farmers are taking longer to repay them. Commodity prices for corn and soybeans have been near or below break-even, while input costs — fuel, fertilizer, equipment — have remained elevated. About 75% of 2025 farm income growth came from government payments, not market gains. Without market recovery or significant cost reduction, the math keeps pointing the wrong direction.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



