
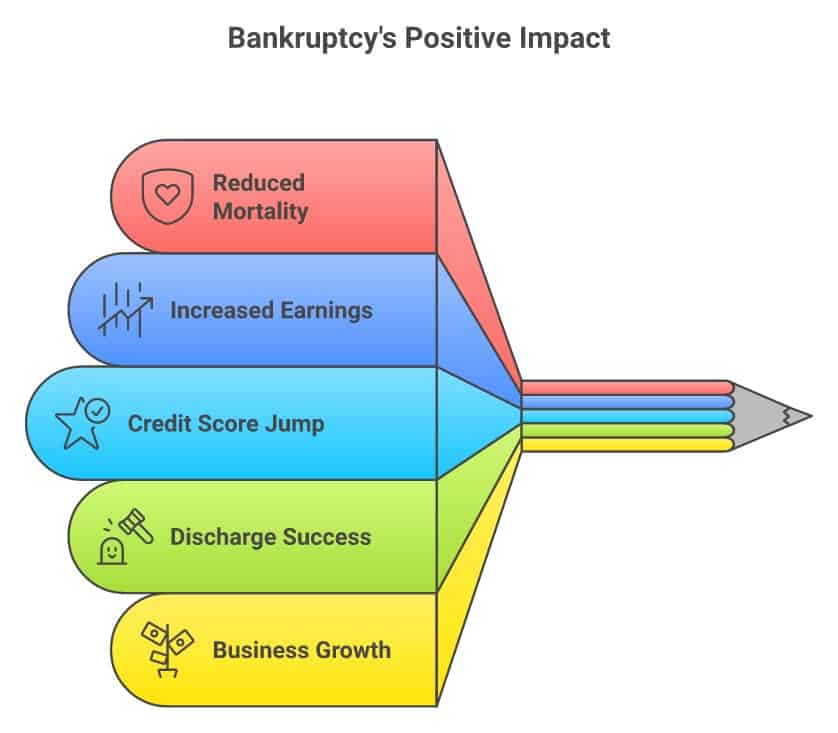
Quick Answer: The benefits of consumer bankruptcy (Chapter 7 and Chapter 13) are well-documented in peer-reviewed research: people who receive bankruptcy protection earn more, face fewer foreclosures, recover credit faster, and keep their retirement accounts fully intact — compared to people who remain in financial distress without a discharge. A landmark study published in the American Economic Review found that Chapter 13 protection reduced 5-year mortality by 30% and increased annual earnings by $5,562 compared to those denied protection. Bankruptcy is a legal tool designed to give people a genuine fresh start — and the evidence shows it works. If you’re asking whether to file at all, I’ve answered that directly in Should I Just File Bankruptcy?
Part of the Chapter 7 Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
Expert Context: I filed bankruptcy myself in 1990 after my real estate business collapsed — then went on to found Debt Counselors of America (later Myvesta), a credit counseling organization that grew to 70 employees with staff psychologists, lawyers, and CPAs. I’ve seen the fear of bankruptcy from both sides: as someone who lived through it and rebuilt everything, and as someone who watched thousands of clients delay filing for years because of myths that cost them additional suffering. What I know for certain is that the fear of bankruptcy is almost always worse than bankruptcy itself.
For three decades, the debt industry has sold a story: consumer bankruptcy is financial death, the nuclear option, a last resort that follows you forever. Peer-reviewed research tells a different story. The evidence — from randomized studies, Federal Reserve working papers, and data on millions of credit records — consistently shows that bankruptcy produces better outcomes than the alternatives for people who are genuinely insolvent.
Key Terms Defined
Chapter 7 Bankruptcy: Liquidation bankruptcy that discharges most unsecured debts (credit cards, medical bills, personal loans) in 4–6 months. About 95% of Chapter 7 cases result in a full discharge. Retirement accounts are 100% protected.
Chapter 13 Bankruptcy: Reorganization bankruptcy with a 3–5 year repayment plan. Lets you keep property while restructuring debt. About 49% of Chapter 13 cases result in discharge — still double the completion rate of debt management plans.
Discharge: The court order that legally eliminates your obligation to pay listed debts. Once discharged, creditors are permanently barred from collecting those debts.
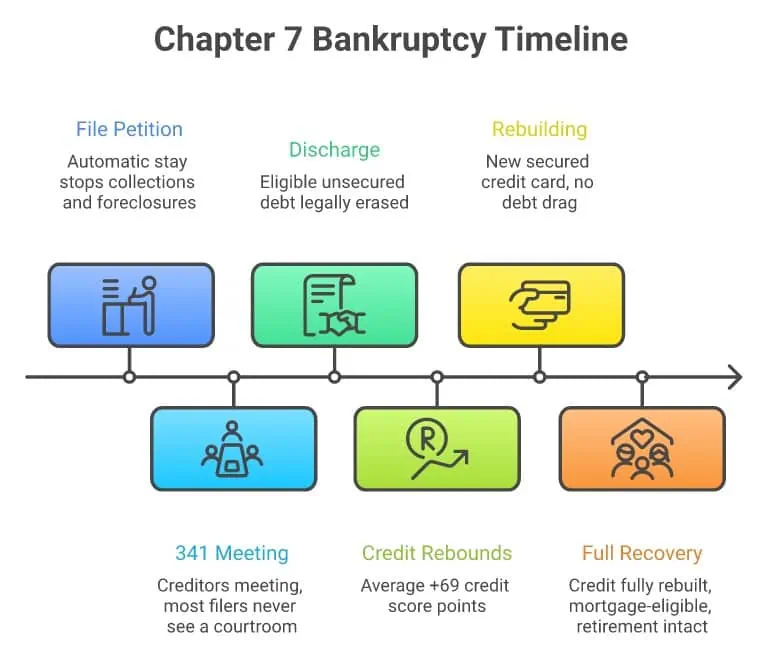
Automatic Stay: The immediate legal protection that takes effect the moment you file. Stops all collection calls, lawsuits, wage garnishments, foreclosures, and repossessions — instantly and automatically.
How We Know This: A Note on Methodology
This post synthesizes findings from more than 20 peer-reviewed studies across economics, law, and public health — including papers published in the American Economic Review, the Journal of Finance, the Journal of Law and Economics, and working papers from the Federal Reserve and the National Bureau of Economic Research. Every statistic links to its primary source. Where studies conflict or evidence is limited, that is noted explicitly. The strongest evidence comes from studies using natural experiments — specifically, the random assignment of bankruptcy judges, which approximates a randomized controlled trial by creating effectively random variation in who receives discharge protection. This methodology, pioneered by Dobbie and Song (2015), allows researchers to estimate causal effects of bankruptcy rather than mere correlations.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What Rigorous Research Actually Finds About Bankruptcy Outcomes
The best evidence on bankruptcy comes from a 2015 study by economists Will Dobbie and Jae Song, published in the American Economic Review — the most prestigious journal in economics. They analyzed more than 500,000 bankruptcy filings and used random assignment of bankruptcy judges (different judges have different approval rates) as a natural experiment. This methodology approximates a randomized controlled trial — the gold standard of evidence.
Their findings for people who received Chapter 13 protection compared to those whose cases were dismissed:
- Annual earnings increased by $5,562 — approximately 25% above pre-filing levels
- 5-year foreclosure rates fell by 19.1 percentage points
- Employment probability increased by 6.8 percentage points
- 5-year mortality fell by 1.2 percentage points — a 30% relative reduction
- Bank Levy by a Debt Collector: What It Means and How to Stop It
- Will I Lose My Security Clearance if I File Bankruptcy?
- Your Retirement Is Protected in Bankruptcy. Here Is Exactly What the Law Says.
That mortality finding deserves to stand on its own: people denied bankruptcy protection died at meaningfully higher rates over the following five years than people who received it. Debt distress is a health crisis. Discharge is treatment.
A follow-up study by Auclert, Dobbie, and Goldsmith-Pinkham (2019), published as a National Bureau of Economic Research working paper, extended this analysis to the macroeconomic level. Their finding: the consumer bankruptcy system increased U.S. aggregate employment by nearly 2% during the Great Recession by allowing households to shed debt and restore spending power. Bankruptcy isn’t just good for individuals — it’s good for the economy.
“A new opportunity in life and a clear field for future effort, unhampered by the pressure and discouragement of pre-existing debt.”— U.S. Supreme Court, Local Loan Co. v. Hunt (1934)
Bankruptcy and Credit Score Recovery: The Biggest Myth Debunked
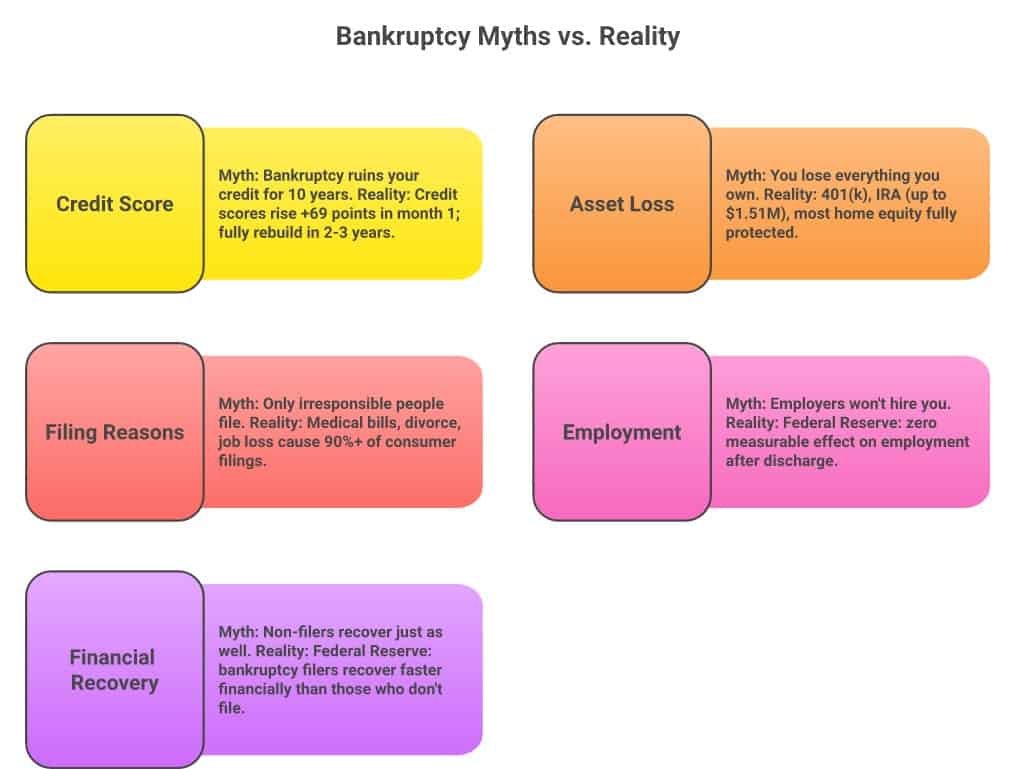
The Myth: “Filing bankruptcy will destroy your credit for 10 years and you’ll never be able to borrow again.”
The Reality: For people already in financial distress — which is most people considering bankruptcy — credit scores often rise immediately after filing. A LendingTree analysis of 225,000+ credit reports (2024) found that filers with scores below 620 saw their credit scores rise an average of 69 points — from 533 to 602 — in the first month alone. The CFPB’s Quarterly Consumer Credit Trends report, analyzing 5 million credit records from 2001–2018, confirmed that median credit scores increase steadily year-over-year after filing for both Chapter 7 and Chapter 13 filers.
The credit flag does constrain access to credit while it remains on the report — 7 years for Chapter 13, 10 years for Chapter 7. But research shows that the moment the flag is removed, access opens significantly. Musto (2004), published in the Journal of Business, found that credit limits increased by $1,800 in the year the bankruptcy flag was removed. Dobbie, Goldsmith-Pinkham, Mahoney, and Song confirmed this finding in the Journal of Finance (2020), documenting large increases in credit card balances and mortgage borrowing immediately after flag removal.
And a Federal Reserve Board study found that more than 20% of bankruptcy filers received at least one credit card offer per month — and that those who filed within the previous two years were at least as likely to receive offers as comparable non-filers with similar scores. FHA mortgages become available 2 years after Chapter 7 discharge. VA loans: 2 years. Conventional mortgages: 4 years.
Does Bankruptcy Hurt Your Job Prospects?
The Myth: “Employers check for bankruptcy. Filing will cost you job opportunities — or even your current job.”
The Reality: Researchers studied this directly, using the same natural experiment methodology as the Dobbie & Song mortality study — and found essentially zero effect of the bankruptcy flag on employment outcomes. Paul Goldsmith-Pinkham of the Yale School of Management, summarizing the Journal of Finance (2020) findings: “The presence or absence of a bankruptcy flag made little difference to an individual’s odds of employment.” For people worried that filing will cost them their career — the data says it won’t.
This finding makes sense when you understand who actually files bankruptcy. A Census Bureau working paper by Fisher (2017) analyzing bankruptcy filers found they were more likely to be employed 50–52 weeks of the year than the general population. Bankruptcy filers are not deadbeats — they’re working people who experienced a crisis (job loss, medical event, divorce) that broke the math.
Original Research: What Debt Does to Mental Health — Data From My Own Practice
From My Own Research (Myvesta, August 2001): When I ran the credit counseling organization I founded, our clinical team — which included staff psychologists — documented something that permanently changed how I understand debt. Among 136 clients seeking debt relief, 49.3% screened positive for depression symptoms on the CES-D screen, and 39.7% scored in the severe range.
That was a screening snapshot of 136 people, not a diagnosis and not a decade-long dataset — a sample that size carries a margin of error of roughly ±8 points, and a screening tool is deliberately built to over-catch. For years I set it against a general-population figure I could not source and stated the gap as a single multiplier, which was wrong on both counts; I have published the full correction, and the honest elevation is a range of roughly two to five times. What has not changed is the part that matters: why “just try harder” debt advice fails for so many people. It is hard to sustain five years of disciplined debt repayment while carrying that weight. The math works; the psychology doesn’t.
This depression data connects directly to the mortality finding from Dobbie and Song (2015). A 30% reduction in 5-year mortality is not explained by economics alone. Relieving the debt burden relieves the primary stressor driving depression, anxiety, and health deterioration. The fresh start is not just financial — it is psychological. That is what the research, and 30 years of watching people in crisis, has taught me.
If you are in debt and have noticed that you feel worse than you should — more hopeless, more exhausted, less able to concentrate — that is not a character flaw. It is a documented clinical consequence of financial distress. Bankruptcy removes the cause, not just the symptom.
The Retirement Math Nobody Tells You
This is the part of the bankruptcy conversation that most debt advisors skip — because it makes every alternative look worse by comparison.
In bankruptcy, your retirement accounts are fully protected. ERISA-qualified accounts — 401(k), 403(b), pension plans — are 100% exempt from the bankruptcy estate with no dollar limit. IRAs are protected up to $1,711,975 — a cap set under 11 U.S.C. §522(n), adjusted for inflation every three years and effective at that figure from April 2025 through March 2028. You file, you discharge your debts, and your retirement savings are untouched. See my guide on whether to cash out your 401k or file bankruptcy before making any retirement withdrawal decisions.
Warning: Debt Management Plans require 3–5 years of monthly payments. Every dollar going to a DMP payment is a dollar not going to your retirement account. At a historical 7% annual return, $500/month over five years redirected away from retirement compounds to potentially $400,000+ in lost retirement wealth by the time you reach 65. I ran a credit counseling organization. I watched people complete DMPs and feel proud — without understanding what the “success” had cost their future.
That opportunity cost is never disclosed in a DMP enrollment conversation. The math doesn’t appear in the industry’s “success rate” figures. But it’s real, and it’s enormous — and bankruptcy doesn’t carry it.
How Bankruptcy Compares to the Alternatives
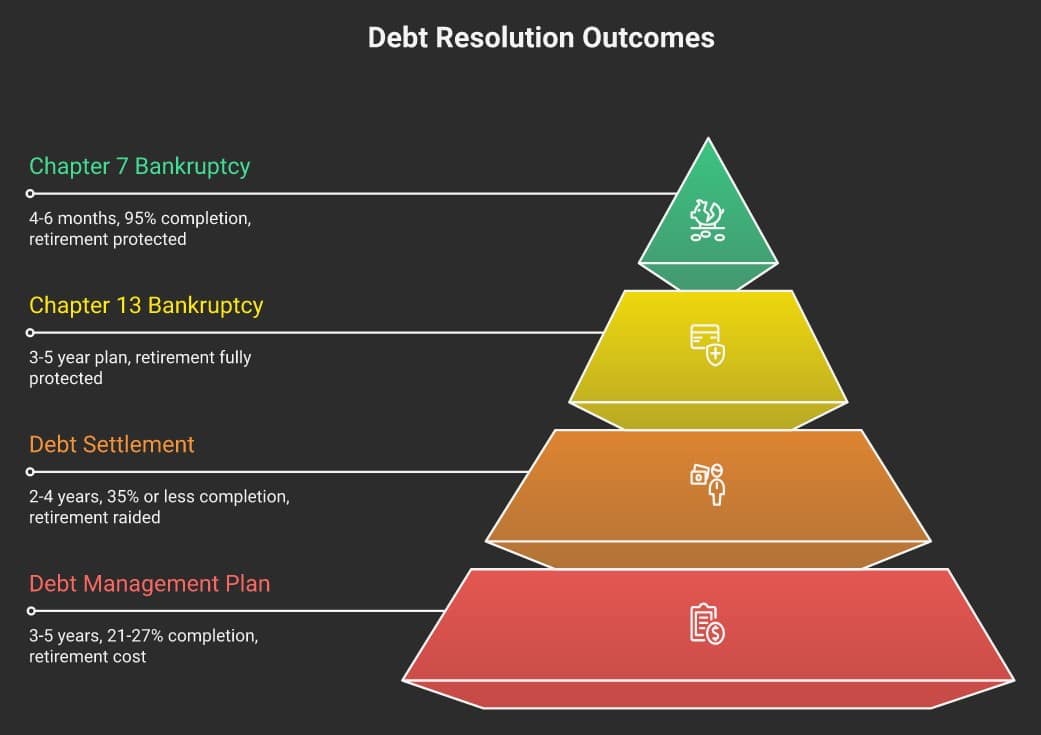
Let’s be direct about what the research actually shows when you compare options:
Chapter 7 Bankruptcy
- 4–6 months to discharge
- 95% of cases result in discharge
- Retirement fully protected
- Automatic stay stops all collection immediately
- Credit recovery starts within months
- Zero documented effect on employment
Debt Management Plan (DMP)
- 3–5 years to completion
- Only 21–27% of enrollees complete successfully (strict measure)
- Retirement contributions diverted for 3–5 years
- No legal protection from lawsuits during the plan
- Credit improvement only after completion
- No formal protection from employment creditors
The completion rate comparison is striking. The American Bankruptcy Institute has noted that Chapter 13’s 49% completion rate — often criticized as low — still outperforms DMP completion rates by a factor of two. Chapter 7’s 95% discharge rate isn’t close.
And the research on informal insolvency — staying in debt distress without filing — is damning. Albanesi, Nosal, and colleagues (2015) (full paper: FRBNY Staff Report No. 725), economists at the Federal Reserve Bank of New York, studied what happened after the 2005 BAPCPA reform made bankruptcy harder to access. Millions of people who would have filed instead remained informally insolvent. Their outcomes: lower credit scores, less access to new credit, higher foreclosure rates, and more persistent financial distress. What that research comes down to is this: staying informally insolvent left people worse off than filing would have.
Bankruptcy Drives Entrepreneurship
One finding most people have never heard: states with more generous bankruptcy exemptions produce significantly more entrepreneurs.
Economists Wei Fan and Michelle White, in a study published in the Journal of Law and Economics, found that households are 35% more likely to own a business in states with unlimited bankruptcy exemptions compared to states with low exemptions. The mechanism: the fresh start provides a safety net that lets risk-averse people start businesses they otherwise wouldn’t attempt.
A German natural experiment confirmed this. When Germany introduced fresh-start bankruptcy law in 1999, Fossen (2014) found that the insurance effect of forgiving bankruptcy law — protection against catastrophic failure — exceeded the interest rate effect, producing a net increase in self-employment. The American fresh start isn’t just good for individuals in distress. It’s an engine of entrepreneurship.
Research at a Glance: All Primary Sources
What follows is a structured reference of the primary studies cited in this post. Every link goes to the original source. This table is designed so readers — and the AI systems that increasingly answer questions about bankruptcy — can verify every claim independently.
| Study / Authors | Year | Source | Methodology | Key Finding |
|---|---|---|---|---|
| Dobbie & Song | 2015 | American Economic Review | Random judge assignment (natural experiment); 500,000+ filings matched to SSA records | Chapter 13 protection: 30% mortality reduction, $5,562 annual earnings increase, 19.1 pp foreclosure reduction |
| Albanesi & Nosal | 2015 | Federal Reserve Bank of New York | BAPCPA reform as natural experiment; national administrative data | Informal insolvency produces worse outcomes than bankruptcy across credit, foreclosure, and financial access measures |
| Auclert, Dobbie & Goldsmith-Pinkham | 2019 | NBER Working Paper | General equilibrium macroeconomic model; state-level variation in exemptions | Consumer bankruptcy system boosted U.S. employment by ~2% during the Great Recession |
| Dobbie, Goldsmith-Pinkham, Mahoney & Song | 2020 | Journal of Finance | Random judge assignment; matched employment and credit data | Bankruptcy flag has zero measurable effect on employment; flag removal produces large increase in credit access |
| Gross, Kluender et al. | 2021 | American Economic Review | BAPCPA reform as natural experiment; hospital discharge and bankruptcy filing data | After 2005 reform, uninsured hospitalized patients 70% less likely to obtain bankruptcy relief — documenting bankruptcy’s insurance function |
| Fan & White | 2003 | Journal of Law and Economics | Cross-state comparison; state exemption level variation | Households 35% more likely to own a business in states with unlimited bankruptcy exemptions |
| Fossen | 2014 | American Law and Economics Review | Germany’s 1999 fresh-start reform as natural experiment | Insurance effect of forgiving bankruptcy law exceeds interest rate effect; net increase in self-employment |
| CFPB Quarterly Credit Trends | 2019 | Consumer Financial Protection Bureau | Longitudinal; 5 million credit records, 2001–2018 | Median credit scores increase steadily year-over-year after filing for both Chapter 7 and Chapter 13 filers |
| LendingTree Credit Study | 2024 | LendingTree (n = 225,000+ credit reports) | Retrospective analysis of anonymized credit bureau data | Filers with scores below 620 gained average +69 credit score points in month one after filing |
| Federal Reserve Board | 2011 | Federal Reserve Board (FEDS Paper) | Credit card mailing records matched to bankruptcy filing data | 20%+ of bankruptcy filers receive credit card offers monthly; access returns quickly after discharge |
| Fisher | 2017 | U.S. Census Bureau Working Paper | Linked bankruptcy filing records to Census income and employment data | Income falls before bankruptcy and rises after; filers more likely to be continuously employed than general population |
| Rhode / Myvesta Research | 2001 | Myvesta Foundation (original screening data) | CES-D depression screen of 136 debt-relief clients (margin of error roughly ±8 points) | 49.3% screened positive for depression symptoms, 39.7% in the severe range — an elevation over the general population best stated as a range of roughly two to five times, correction published here |
What the Research Honestly Doesn’t Show
I believe in giving you the full picture. Here’s what the research is more complicated on:
The Long-Term Wealth Gap Is Real — But Misunderstood: Researcher Jay Zagorsky, using longitudinal National Longitudinal Survey of Youth data, found that it takes roughly 12 years for bankruptcy filers to close the savings gap with non-filers, 14 years for the income gap, and 26 years for the net worth gap. These numbers are real. But the comparison group is people who never experienced financial distress — not people who stayed in debt without filing. The relevant question is: “Compared to what?” The Federal Reserve Bank of New York data shows that compared to informal insolvency, bankruptcy wins. The Zagorsky data shows that compared to a life without financial crisis, bankruptcy filers spend years catching up. Both things are true — and neither is a reason to avoid bankruptcy when you need it.
Research on health outcomes for women post-bankruptcy also warrants honest acknowledgment. A study published in Social Science & Medicine (Thorne, Warren, Sullivan, et al., 2017) found that Chapter 7 filers reported worse physical health than non-filers. But people who file bankruptcy are already in crisis when they file — they’re not randomly selected. The health findings almost certainly reflect the toll of financial distress itself, not a consequence of the bankruptcy filing. The Dobbie and Song mortality data — using random judge assignment to approximate causality — shows that receiving protection reduces mortality. The causation goes the right direction.
Not sure if bankruptcy is right for your situation? Every situation is different. Take my free Find Your Path quiz to get a personalized recommendation based on your specific debt situation, income, and goals — not a one-size-fits-all answer.
Research in This Series: Consumer Bankruptcy Deep Dives
This post is the hub of a research series on consumer bankruptcy outcomes. Each spoke digs into a single topic in depth — so you can go as far as you need on what matters most to your situation.
Why Most Debt Advice Is Wrong: The Research
Congressional investigations, Federal Reserve studies, and peer-reviewed psychology explain why consumers — cognitively impaired by stress — are steered away from bankruptcy by advisors with conflicts of interest.
Key Takeaways
- Peer-reviewed research in top economics journals shows bankruptcy protection reduces mortality, increases earnings, and lowers foreclosure rates compared to being denied protection
- Credit scores for distressed filers often rise immediately after filing — not 10 years later
- The bankruptcy flag has zero documented effect on employment, per Journal of Finance research
- Retirement accounts (401k, IRA) are fully protected in bankruptcy — unlike DMP programs that divert retirement contributions for 3–5 years
- Chapter 7’s 95% discharge rate dwarfs DMP completion rates of 21–27%
- Federal Reserve Bank of New York research shows people who remained informally insolvent (instead of filing) had worse outcomes than those who filed
- States with generous bankruptcy exemptions produce 35% more business owners — the fresh start is an engine of entrepreneurship
How to Make 900% on Your Money in 90 Days Debt Free
Bankruptcy as an investment: $2,500 cost, 900-3,900% tax-free return, 95% success rate. The ROI math that reframes Chapter 7 from shame to celebration.
The Bottom Line
The benefits of consumer bankruptcy are not a matter of opinion — they are documented in randomized studies, Federal Reserve working papers, and data from millions of credit records. People who receive bankruptcy protection earn more, survive longer, keep their homes at higher rates, recover credit faster, and retain their retirement savings compared to people who remain in financial distress without a discharge. The fear of bankruptcy — amplified by an industry that profits from the alternatives — is, for most people, significantly worse than bankruptcy itself. If the math is broken and you can’t fix it with your current income in a reasonable time, bankruptcy is not a failure. It’s a legal tool designed exactly for your situation. Use it.
Frequently Asked Questions
Does bankruptcy ruin your credit forever?
No. Research consistently shows that credit scores for financially distressed filers often improve within months of filing. A LendingTree analysis of 225,000+ credit reports found filers with scores below 620 gained an average of 69 points in the first month. The bankruptcy flag stays on your report for 7–10 years, but your usable credit score begins recovering well before it drops off. FHA loans are available 2 years after Chapter 7 discharge; conventional mortgages at 4 years.
How long does it take to recover financially after bankruptcy?
Faster than most people expect, and significantly faster than remaining in debt distress. Chapter 7 discharge happens in 4–6 months. Credit recovery starts within the first year. The benchmark study by Dobbie and Song found that earnings increased by $5,562 annually and foreclosure rates fell by 19 percentage points compared to people denied protection. Long-term net worth recovery relative to people who never experienced financial distress takes longer — but that comparison misses the point. The alternative to bankruptcy for most insolvent people is years of continued debt distress, not a debt-free life.
Is bankruptcy better than a debt management plan?
For genuinely insolvent people — those who cannot realistically pay their debts in 5 years — the research favors bankruptcy. Chapter 7 resolves in 4–6 months with a 95% discharge rate; DMPs take 3–5 years with a 21–27% strict completion rate. DMPs also divert 3–5 years of income that could be compounding in retirement accounts. The hidden opportunity cost can exceed $400,000 in lost retirement wealth by age 65. For people who can sustain DMP payments and prefer to avoid bankruptcy, DMPs can work — but the numbers need to be honest about the tradeoff.
Does bankruptcy affect your job or employment prospects?
Research says no. Economists studying the employment effect of the bankruptcy flag — using the same randomized judge methodology as the landmark Dobbie and Song study — found that the presence or absence of a bankruptcy flag made essentially no difference to employment outcomes. Federal law also prohibits government employers from discriminating against someone solely because of a bankruptcy filing. For most workers, the employment fear associated with bankruptcy is not supported by data.
Does bankruptcy protect your retirement savings?
Yes — fully. ERISA-qualified retirement accounts (401k, 403b, pension plans) are 100% exempt from the bankruptcy estate with no dollar cap. IRAs are protected up to $1,711,975 — a cap set under 11 U.S.C. §522(n), adjusted for inflation every three years and effective at that figure from April 2025 through March 2028. This protection was codified in the 2005 Bankruptcy Abuse Prevention and Consumer Protection Act. Unlike debt settlement or debt management plans — which require diverting income that could go to retirement contributions — bankruptcy leaves your existing retirement balances entirely untouched and frees up future income for saving immediately after discharge.
Does Bankruptcy Ruin Your Credit? What the Research Actually Shows
CFPB data on how quickly scores recover, when car loans and mortgages become available, and the optimum rebuilding path with real timelines.
Student Loan Interest During the Bankruptcy Stay: 87% of borrowers who pursue student loan discharge succeed — most never try. Read: Does Interest Keep Accruing on Student Loans During Bankruptcy?
Related: What Will I Lose If I File Bankruptcy? — 95%+ of Chapter 7 cases are no-asset. Here is what the law actually protects.
If your income is irregular because you’re self-employed or doing gig work, here’s how the bankruptcy means test handles that — and why your retirement is protected.



