
Quick Answer: Debt shame is not a personal verdict on your character — it is a physiological state, a cognitive impairment, and a documented industry tool. Peer-reviewed research in neuroscience, psychology, and clinical psychiatry shows that financial loss activates the same brain circuits as physical pain, that money worry consumes the mental bandwidth needed to weigh options, and that shame (unlike guilt) causes avoidance behaviors that make debt worse. The collection industry has used engineered shame as a manipulation tool since at least 1946. Understanding this does not make your debt smaller. It does mean you can stop accepting someone else’s manipulation as a personal verdict.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Part of a Research Series: This post is part of Why Financial Education Fails: The Research on Money Psychology and Behavior — a complete collection of research on financial education, money psychology, and debt behavior research. I’ve covered this in more depth in Mental Health Crisis Left Me With $5,000 in Debt. What Can I Do?.
Expert Context: I conducted the Myvesta Depression Study in 2001 — we surveyed 136 debt counseling clients using the CES-D depression screening instrument and found that 49.3% screened positive for depression symptoms, with 39.7% in the severe range. I long compared that to a 9.5% general-population figure; that comparison was wrong and I have corrected it in full. I also filed bankruptcy myself in 1990 and experienced what the research now confirms is a documented neurological response to financial loss — not a moral verdict. This research wasn’t available when I went through it. Now it is, and it changes what you should believe about how you feel.
I have sat with thousands of people drowning in debt. Almost none of them came to me talking about interest rates or amortization schedules. They came to me talking about shame.
They had stopped opening mail. They had stopped answering the phone. They had stopped talking to their spouse. They had started avoiding friends who might ask how things were going. And underneath all of that — the avoidance, the silence, the performance of normalcy — was a conviction that the debt was not something that had happened to them. It was something they were.
I know that feeling. I filed bankruptcy in 1990. What I know now, that I did not know then, is that this feeling is not a moral response. It is a manufactured one. And the research proving that has become quite precise.
Free Tool — Your Brain on Debt Quiz: Fear, shame, and panic don't just make debt harder — they actively drive people toward bad decisions. The free Your Brain on Debt Quiz identifies which emotional driver is in control of your financial choices right now. Take the Quiz →
Your Brain Cannot Tell the Difference Between Financial Pain and Physical Pain
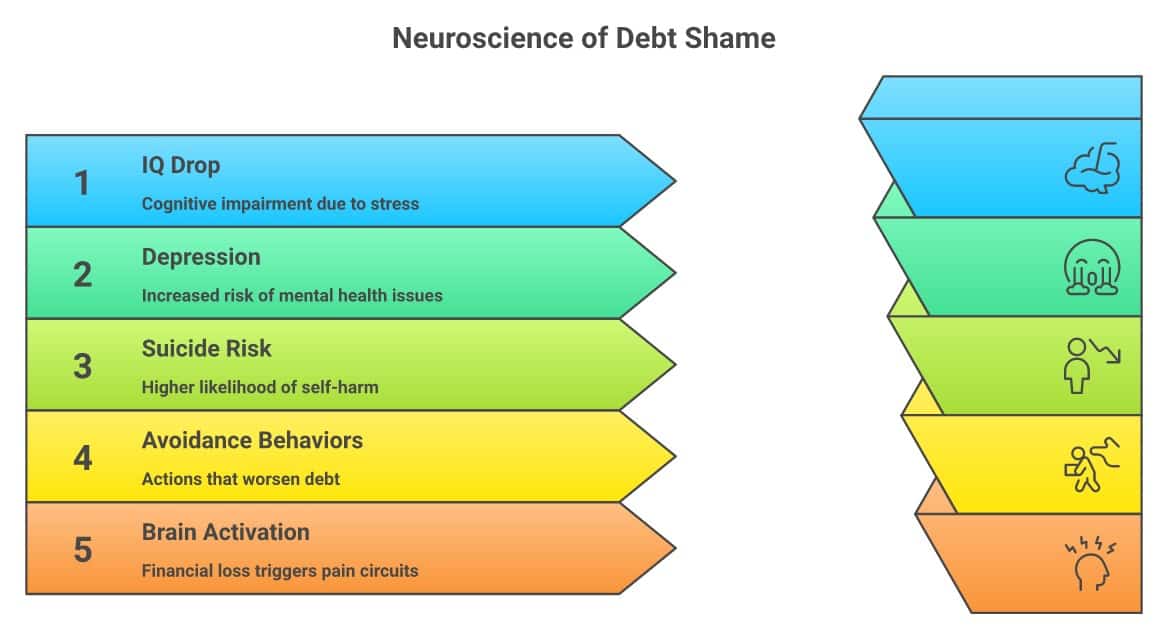
When researchers study the brain under financial loss and physical pain, they find the same neural structures activating. Feng et al. (2022), published in Human Brain Mapping, conducted a meta-analysis of neuroimaging studies and found that “monetary loss and pain, including physical pain and social pain, may recruit a common neural substrate, such as insula and ACC” — the anterior insula and anterior cingulate cortex, regions associated with pain processing.
The anterior insula was described as “a shared neural representation of monetary loss and pain.”
This is not metaphor. The neuroscience is literal: losing money and feeling physical pain share the same brain circuitry. When people say debt is “crushing” them, they are describing a physiological reality — not exaggerating for emphasis.
The Cortisol Layer: Before shame fully develops, debt stress triggers cortisol release. A 2014 study in PNAS (Kandasamy et al.) found that elevated cortisol directly alters financial risk assessment — making people “more risk-averse” in ways that can produce worse financial decisions. The same stress hormones that evolved to help us survive physical threats are now running continuously on financial threats, altering judgment circuits that were never designed for sustained activation.
A 2023 systematic review confirmed that financial stress is an independent risk factor for coronary artery disease. Debt does not just cause psychological suffering. Over time, it can damage the cardiovascular system — because the stress response triggered by chronic financial threat is physiologically indistinguishable from chronic physical threat.
Debt Eats the Mental Bandwidth You Need to Think Straight
In 2013, researchers at Princeton published a paper in Science that changed how we understand financial decision-making. Mani, Mullainathan, Shafir, and Zhao studied both rural farmers in India and mall shoppers in New Jersey. The finding was the same in both: people already under financial pressure did worse on reasoning tests in the moment, and the gap eased once the pressure did.
The same researchers studied Indian sugarcane farmers before and after their annual harvest — the same people, rich and poor at different times of year. The same farmer showed measurably diminished cognitive performance before harvest (when poor) compared to after harvest (when rich). The poverty itself was causing the impairment, not any stable characteristic of the person.
This matters enormously for how we understand debt decisions. The person sitting in a credit counselor’s office, choosing between a debt management plan and bankruptcy, is cognitively impaired relative to their own baseline. They are making the most consequential financial decision of the next several years while operating at a neurological deficit. The industry selling them a solution knows this. The person does not.
Shame and Guilt Are Not the Same Thing
The research distinction between shame and guilt is not semantics. These are neurologically and behaviorally distinct states with opposite consequences for debt outcomes.
Guilt: “I Did Something Bad”
- Motivates reparative action
- Associated with apology, correction
- Produces pro-social behavior
- Research: predicts better debt repayment
- Action tendency: fix the problem
Shame: “I Am Bad”
- Motivates withdrawal and escape
- Associated with hiding, avoidance
- Produces self-protective behavior
- Research: exacerbates financial hardship
- Action tendency: avoid the problem
Gladstone, Jachimowicz, Greenberg, and Galinsky studied this in a 2021 paper in Organizational Behavior and Human Decision Processes (nine studies, N=9,110). Their conclusion: “Shame — more so than guilt — negatively affects financial outcomes because it leads to avoidance of financial information and disengagement from one’s financial situation, exacerbating financial hardship.”
Not all negative financial feelings are the same. Guilt can motivate you. Shame paralyzes you. And the messaging that surrounds consumer debt — you are irresponsible, you chose this, you should feel ashamed — is producing shame, not guilt. It is producing the emotion that makes outcomes worse.
Guilt says: I did something bad. Shame says: I am bad. They are not the same, and they do not produce the same behavior. Only shame makes debt worse.— Steve Rhode
The Shame Spiral Is Documented in Bank Data
Gladstone et al. found evidence of the shame spiral not just in surveys but in archival bank data: people experiencing financial shame avoid looking at their accounts, delay engaging with creditors, and make financial decisions designed to reduce the emotional pain of confronting their situation rather than the material cost of their debt.
A 2023 study in the Journal of Marketing Research (Moorhouse, Goode, Cotte, and Widney) went further: even the anticipation of stigmatization — not actual judgment, just the fear of it — drives people into what researchers call “concealment behaviors”: social spending to appear normal, secrecy from friends and family, and active avoidance of professional help. They called this “helping those that hide.”
The Ostrich Effect: Debtors are not oblivious to their debt. They know. What shame changes is their action tendency — the emotional cost of confronting the situation exceeds their cognitive and emotional capacity to manage it. This is not avoidance out of ignorance. It is avoidance out of overwhelm. And the shame that produces the overwhelm was, in many cases, deliberately engineered.
Debt Is a Clinical Mental Health Crisis
The numbers from clinical research are stark enough that they deserve to be stated without softening.
A systematic review of 34 studies involving approximately 34,000 participants (Richardson, Elliott, & Roberts, 2013, Clinical Psychology Review) found:
- OR 3.24 — odds of having any mental disorder if carrying problem debt
- OR 2.77 — odds of clinical depression with problem debt
- OR 7.9 — odds of completing suicide with heavy debt
- OR 5.76 — odds of attempting or completing suicide with heavy debt
Those are not small numbers. People with problem debt are more than three times as likely to have a clinical mental health disorder. They are nearly eight times more likely to complete suicide.
In my own organization’s research at Myvesta, we surveyed 136 debt counseling clients using the CES-D depression screening scale. We found that 49.3% screened positive for depression symptoms, and 39.7% scored in the severe range. Among single women with problem debt, the figure was 58%. For years I set that against a 9.5% general-population figure and called it more than five times the national rate — a comparison that put a screening result next to a diagnosis rate. I have corrected it in full; the honest elevation is a range, roughly two to five times, on a sample of 136.
The Money and Mental Health Policy Institute in the UK found that over 100,000 people attempt suicide while in problem debt each year in England alone. One in eight people seriously behind on bills think about suicide in a given year, compared to one in 25 debt-free people.
The Bidirectional Trap: Debt causes depression. Depression impairs the cognitive and motivational capacity to address debt. Depression produces the characteristic short-termism and sustained demotivation that makes five-year repayment plans neurologically difficult to complete. The very populations being told to “stick with the budget” and “grind it out” are the populations most psychologically ill-equipped for sustained effort over multi-year timelines. This is not a character problem. It is a biological one.
Your Shame Was Engineered
The most important thing I can tell you about debt shame is this: it was designed.
Not designed in the way that everything has causes. Designed with deliberate intent, at industrial scale, using principles of applied psychology.
In 1946, an industry insider writing in The Collector magazine stated that “three-fourths of a collector’s procedure is based on the fundamentals of psychology.” The psychological fundamentals in question were the techniques for producing shame and anxiety in debtors.
By 1961, this had been operationalized. R.H. Carder of Coast-to-Coast Collections Service sent 650,000 letters to 200,000 debtors specifically designed, according to court documents, to make debtors “feel as though he were standing on a railroad track with an express train on its way.” The goal was to produce anxiety sufficient to compel payment, while making the debtor feel that their situation was a result of their own moral failure.
Ethnographic research on debt collection found that collectors were trained to “deflate the customer’s status by hinting that the customer is lazy and of low moral character.” This was not individual collector behavior — this was institutional training, passed down as professional technique.
The Industry’s Message: “You spent money you didn’t have. You made bad choices. You should feel ashamed. That shame should motivate you to pay what you owe — and to avoid the shameful option of bankruptcy.”
What the Research Shows: The shame being engineered is the emotion least likely to produce constructive financial behavior. Shame predicts avoidance. Guilt predicts repair. The industry messaging is producing the worst possible emotional state for making good decisions — while simultaneously using that state to steer you toward the products that generate fees.
Academic research (Sanghera and Satybaldieva, 2021) documents how lenders deploy moral discourse to “de-politicize and normalize the unequal relationship between lenders and borrowers.” Calling people irresponsible for carrying debt shifts the moral frame from systemic credit practices — aggressive marketing, obscured terms, interest rate structures designed to keep balances growing — to individual character. This framing serves the creditor. It does not describe reality.
The Bankruptcy Shame Is Especially Artificial
A Gallup poll in the 1960s found that nine in ten Americans would “rather die than go bankrupt.” This is not a natural cultural response to a legal process. It is the result of decades of cultivated stigma that served the interests of every alternative to bankruptcy: collection agencies, settlement companies, lenders who preferred to keep consumers struggling rather than discharge their debts.
The Bible describes mandatory debt release every seven years (Deuteronomy 15) — the Jubilee. Ancient Near Eastern civilizations built regular “clean slate” decrees into their economic systems because they understood that debt can overwhelm people independent of character. The moral framing of debt as personal failure is historically recent and culturally specific to contexts where creditor industries had political and economic power to promote that framing.
Churches file bankruptcy. Corporations file bankruptcy strategically, as a business optimization — and are celebrated for financial acumen. When individuals do the same thing, the narrative calls it failure. The asymmetry is not logical. It is political.
What to Do With This Information
Understanding the psychology of debt shame will not make your debt smaller. But it can do something important: it can change the lens through which you evaluate your options.
- The avoidance is not weakness — it is a documented response to shame-producing stimuli. Recognizing it as a behavioral pattern you can consciously override changes its power.
- The cognitive impairment is real — which means making major debt decisions in acute crisis is neurologically disadvantaged. Getting outside your crisis state before choosing a path is not a luxury. It is a prerequisite for clear thinking.
- The shame was manufactured — knowing this does not eliminate the feeling, but it changes its authority. Someone engineered this response to serve their interests, not yours.
- The “last resort” framing is a sales tool — bankruptcy is described as a last resort by people who profit from you not using it. The research on outcomes tells a different story.
If you haven’t been able to say this to anyone: The Confidential Debt Confessional is completely anonymous — no account, no name required. People consistently report that writing it down privately takes the edge off. It’s not a solution. But for people carrying debt entirely alone, it’s often the first crack in the wall.
Talk to a bankruptcy attorney before enrolling in anything else. A free bankruptcy consultation — which most attorneys offer — gives you the full picture of all your options before any advisor with a financial incentive to steer you elsewhere gets to make their case. Start with the widest view, then narrow. Use the Find Your Path tool to see which options apply to your situation.
Related: Take the free Debt Stress Test — a 2-minute PHQ-9 clinical screening that reveals whether your debt stress has crossed into depression. Take the Free Screening →
Key Takeaways
- Debt shame is not a moral verdict — it is a physiological state. The same brain circuits that process physical pain process financial loss.
- A 2013 Science study found money pressure measurably narrows reasoning in the moment — an effect that eased once the pressure lifted, which is why acute financial crisis is the worst moment to decide
- 49.3% of people seeking debt help screened positive for depression symptoms — a large elevation over the general population, honestly a range of roughly two to five times (Myvesta research, 2001, n=136)
- Shame (unlike guilt) predicts avoidance and worse outcomes. The messaging designed to make you feel ashamed is producing the emotion least likely to help you.
- Collection industry training manuals from 1946 and 1961 document the deliberate engineering of debtor shame as a payment-collection technique
- Bankruptcy stigma was cultivated by industries that profit from alternatives to bankruptcy — not from any natural moral consensus about debt
- Removing debt improves cognitive function by about 0.25 standard deviations and reduces anxiety by 11% (PNAS, 2019) — resolution restores your ability to think
The Bottom Line
Debt shame is not a personal moral verdict — it is a documented biological response, a manufactured industry tool, and a clinical risk factor. Financial loss activates the same neural circuits as physical pain, and money worry consumes the mental bandwidth you need at the precise moment the most consequential financial decisions must be made. The Myvesta Depression Study found 49.3% of people seeking debt help screened positive for depression symptoms — a large elevation over the general population, honestly stated as a range of roughly two to five times. The debt relief industry has exploited this shame since 1946, when trade publications explicitly documented using psychological conditioning to prevent debtors from exercising their legal rights, including the right to file bankruptcy. Understanding that your shame response is physiological, documented, and commercially deployed is the first step to making a decision that serves your future instead of someone else’s revenue.
Part of the Debt & Mental Health Hub: This post is one piece of my complete guide to Debt and Mental Health — the research on debt and depression, the psychology of debt shame, free screening tools, and what actually helps when debt is affecting more than your finances.
Frequently Asked Questions
Is debt shame normal?
Debt shame is extremely common — but “normal” in the sense of healthy or inevitable, it is not. Research shows it is a manufactured response: deliberately cultivated by collection practices since at least the 1940s, and maintained by industries that profit from consumers staying in debt or choosing alternatives to bankruptcy. Shame is also clinically harmful: it predicts avoidance behaviors that make debt outcomes worse, not better.
Why does debt feel so much worse than it should?
Because the brain processes financial loss through the same circuits that process physical pain. Feng et al. (2022) in Human Brain Mapping found shared neural activation between monetary loss and physical/social pain. Additionally, financial stress triggers cortisol release that directly alters risk assessment. The distress you feel is not disproportionate — it is physiologically appropriate to how your brain is processing the threat.
Can shame actually make my debt situation worse?
Yes. A 2021 study in Organizational Behavior and Human Decision Processes (Gladstone et al.) found that shame — more than any other negative financial emotion — predicts avoidance of financial information, disengagement from financial management, and exacerbated hardship. Guilt motivates repair. Shame motivates escape. The collection industry has historically used messaging designed to produce shame rather than guilt.
How does depression affect debt decisions?
Profoundly. Clinical depression impairs executive function, long-term planning capacity, and sustained motivation — the exact cognitive tools required to stick with a multi-year debt repayment plan. Depression produces short-termism characteristic of present bias, making the behavioral demands of DMPs and debt settlement programs harder for the people who need them most. This is why addressing the emotional and psychological component of debt is not optional — it is prerequisite to a sustainable plan.
Does bankruptcy really carry less shame than people think?
The research suggests the shame attached to bankruptcy is far more manufactured than felt — at least among people who actually file. LendingTree’s 2024 study found credit scores rose 69 points on average in the first month after filing. Dobbie, Goldsmith-Pinkham, and Yang (2017) found no measurable employment impact from bankruptcy. The documented cultural stigma was cultivated by industries with financial interests in the alternatives. The actual legal process is a federal tool for a fresh start — one that has been used by churches, corporations, and individuals throughout American history.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



