
Quick Answer: Bankruptcy stigma was not a spontaneous cultural response to moral failure. It was manufactured — by the collection industry through deliberate psychological conditioning starting in the 1940s, and by the credit card industry through $100+ million in lobbying that embedded the word “Abuse” into federal law in 2005. The companies that profit when you don’t file bankruptcy — credit counselors, debt settlement companies, collection agencies — actively promoted the stigma that keeps you away from the option with the best-documented outcomes. The word “stigma” literally means a mark of shame. Understanding where it came from, and who put it there, changes what authority it has over your decisions.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Expert Context: I spent thirty years as an investigative writer documenting how debt relief companies operate — including how the shame messaging around bankruptcy is deployed against consumers as a deliberate sales technique. I also watched this from inside the credit counseling industry I founded in 1994. And I filed bankruptcy myself in 1990. That combination — living through the shame, running the organization that used the industry’s language, then spending three decades documenting its commercial origins — is what this research confirms and what this post is based on.
Nine out of ten Americans in the 1960s said they would “rather die than go bankrupt.” That is not a natural moral response to a legal process. That is the result of decades of cultivated fear — created by industries that had financial reasons to make you afraid.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
I know this because I have watched it from three vantage points: as someone who filed bankruptcy in 1990, as the founder of a credit counseling organization who saw how the industry talks about bankruptcy, and as an investigative writer who has spent thirty years documenting how debt relief companies operate.
The stigma is real. The suffering it causes is real. The debt decisions it produces — people grinding through five-year programs instead of taking a fresh start — are real and costly. But the source of the stigma is not a timeless truth about the moral weight of debt. It is a commercial product, manufactured by industries with financial stakes in keeping you from bankruptcy.
The Historical Origins: Stigma Was Not Always There
The moral framing of debt as personal failure is not ancient or universal. It is historically specific.
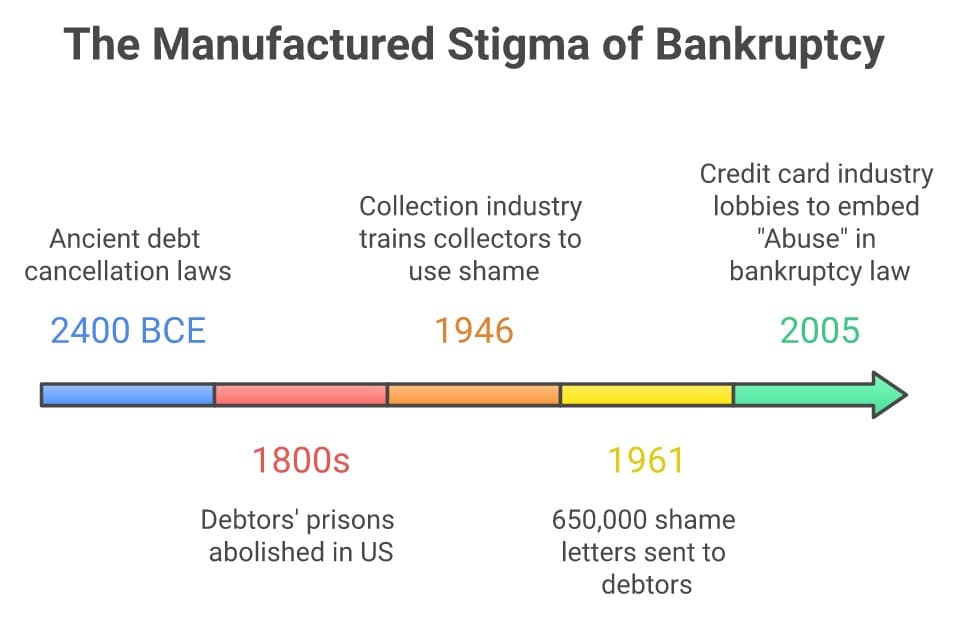
Ancient Near Eastern civilizations — including the biblical Israelites — built regular debt cancellation into their social and legal systems. The earliest known debt cancellation was proclaimed by Enmetena of Lagash around 2400 BCE. The Bible commands mandatory debt release every seven years (Deuteronomy 15:1: “Every seven years you must cancel debts”). The Jubilee year every fifty years included land and debt restoration. These were not fringe provisions — they were central economic policies, because ancient societies understood that debt can overwhelm people independent of character.
Bankruptcy laws in England and early America were originally protective instruments for creditors — ways to recover something from failed debtors — not moral judgments on the debtor’s character. Bruce H. Mann, in his landmark historical study Republic of Debtors (Harvard University Press, 2002), documents that “at the beginning of the eighteenth century, debt was equated with sin and the inability to pay one’s creditors was a moral failing.” But he also documents that “by 1800, imprisonment for debt was under attack and insolvency was no longer seen as a moral failure, merely an economic setback.”
Debtors’ Prisons, Then Reform: The United States imprisoned approximately 75,000 people annually for debt in the early nineteenth century — including future president James Wilson, a signer of the Constitution. This system was abolished not because debt became morally acceptable, but because it was economically destructive. Every person in prison for debt was a person not working to pay debt back. The system was eliminated for pragmatic reasons. The moral stigma, however, proved more durable — and more useful to certain industries.
The German sociologist Max Weber’s analysis of the “Protestant ethic” — published in 1905 — described how Calvinist theology transformed commercial success into a sign of divine favor and debt into a sign of moral weakness. This theological framework was not about debt per se. It was about asceticism, discipline, and the visible signs of predestination. But when combined with American frontier mythology — the self-made man who pulls himself up by his bootstraps — it became the cultural substrate onto which the collection industry would later graft specific emotional conditioning.
The Industry That Engineered Your Shame
By the 1940s, debt collection had become an industry with trade associations, publications, and training programs. And those training programs explicitly taught psychological techniques for producing shame in debtors.
In 1946, an insider writing in The Collector — an industry trade publication — stated that “three-fourths of a collector’s procedure is based on the fundamentals of psychology.” The psychological fundamentals in question were techniques for making debtors feel ashamed, irresponsible, and morally inferior.
By 1961, this had been operationalized at industrial scale. R.H. Carder of Coast-to-Coast Collections Service sent 650,000 letters to 200,000 debtors designed specifically to produce anxiety. Court documents describe the goal: to make debtors “feel as though he were standing on a railroad track with an express train on its way.” The letters were calibrated to produce maximum psychological pressure — not to inform, but to destabilize.
Ethnographic research on debt collection has found that collectors were trained to “deflate the customer’s status by hinting that the customer is lazy and of low moral character.” This was not individual collector aggression — it was institutional training, passed down through the industry as professional technique.
The shame you feel about your debt was deliberately engineered by an industry that profits from it. That is not a metaphor. It is documented in trade publications and court records going back to 1946.— Steve Rhode
The goal of the shame engineering was not to help you repay your debt. It was to prevent you from exercising your legal rights — including your right to file bankruptcy — so that collection could continue.
The Credit Card Industry’s $100 Million Purchase
If the collection industry engineered shame at the individual level, the credit card industry engineered it at the legislative level.
For approximately eight years beginning in the 1990s, the credit card industry lobbied Congress for what would become the Bankruptcy Abuse Prevention and Consumer Protection Act of 2005 (BAPCPA). Opponents of the bill documented that the industry spent more than $100 million on this lobbying campaign — the most expensive financial industry lobbying effort in history up to that point.
The industry’s argument was simple: bankruptcy was being abused by people who could afford to pay their debts but were choosing bankruptcy instead. They needed the word “Abuse” embedded in the name of the law. They needed the cultural narrative of the strategic defaulter — the person gaming the system — to justify making bankruptcy harder and more expensive to file.
What the Industry Promised vs. What Happened: The credit card industry told Congress that making bankruptcy harder would reduce their losses, and that savings would flow to consumers as lower interest rates. Academic research found otherwise. Michael Simkovic’s 2009 study in the American Bankruptcy Law Journal documented that “although bankruptcies and credit card company losses decreased, and credit card companies achieved record profits, the cost to consumers of credit card debt actually increased.” The industry captured the savings as profits. Consumers got nothing.
The Federal Reserve Bank of New York studied what happened to people who were pushed out of bankruptcy by BAPCPA’s higher barriers. Albanesi and Nosal (2015) found: “The decline in bankruptcy filings resulted in a rise in the rate and persistence of insolvency as well as an increase in the rate of foreclosure.” The people who couldn’t file were not better off paying their debts — they were worse off, trapped in persistent insolvency with less credit access and lower credit scores than people who actually filed.
“Insolvency is associated with worse financial outcomes than bankruptcy, as insolvent individuals have less access to new lines of credit and display lower credit scores than individuals who file for bankruptcy.”
The stigma campaign worked for the industry. It did not work for the people it targeted.
The Debt Relief Industry’s Role
The credit card industry manufactured the legislative stigma. The debt relief industry — credit counselors, settlement companies — deployed it as a sales tool.
The U.S. Senate Permanent Subcommittee on Investigations documented, in its 2005 report, that credit counseling agencies used advertisements explicitly designed to exploit bankruptcy stigma: encouraging consumers to “avoid the catastrophe of bankruptcy,” calling bankruptcy “a ten-year mistake,” and “emphasizing post-bankruptcy ramifications” — all to steer consumers into debt management plans that generated revenue for the agencies.
The Senate report further documented that “AmeriDebt counselors preyed on consumers’ fears and vulnerabilities with high-pressure sales tactics that were intrusive and often belittling.” This was not an isolated agency. It was industry-wide behavior, documented across multiple agencies in the congressional investigation.
The GAO’s 2010 undercover investigation found settlement companies explicitly using bankruptcy stigma language in sales calls — telling potential clients that bankruptcy would “ruin their credit for 10 years,” “cost them their jobs,” and “mark them as failures.” These claims were used to steer consumers toward settlement programs with documented success rates in the single digits — programs that charged 15-25% of enrolled debt in fees regardless of outcome.
The Myths vs. The Evidence
Myth 1: “Bankruptcy will destroy your credit for 10 years.”
Reality: LendingTree’s 2024 study of actual filers found average credit scores rose 69 points in the first month after filing. Filers with the worst scores (below 580) gained an average of 88.6 points. At 12 months, more than half of all filers had a score of 640 or above. The bankruptcy notation can remain on a credit report for 7–10 years, but credit rebuilds continuously from the moment of discharge — often faster than during the years of delinquency that preceded filing.
Myth 2: “You’ll lose everything you own.”
Reality: Most Chapter 7 filers keep all of their property because exemptions protect it. Federal exemptions protect retirement accounts fully (401k, IRA, pension plans). Most states protect a vehicle up to a specified equity value, household goods and furnishings, tools of the trade, and a homestead exemption. Academic research (Lawless, Littwin, Foohey, & Thorne, 2021) found the majority of Chapter 7 cases are “no asset” cases — the trustee finds no nonexempt assets to liquidate.
Myth 3: “Bankruptcy will affect your job.”
Reality: Dobbie, Goldsmith-Pinkham, and Yang (2017, Review of Economics and Statistics) studied 175,000+ bankruptcy filers linked to credit bureau records and found that bankruptcy’s effect on employment prospects was a “precise zero” — no measurable impact on getting or keeping a job. Federal law prohibits employers from discriminating against applicants solely because they filed bankruptcy (11 U.S.C. § 525).
Myth 4: “Only irresponsible people file bankruptcy.”
Reality: Research from Lawless, Littwin, Foohey, and Thorne (2021, Portraits of Bankruptcy Filers) found that the typical bankruptcy filer is employed, owns a home, and has debt primarily from medical bills, job loss, or divorce — not consumer overspending. Harvard Law professor Elizabeth Warren’s research documented that medical debt was a leading cause of bankruptcy filing. Corporations file bankruptcy as a strategic financial tool and are applauded for financial acumen. Individuals do the same thing and are called failures.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
What the Cross-Cultural Research Shows
Bankruptcy stigma is not universal. It varies dramatically by country — and those differences track, predictably, with outcomes.
Germany overhauled its insolvency law in 2021, reducing the discharge period from six years to three years, explicitly for the purpose of reducing stigma and improving post-insolvency economic recovery. The German Federal Ministry of Justice stated the reform was designed to improve “fresh start” outcomes and align with research on economic recovery.
Japan provides a cautionary example in the other direction. With some of the strongest debt shame culture in the developed world, Japan recorded approximately 3,279 debt-related suicides in 2002 — roughly nine per day. This is not a country without bankruptcy law. Japan has bankruptcy law. But the cultural shame is so severe that many people cannot access it. The endpoint of maximally cultivated debt shame is not repayment. It is death.
The United States sits in a dangerous middle: permissive bankruptcy law that is actually among the most accessible in the world, and severe cultural stigma cultivated by industries that profit from people not using it.
The Corporate Double Standard
There is a detail about bankruptcy stigma that deserves more attention than it receives: corporations use it constantly, strategically, and without shame — and are celebrated for doing so.
- Airlines (United, Delta, American, US Air) have all used Chapter 11 to restructure debts while continuing operations
- Major retailers (Sears, K-Mart, JCPenney, Neiman Marcus) have used bankruptcy to shed leases and debt
- Real estate developers routinely use bankruptcy as a financial optimization tool
- The same credit card companies that lobbied to make consumer bankruptcy harder have subsidiaries and customers that file Chapter 11 regularly
The moral framing — “you should be ashamed if you file bankruptcy” — is applied to individuals but not to corporations. This asymmetry is not moral. It is political. It reflects whose interests the stigma serves.
Churches file bankruptcy. Major nonprofits file bankruptcy. The Catholic dioceses in various cities have used bankruptcy to resolve sex abuse liability — the legal tool applied strategically, without moral condemnation. The same tool used by an individual to escape medical debt is called character failure.
Now that you know where the stigma came from: The Should I File Bankruptcy? quiz takes about two minutes and walks through your specific situation without anyone’s financial incentive attached. Then use the Find Your Path tool to see the full range of options that apply to you, and get a free consultation with a bankruptcy attorney to confirm the details for your state.
Key Takeaways
- Bankruptcy stigma was not a natural cultural response. It was engineered by the collection industry through deliberate psychological conditioning (documented from 1946) and by the credit card industry through $100+ million in lobbying for BAPCPA (2005).
- The credit card industry promised consumers would benefit from BAPCPA. Simkovic (2009) found industry captured the savings as record profits; consumer credit costs increased.
- The Federal Reserve found that avoiding bankruptcy — due to BAPCPA barriers — produced worse outcomes: more persistent insolvency, lower credit scores, higher foreclosure rates (Albanesi & Nosal, 2015).
- LendingTree (2024): credit scores rose 69 points on average in month one after filing. The “10-year credit destruction” narrative is not supported by data.
- Employment: zero measured impact on job prospects from bankruptcy filing (Dobbie et al., 2017, Review of Economics and Statistics).
- Most Chapter 7 cases are “no asset” — the typical filer keeps their property through exemptions.
- Japan’s maximally-stigmatized debt culture produces approximately 9 debt-related suicides per day. Germany reduced stigma as economic policy in 2021. The U.S. has maximum legal access and maximum manufactured stigma — a gap that serves the debt relief industry.
The most common costly consequence of bankruptcy stigma: people cash out their 401k to avoid filing, losing $100,000+ in retirement wealth to avoid a label. I cover the full math in Should I Cash Out My 401k or File for Bankruptcy?
Related: See How to Make 900% on Your Money in 90 Days — the math that proves why the collection industry manufactured bankruptcy stigma.
The Bottom Line
Bankruptcy stigma was not a spontaneous moral response to financial failure — it was manufactured by industries with financial stakes in keeping consumers away from bankruptcy. The collection industry’s own trade publications documented using psychological shame techniques against debtors since 1946. The credit card industry spent over $100 million lobbying to embed the word “Abuse” in federal bankruptcy law (BAPCPA, 2005), then captured the savings from reduced bankruptcies as record profits while consumer credit costs increased. Federal Reserve research found that people prevented from filing by BAPCPA’s higher barriers ended up with higher insolvency and foreclosure rates than people who filed. Bankruptcy stigma has a commercial origin, a commercial purpose, and a documented cost to consumers who believe it.
Frequently Asked Questions
Who benefits from bankruptcy stigma?
The industries that profit most from bankruptcy stigma are: (1) credit card companies, who benefit when consumers struggle to repay rather than discharge debt; (2) debt settlement companies, who charge 15-25% of debt for programs with documented success rates under 25%; (3) credit counseling agencies with the “fair share” model, who lose revenue when consumers file bankruptcy rather than enroll in DMPs; and (4) collection agencies, whose business is collecting debts that would otherwise be discharged. None of these industries profit from you filing bankruptcy. All have financial incentives to keep stigma high.
Is bankruptcy actually a “last resort”?
The “last resort” framing was promoted by the same industries that profit from you not filing bankruptcy. The research does not support it as a description of optimal strategy — it describes who profits from the framing, not what produces the best outcomes. Dobbie and Song (2015, American Economic Review) found that bankruptcy protection increases annual earnings by $5,562 and decreases five-year mortality by 1.2 percentage points compared to denied filers. This is not the profile of an option of last resort — it is the profile of an effective legal tool that consumers systematically underuse because of manufactured stigma.
Did BAPCPA (2005 bankruptcy reform) help consumers?
No. The credit card industry promised it would, but academic research found the opposite. Michael Simkovic’s peer-reviewed study (2009, American Bankruptcy Law Journal) found that although industry losses decreased and industry profits hit record highs, consumer credit costs actually increased. The Federal Reserve Bank of New York (Albanesi & Nosal, 2015) found that the resulting decline in bankruptcy filings produced more persistent insolvency, lower credit scores, and higher foreclosure rates. The reform benefited the industry that lobbied for it — not the consumers it claimed to protect.
Does bankruptcy really affect your ability to get a job?
No. Dobbie, Goldsmith-Pinkham, and Yang (2017) found zero measurable employment impact from bankruptcy filing across 175,000+ cases. Federal law (11 U.S.C. § 525) prohibits governmental employers from discriminating against applicants solely on the basis of bankruptcy, and courts have extended this principle broadly. The claim that “employers will see your bankruptcy” is used in debt relief sales presentations to steer consumers toward alternatives — but it does not reflect the research on actual employment outcomes.
What does the Bible actually say about debt?
Deuteronomy 15:1 commands mandatory debt release every seven years: “Every seven years you must cancel debts.” The Jubilee year (Leviticus 25) includes debt restoration. The New Testament Lord’s Prayer includes “forgive us our debts.” The use of Christian morality to stigmatize bankruptcy inverts the actual scriptural teaching on debt forgiveness. Religious bodies — including Catholic dioceses — have used bankruptcy as a legal tool. The moral stigma applied to individuals is not derived from scripture; it is derived from Protestant work ethic theology as interpreted by creditor-aligned cultural norms.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



