

Quick Answer: Nobody runs this math before you enroll in a debt management plan. The DMP counselor doesn’t run it. The settlement company doesn’t run it. The FTC doesn’t require anyone to run it. So I’m running it for you: a 35-year-old who pauses $400/month in 401(k) contributions during a 5-year DMP — plus their employer match — loses approximately $247,000 in retirement savings at age 65. Chapter 7 bankruptcy discharges the same debt in approximately 90 days. The retirement opportunity cost for 90 days: approximately $10,700. Your 401(k) is protected in bankruptcy anyway, by the Supreme Court (1992) and federal law. You are not choosing between protecting retirement and filing bankruptcy. You are choosing between a $247,000 retirement loss and a $10,700 one.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Expert Context: I ran Myvesta — a credit counseling organization I founded in 1994 — and enrolled thousands of people in debt management plans. I know exactly what we disclosed: the monthly payment, the program length, the fees. What we never disclosed, because nobody required it and nobody runs it, is the retirement opportunity cost. This calculation is my attempt to show you what should have been shown to every person who ever enrolled in one of those programs, including the ones I enrolled.
When I ran Myvesta, we enrolled thousands of people in debt management plans. We disclosed the monthly payment, the program length, and the fees. What we never disclosed — and what nobody in the industry is required to disclose — is the retirement math.
I am telling you this not to indict credit counseling. I am telling you because I ran the organization, I know what we disclosed and what we didn’t, and I think you deserve to see the calculation before you make this decision.
The Math Nobody Shows You
The financial concept involved is compound growth — the mechanism by which early retirement contributions are worth far more than late ones, because they compound over more years.
Here is the specific calculation, with stated assumptions:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Scenario: 35-year-old, $400/month employee contribution, $200/month employer match, 7% annual return, retirement at 65
No DMP — continuous contributions: $490,835 at age 65
After 5-year DMP — contributions pause at 35, resume at 40: $325,919 at age 65
Lost employee contributions: $164,916
Lost employer match ($200/month × 5 years): $82,458
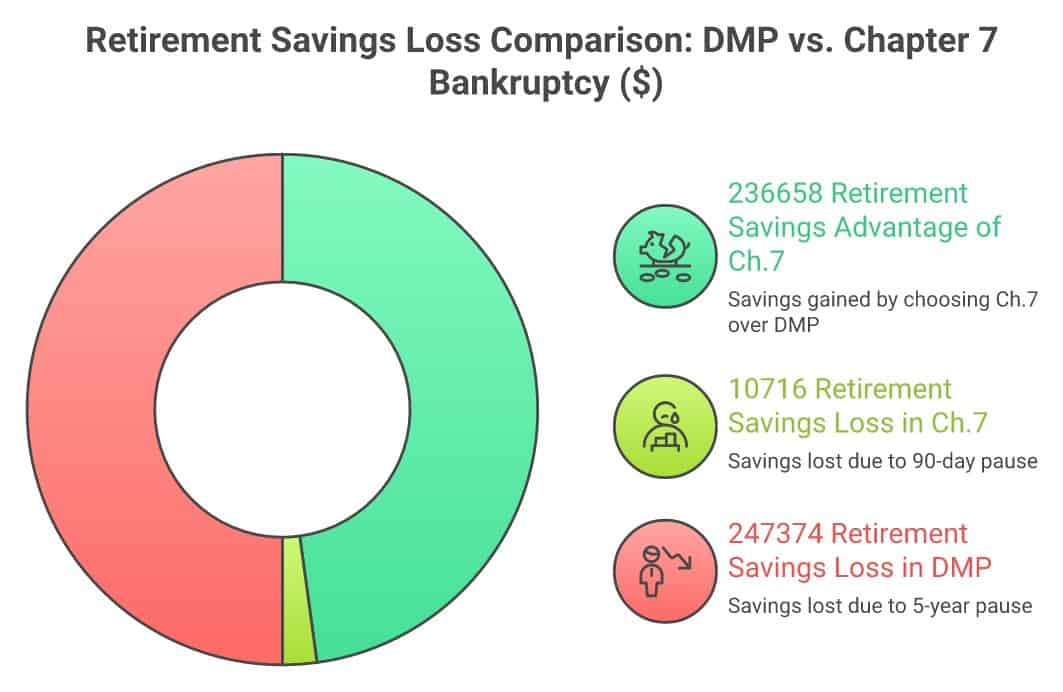
Total retirement opportunity cost of 5-year DMP: $247,374
At 10% annual return (the historical nominal S&P 500 average), a 30-year-old forgoing $500/month employee plus $200/month employer match during a 5-year DMP loses approximately $409,000 in retirement savings at age 65. That is where the “$400,000 opportunity cost” figure comes from. The exact number depends on your age, contribution amount, and return assumption — but the magnitude is consistent.
Why Early Contributions Are Worth 5.7× More Than Late Ones
This is the part that surprises people the most.
For a 35-year-old retiring at 65, $400/month contributed in Years 1–5 (ages 35–40) grows to $164,916. The same $400/month contributed in Years 26–30 (ages 60–65) grows to only $28,804.
The same dollar contribution, made 25 years earlier, is worth 5.7 times more.
The irreversible nature of delay: You cannot make up for missing the most valuable contribution years. No future contribution will ever be worth what a contribution at 35 is worth. When a 5-year DMP forces you to pause contributions at your most valuable compounding years, the retirement savings loss is permanent. “Catching up” later is mathematically possible but never recaptures compound growth from those years.
Your Retirement Accounts Are Protected in Bankruptcy Anyway
The most important thing I can tell you about the retirement argument against bankruptcy is this: it is false.
Your 401(k), 403(b), pension, and other ERISA-qualified retirement accounts are protected in bankruptcy regardless of whether you file. The Supreme Court ruled in Patterson v. Shumate (1992) that ERISA-qualified retirement plans are excluded from the bankruptcy estate — with no dollar cap, unlimited protection.
IRAs are protected up to $1,711,975 per person (as adjusted April 1, 2025, Federal Register 90 Fed. Reg. 7843, Feb. 4, 2025) under 11 U.S.C. § 522(n).
What this means for the DMP vs. bankruptcy decision: You are not choosing between “protect my retirement with a DMP” and “lose my retirement in bankruptcy.” That framing is false. Your retirement accounts are equally protected in both scenarios. The actual choice is between: (a) protecting your retirement accounts AND paying the opportunity cost of 5 years of lost growth, or (b) protecting your retirement accounts AND incurring only 90 days of lost growth while bankruptcy discharges the debt. The retirement protection argument for DMPs over bankruptcy is not supported by law.
The Disclosure Gap Is Regulatory
Credit counselors are not necessarily hiding this from you. The law does not require them to calculate or present it.
The FTC’s Telemarketing Sales Rule (16 C.F.R. § 310) requires disclosure of: the cost of the service, the estimated program length, how much to save before settlements are offered, and negative consequences of non-payment. It does not require: the retirement opportunity cost calculation, the employer match forfeited, or a comparison of the program’s long-term financial impact against Chapter 7 bankruptcy.
The mandatory pre-bankruptcy credit counseling session — required by BAPCPA before anyone can file bankruptcy — is often conducted by the same agencies that offer DMPs and receive fair share payments from creditors. The counselor who conducts that pre-bankruptcy session may be employed by an agency that generates revenue when you enroll in a DMP instead of filing.
What the Incomplete Retirement Problem Causes
The downstream consequences of inadequate retirement savings are well-documented and severe.
- 41% of households aged 55–64 have zero retirement savings (GAO, 2015)
- 80% of households with adults 60+ are financially struggling or at risk of economic insecurity (NCOA, 2024)
- Older adults with the fewest financial resources die, on average, nine years earlier than those with the greatest wealth (NCOA/HRS, 2025)
- Social Security replaces approximately 39% of pre-retirement income — designed as a supplement, not a full retirement. And if it’s your only income, settlement companies may be charging you for protection you already have
The math connects. A 35-year-old who completes a 5-year DMP and emerges with $247,000 less in future retirement wealth is on the trajectory toward exactly the financial insecurity documented in NCOA data. The DMP resolved a short-term debt problem by contributing to a long-term retirement crisis.
The Comparison Across All Three Paths
Chapter 7 Bankruptcy
- Timeline: ~90 days to discharge
- Out-of-pocket cost to file: ~$2,500 all-in (and many attorneys take a payment plan)
- Retirement opportunity cost: ~$10,716 (just the ~90-day pause)
- Retirement protection: ERISA accounts fully protected (no cap)
- Credit: +69 points avg in month 1 (LendingTree, 2024)
- Tax: No tax consequence on discharged debt
- Legal protection: Automatic stay stops collections immediately
5-Year Debt Management Plan
- Timeline: 3–5 years (historical completion: 21–26%)
- Retirement opportunity cost: ~$247,374 at age 35
- Retirement protection: Same ERISA protection as bankruptcy
- Fees: Monthly program fee (~$25–75/month) for years
- Hidden cost: Lost employer match compounding
- Credit impact: May improve over time if completed
4-Year Debt Settlement
- Timeline: 2–4 years
- Retirement opportunity cost: ~$238,647 at age 35
- Fees: 15–25% of enrolled/settled debt
- Success rate: 23% complete all enrolled debts (AFCC)
- Tax: Forgiven debt typically taxable as income
- Credit: Guaranteed damage during non-payment period
Nobody protects your retirement by choosing a debt management plan over bankruptcy. The law protects your retirement in both. What the DMP costs is five years of compound growth on contributions you couldn’t make while paying it.— Steve Rhode
I Want You to Have the Full Picture
Credit counseling has a legitimate role. For people who genuinely cannot qualify for bankruptcy, who have specific debt types that don’t discharge well, or who have the income, discipline, and stable employment to complete a multi-year program — DMPs can work. The ~21–26% historical completion rate means some people do complete them.
What I want for you is to make this decision with the retirement math visible. Not after you’ve enrolled. Before.
Run the retirement math for your situation. Use your actual monthly retirement contribution amount, your employer match, your age, and the number of years in the program. Multiply contribution months missed by what those dollars would compound to at age 65. Compare that number to the 90-day version for Chapter 7. Then talk to a bankruptcy attorney for a free consultation before deciding. The law will not make this comparison for you — but you can make it yourself.
See how the options compare for your specific numbers: The Should I File Bankruptcy? quiz takes about two minutes and walks through your situation without anyone’s sales agenda. The Find Your Path tool shows which debt options apply to your math specifically — DMP, Chapter 7, Chapter 13, settlement, and others — so you can compare what each actually means for your situation.
Key Takeaways
- A 5-year DMP costs a 35-year-old approximately $247,374 in retirement savings at age 65 (at 7% return, $400+$200/month) — the retirement opportunity cost nobody discloses at enrollment
- Chapter 7 bankruptcy costs approximately $10,716 in retirement opportunity cost — the same debt discharged in 90 days
- Your 401(k) and ERISA-qualified accounts are protected in bankruptcy regardless — by Patterson v. Shumate (1992) and 11 U.S.C. § 522. There is no “protect retirement by avoiding bankruptcy” — the protection is equal in both scenarios
- IRA protection in bankruptcy: $1,711,975 per person as of April 2025 (Federal Register)
- Early retirement contributions are worth 5.7× more than contributions 25 years later — the DMP forces you to sacrifice your most valuable compounding years
- The FTC does not require retirement opportunity cost disclosure at DMP enrollment — the calculation is not legally mandated
- 41% of households aged 55–64 have zero retirement savings (GAO, 2015); low-wealth older adults die 9 years earlier than high-wealth ones (NCOA, 2025)
The Bottom Line
A 35-year-old who pauses 401(k) contributions during a 5-year DMP loses approximately $247,000 in retirement savings at age 65 — a cost no credit counselor is required to disclose and the industry never discusses. Chapter 7 bankruptcy discharges the same debt in approximately 90 days, producing a retirement opportunity cost of approximately $10,700. Your 401(k), 403(b), and other ERISA-qualified retirement accounts are fully protected in bankruptcy with no dollar cap (Supreme Court, 1992), so the choice is not between protecting retirement and filing bankruptcy — it is between a $247,000 retirement loss and a $10,700 one for identical starting debt — and Chapter 7 costs only about $2,500 out of pocket to file (often on a payment plan), while the DMP’s retirement loss is the part nobody puts on the brochure. The compounding math is irreversible: early contributions are worth 5.7 times more than late ones, and no future catch-up can recover the compound growth from years missed. Run this calculation before enrolling in any multi-year debt repayment program — you can use the retirement opportunity cost calculator here.
Part of the Credit Counseling Hub: This post is one piece of my complete Credit Counseling: The Complete Guide — what a DMP costs, who it helps, the agency financial stability risk, and how to verify any agency before enrolling.
Frequently Asked Questions
Does bankruptcy protect retirement accounts?
Yes, completely — in most cases. ERISA-qualified retirement accounts (401(k), 403(b), pension plans) are excluded from the bankruptcy estate with no dollar cap, by Supreme Court ruling in Patterson v. Shumate (504 U.S. 753, 1992) and 11 U.S.C. § 541. IRAs are protected up to $1,711,975 per person under 11 U.S.C. § 522(n), adjusted for inflation every three years (updated April 2025). Choosing a DMP over bankruptcy does not provide any additional protection for retirement accounts — they are equally protected in both scenarios.
What is the retirement opportunity cost of a debt management plan?
The retirement opportunity cost is the compound growth on retirement contributions you could not make during the DMP program. For a 35-year-old forgoing $400/month in employee contributions plus $200/month employer match for 5 years at 7% annual return: approximately $247,374 in lost retirement savings at age 65. At 10% return (historical nominal S&P average), the figure rises substantially. The exact number depends on your age, contribution amount, employer match, and assumed return rate.
Why don’t credit counselors disclose the retirement opportunity cost?
The FTC’s Telemarketing Sales Rule requires disclosure of program costs, length, and consequences of non-payment. It does not require the retirement opportunity cost calculation. Credit counseling agencies are not legally required to show you what 5 years of forgoing retirement contributions — and employer match — will cost you at age 65. This is a regulatory gap, not necessarily a deliberate concealment. But the effect is the same: consumers make enrollment decisions without this number visible.
How does the DMP retirement cost compare to the debt being paid off?
In many cases, the retirement opportunity cost exceeds the original debt. A person with $30,000 in credit card debt who completes a 5-year DMP loses approximately $247,000 in future retirement savings (at 7%, age 35). Chapter 7 bankruptcy would have discharged the same $30,000 in approximately 90 days with approximately $10,700 in retirement opportunity cost. The “responsible” path cost nearly 8x more in retirement savings than the “shameful” one.
Should I never use a debt management plan?
Not “never” — but make the decision with the full math visible. DMPs work for people who cannot qualify for bankruptcy, who have specific debt types that suit the program, and who have the income stability and discipline to complete a multi-year program. The historical completion rate is 21–26%. Before enrolling, run the retirement opportunity cost calculation for your specific situation. Compare it to the Chapter 7 option with a bankruptcy attorney’s free consultation. Make the decision with both numbers in front of you — not just the monthly payment and program length.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



