

Part of a Research Series: This post is part of Why Financial Education Fails: The Research on Money Psychology and Behavior — a complete collection of research on money psychology and financial behavior.
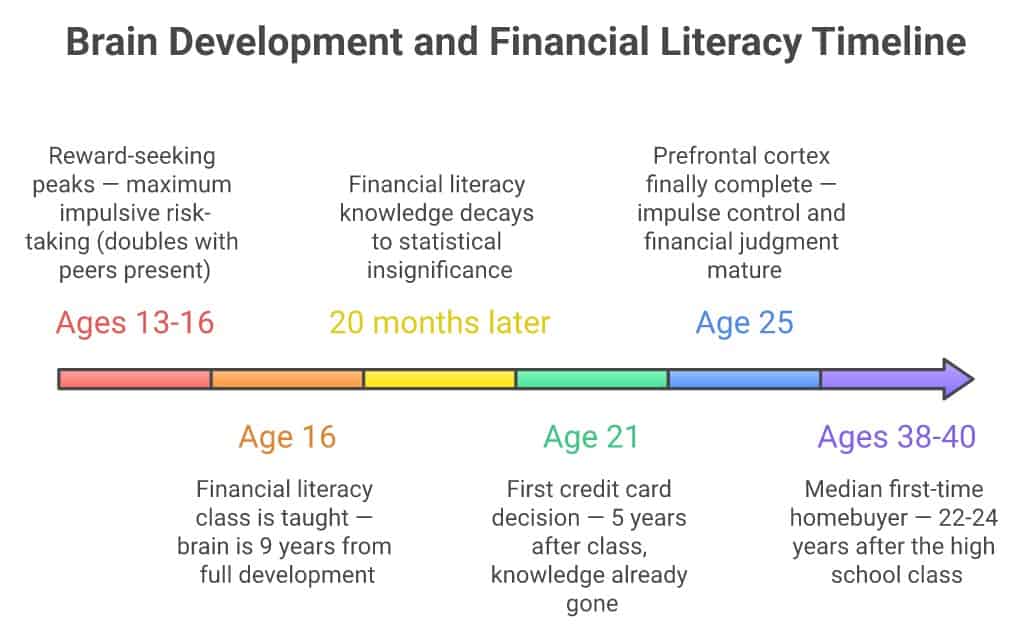
Quick Answer: Financial literacy education delivered in high school reaches students during the neurological window of peak reward-seeking and minimum impulse control. The prefrontal cortex — the brain region governing financial decision-making, impulse control, and emotional regulation — does not complete development until approximately age 25, according to a 2013 study in Neuropsychiatric Disease and Treatment. Teaching financial skills at 16 means the knowledge decays (it fades to statistical insignificance within 20 months) before the brain is structurally capable of applying it. First major financial decisions now occur between ages 21 (first credit card) and 38–40 (first home purchase) — years to decades after the classroom.
Expert Context: I founded Myvesta (formerly Debt Counselors of America) in 1994 and ran it until 2006, counseling thousands of debt clients through a team that included staff psychologists. Our 2001 clinical research using the validated CES-D depression scale found that 49.3% of 136 people seeking debt help screened positive for depression symptoms, with 39.7% in the severe range. (I long stated this as versus 9.5% in the general population; that comparison was wrong and is corrected here.) Those clients were adults with fully mature brains. If emotional dysregulation prevents adults from applying financial knowledge they already possess, consider what happens when we deliver that same knowledge to teenagers whose emotional regulation systems are neurologically incomplete. I was invited to the UK Parliament to discuss financial literacy. My conclusion then is the same as the neuroscience now confirms: we have the subject right and the timing catastrophically wrong.
Twenty-six states now mandate financial literacy education in high school. The research on whether it changes behavior is already damning — a meta-analysis of 201 studies found it explains only 0.1% of what people actually do with money. But there is a second problem layered inside the first, and it is more fundamental: we are delivering financial education to the one group of humans neurologically least equipped to apply it.
The teenage brain is not a smaller adult brain. It is a structurally different brain at a specific developmental stage — one in which the reward-seeking system operates at full power while the system responsible for impulse control, risk assessment, and future-oriented planning is still under construction. That system is the prefrontal cortex. It does not finish building until approximately age 25.
Every significant financial decision — buying versus renting, taking on student loans, opening a credit card, saving for retirement — is processed through the prefrontal cortex. The brain supposed to handle those decisions is the same brain we are trying to educate in a classroom nine years before it reaches structural completion.
About This Research
This analysis synthesizes findings from 15 primary sources including peer-reviewed neuroscience studies in Neuropsychiatric Disease and Treatment, Developmental Review, and the Annals of the New York Academy of Sciences; Federal Reserve research on consumer credit entry ages and financial education; the landmark Fernandes, Lynch, and Netemeyer meta-analysis in Management Science; a 2019 World Bank meta-analysis on financial education timing; and NBER research on financial literacy among young adults. All statistics are linked to their original sources below.
Key Terms Defined
Prefrontal cortex (PFC): The frontal region of the brain governing executive functions — impulse control, risk assessment, long-term planning, delay discounting, and emotional regulation. This is the brain’s financial decision-making center. Source: Arain et al., Neuropsychiatric Disease and Treatment, 2013.
Delay discounting: The tendency to assign less value to future rewards compared to immediate ones — the neurological mechanism behind impulsive spending and undersaving. Adolescents show significantly higher delay discounting rates than adults, driven by PFC immaturity. Source: Hartley and Somerville, Current Opinion in Behavioral Sciences, 2015.
Dual systems model: A framework describing adolescent decision-making as driven by two systems maturing at different rates — the socioemotional system (reward-seeking, matures early) and the cognitive control system (impulse regulation, matures in the mid-20s). Source: Steinberg, Developmental Review, 2008.
Just-in-time financial education: Financial instruction delivered at or near the actual moment of a financial decision, rather than years in advance. Evidence shows this approach produces significantly better behavioral outcomes than classroom instruction. Source: World Bank, 2019.
Finding 1: The Prefrontal Cortex — the Brain’s Financial Decision Center — Is Not Complete Until Age 25
In 2013, Arain and colleagues published a comprehensive review in Neuropsychiatric Disease and Treatment confirming what neuroscientists had been accumulating evidence for over a decade: “The brain undergoes a ‘rewiring’ process that is not complete until approximately 25 years of age.” The prefrontal cortex — one of the last brain regions to reach maturation — governs the exact functions financial decisions require: impulse control, risk assessment, emotional regulation, long-term planning, and delayed gratification.
The National Institute of Mental Health states it plainly: “The brain finishes developing and maturing in the mid-to-late 20s.” The frontal region, which handles “skills like planning, prioritizing, and making good decisions,” is one of the last to mature. Until it does, the American Academy of Child and Adolescent Psychiatry notes that teen decision-making is “guided more by the emotional and reactive amygdala and less by the thoughtful, logical frontal cortex.”
A student receiving financial literacy instruction at age 16 has nine years of brain development remaining in the specific systems that financial decisions depend on. Basic intellectual abilities — comprehension, reasoning — reach adult levels around age 16. But psychosocial maturity — impulse control, future orientation, resistance to peer influence in financial situations — continues developing into the mid-20s.
Common Claim: “Teenagers are smart enough to understand financial concepts, so the timing of financial literacy education is fine.”
What the Research Shows: Understanding a financial concept and being neurologically capable of applying it under real-world emotional conditions are entirely different cognitive functions. Steinberg’s research in Developmental Review found that basic intellectual abilities reach adult levels around age 16 — but psychosocial maturity, which governs actual financial behavior in emotionally charged situations, does not complete until the mid-20s. Knowing what compound interest is and resisting the emotional pull of immediate spending are controlled by different neural systems that mature nearly a decade apart.
Finding 2: Adolescent Brains Are Calibrated for Maximum Risk-Taking During the Financial Education Window
Laurence Steinberg of Temple University published a landmark analysis in Developmental Review in 2008 documenting the dual systems model of adolescent risk-taking. The findings apply directly to financial behavior.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Reward sensitivity — the drive toward immediate pleasure and novel stimulation — peaks between ages 13 and 16. Cognitive control — the capacity to evaluate risk, defer gratification, and override emotional impulses — increases gradually and does not complete until the mid-20s. These two systems do not mature together. The result is what Steinberg calls a “developmental asynchrony”: heightened vulnerability to impulsive decisions during the exact years we deliver financial literacy instruction.
Steinberg’s peer-influence experiment makes this concrete. In a simulated driving task, adolescents (mean age 14), college-age participants (mean age 20), and adults (mean age 34) showed similar risk-taking when alone. When peers were present, risk-taking doubled among adolescents, increased 50% among the college-age group, and did not change for adults 34 and older. Financial decisions — what phone your friends carry, what car they drive, what restaurant the group picks — happen constantly in peer-influenced environments. The 16-year-old brain is structurally calibrated to override financial caution in exactly those conditions.
Hartley and Somerville’s 2015 analysis in Current Opinion in Behavioral Sciences confirmed the neurological mechanism: adolescents show exaggerated ventral striatum activity in anticipation of reward compared to both children and adults. They also show heightened delay discounting — significantly less value assigned to future financial benefits. This is not a knowledge problem. It is a developmental stage of the prefrontal-striatal circuit.
We taught thousands of adults with fully mature brains who still could not apply financial knowledge because of emotional dysregulation. The teenage brain faces the same challenge with nine fewer years of prefrontal development.— Steve Rhode
Finding 3: Financial Education Decays Before the Brain Is Ready to Use It
Even setting aside the neurological mismatch, the timing problem compounds through what Fernandes, Lynch, and Netemeyer documented in their 2014 meta-analysis of 201 studies in Management Science: financial literacy education decays. Within 20 months of instruction — regardless of how many hours were delivered — even large financial education interventions show negligible effects on actual behavior.
A student who completes a state-mandated financial literacy course at age 16 makes their first independent credit card decision at approximately age 21. That is five years after the class — past the 20-month decay window. Their first mortgage, if they follow the 2025 National Association of Realtors data showing a median first-time buyer age of 40, comes 24 years after the class. The math is unambiguous: the high school financial literacy classroom delivers a perishable product to a neurologically unready recipient at the maximum possible distance from the decisions it is supposed to inform.
Hastings, Madrian, and Skimmyhorn, writing in the Annual Review of Economics in 2013, found that Jump$tart surveys showed “surprisingly little correlation between high school students’ financial knowledge levels and whether or not they have completed a financial education class.” Cole, Paulson, and Shastry’s 2016 analysis found that state mandates requiring high school personal finance courses had “no effect on investment or credit management outcomes.”
There is a conflicting finding worth acknowledging directly. Brown and colleagues’ 2016 Federal Reserve analysis found that state financial literacy mandates did improve credit scores and lower delinquency rates — but only “for those up to age 29.” This is the most optimistic finding in the literature. It is also, tellingly, the age at which the prefrontal cortex is completing its final stages of development. Even the evidence that works only works when the brain finally catches up.
Common Claim: “Even if teenagers don’t use financial skills immediately, an early foundation helps in the long run.”
What the Research Shows: Fernandes et al. (2014) showed that financial education loses its statistical significance within 20 months regardless of hours invested. A “foundation” built at age 16 and first applied at age 21 is a foundation that has already crumbled. The World Bank’s 2019 meta-analysis found that teachable-moment delivery — at the actual decision point — produces effects 48% larger than advance classroom instruction precisely because it eliminates the decay window entirely.
Finding 4: The Emotional Regulation System That Controls Financial Behavior Is Still Under Construction in Teenagers
The previous post in this series established that financial behavior is driven far more by emotional and personality factors than by knowledge — Boston Federal Reserve research showed 16 of 20 Big Five personality traits correlate with financial outcomes, while formal financial education explains only 0.1% of behavioral variance. That finding becomes more significant when combined with adolescent neuroscience.
The emotional regulation system — specifically the circuit connecting the amygdala (emotional reactivity) and the prefrontal cortex (emotional control) — undergoes a qualitative shift during adolescence. Neuroscience research published in Current Opinion in Behavioral Sciences found that “positive amygdala-prefrontal connectivity in early childhood switches to negative functional connectivity during the transition to adolescence.” In plain terms: the relationship between emotional experience and emotional control becomes less stable as children enter the teen years. The amygdala grows in volume throughout adolescence. The PFC connectivity that would regulate it lags behind by nearly a decade.
This is the same biological substrate I saw failing in adult debt clients at Myvesta. Our 2001 research found that 49.3% of people seeking debt help screened positive for depression symptoms. Debt and emotional dysregulation are not separate problems. They are the same problem expressed through different systems. We saw this in adults with mature prefrontal cortices. The teenage brain, with an amygdala operating at full capacity and a PFC still years from completion, faces a structurally amplified version of the same challenge.
Finding 5: The Research-Supported Alternative Is Decision-Point Education Paired with Money Personality Assessment
There is an evidence-based alternative to the classroom model. The 2019 World Bank meta-analysis on financial education timing found that “offering financial education at a teachable moment increases effect sizes by 0.079 standard deviation units” — translating to effects roughly 48% larger than unconditional classroom instruction. The teachable moment is the actual decision point: getting a first credit card, enrolling in a retirement plan, taking out a student loan, buying a first car.
Federal Reserve Chairman Ben Bernanke stated it directly in a 2012 speech on financial education: “Relevant, accurate, and reliable financial information must be readily available to consumers at the time they are making their decisions.” The CFPB’s own pedagogical framework identifies sound financial decisions as those best supported when information is provided “at critical teachable moments, such as when a consumer is financing education, buying a car, starting a family, purchasing a house, or planning for retirement.”
None of those moments occur in high school. None occur within 20 months of when the class ends. And none occur before the prefrontal cortex has completed the structural development required to handle them without the neurological disadvantages of adolescence.
Hastings, Madrian, and Skimmyhorn (2013) showed that automatic 401(k) enrollment increased retirement savings participation more than any financial education program. Structural design — default enrollment, spending friction, savings automation — compensates for the PFC development gap more effectively than information delivery alone. Romer’s 2010 research in Developmental Psychobiology noted that “intensive training focused on executive functioning and self-regulation skills” — not knowledge transfer — shows the most promise for improving adolescent decision-making outcomes.
At Myvesta, we did not rely on what clients had learned in school. We met them at the moment their financial crisis was real — with staff psychologists, credit counselors, and financial mediators. That is just-in-time education by necessity. The research now confirms it is the right approach by design. The second layer is understanding money personality: knowing whether you are wired toward spending, security, status, or avoidance changes how financial skills need to be taught and applied. Take the Money Personality Quiz to identify your financial behavioral patterns — a foundation that does not decay the way classroom knowledge does.
Free Tool — Money Personality Quiz: Your spending habits are as individual as your debt. The free Money Personality Quiz identifies your money type — and why standard budget advice probably isn't working for you. Discover Your Type →
What This Means If You Have a Teenager — or If You Were One
This research does not argue that teenagers should be kept in the dark about money. It argues that the format, timing, and delivery of financial education must match how the brain actually develops and when financial decisions actually occur.
- Start with money personality, not money rules. Understanding your money personality reveals the emotional and behavioral patterns that will drive financial decisions long before formal financial skills can be applied. Personality is more stable than knowledge and does not decay within 20 months.
- Teach at the decision point, not years before it. When a teenager is about to open their first bank account, that is the moment for deposit and overdraft concepts. When they take their first job, that is the moment for withholding explanation — not in a classroom two years earlier with no paycheck in hand.
- Recognize that emotional dysregulation is the actual mechanism of financial failure. The research across both posts in this series points to the same conclusion: financial behavior is emotional before it is rational. Building emotional awareness — how your money personality interacts with stress, peer pressure, and immediate reward — is more protective than financial literacy coursework alone.
- Build structural guardrails rather than relying on willpower. Automatic savings, spending friction, and accountability structures compensate for incomplete prefrontal control more effectively than information. This applies to teenagers and to adults navigating high-stress financial decisions.
- If you took a high school financial literacy class, the knowledge has almost certainly faded. What has not faded is your money personality. Understanding it now, with a mature prefrontal cortex, is the research-supported path to better financial decisions — not a refresher on the curriculum you completed at 16.
Key Takeaways
- The prefrontal cortex — governing impulse control, delay discounting, and future-oriented financial decisions — does not complete development until approximately age 25 (Arain et al., 2013), while financial literacy is mandated in 26 states for high school students ages 14–18, creating a 7–11 year readiness gap.
- Adolescent reward-seeking peaks at ages 13–16, and peer presence doubles financial risk-taking in teenagers while having no effect on adults over 34 (Steinberg, 2008) — the neurological peak of impulsive decision-making coincides exactly with the classroom delivery window.
- Financial literacy education loses its statistical impact within 20 months regardless of instruction hours (Fernandes et al., 2014), while first major financial decisions now occur between ages 21 (first credit card) and 38–40 (first home purchase).
- Financial education delivered at actual decision points produces effects 48% larger than classroom instruction (World Bank, 2019) — because it eliminates both the knowledge-decay window and the developmental readiness gap simultaneously.
- The emotional regulation system that drives financial behavior (amygdala-PFC circuitry) is the same system still under construction in teenagers — making classroom delivery of financial skills structurally mismatched to the recipient at a neurological level, not merely a logistical one.
The Bottom Line
Financial literacy education delivered in high school targets students at their neurological worst for financial decision-making: the prefrontal cortex — governing impulse control, delay discounting, and future-oriented planning — does not complete development until approximately age 25 (Arain et al., Neuropsychiatric Disease and Treatment, 2013), while adolescent reward-seeking peaks at ages 13–16 and peer presence doubles financial risk-taking in teenagers but not in adults (Steinberg, Developmental Review, 2008). The knowledge taught in that classroom decays to statistical insignificance within 20 months regardless of instruction hours (Fernandes, Lynch, Netemeyer, Management Science, 2014) — years before the first credit card at age 21 and over two decades before the median first-time home purchase at age 38–40 (National Association of Realtors, 2025). The World Bank’s 2019 meta-analysis found that delivering financial education at the actual moment of decision produces effects 48% larger than advance classroom instruction. The research-supported path is not more high school financial literacy mandates — it is decision-point education paired with money personality assessment, delivered when adults have both the mature brain to apply it and the immediate decision that demands it.
Frequently Asked Questions
Why do states keep mandating financial literacy in high school if research shows it doesn’t produce lasting behavior change?
Because the intuition — teach young people financial skills before they make mistakes — is reasonable even though the neurological and behavioral evidence does not support the timing. High school represents the last point where students are a captive audience, making it administratively convenient. Hastings, Madrian, and Skimmyhorn, writing in the Annual Review of Economics, identified the core dilemma: “How do we deliver financial education to adults before they make financial mistakes when we don’t have a captive audience?” The answer the research supports is decision-point delivery — but building that infrastructure around real-world financial moments is harder than adding a class to the existing school curriculum.
At what age is the brain actually ready to learn and apply financial skills effectively?
The research points to the mid-20s as when the prefrontal cortex completes the structural development required for consistent adult-level financial decision-making. However, Romer’s 2010 analysis in Developmental Psychobiology notes that experience and learning can compensate for brain maturation limitations — meaning financial skill-building is most effective when it coincides with actual financial experience, not when it is delivered years in advance. Financial education at ages 21–23 — when first credit decisions, first employment, and first student loan repayment occur simultaneously — is more neurologically appropriate than instruction at ages 14–18.
What is delay discounting and why does it matter for financial behavior in teenagers?
Delay discounting is the tendency to assign less value to future rewards compared to immediate ones — the neurological mechanism behind “I’ll save for retirement later” and “I’ll pay off the card next month.” Hartley and Somerville’s 2015 research in Current Opinion in Behavioral Sciences found that “discount rates decline throughout adolescence and asymptote in early adulthood” — meaning teenagers have significantly higher delay discounting rates than adults. Klein, Collins, and Luciana’s 2022 longitudinal study in Cognitive Psychology confirmed that delay discounting behavior does not stabilize at adult levels until late adolescence at the earliest. This is not a character flaw. It is a developmental stage of the prefrontal-striatal circuit that drives financial patience.
If not high school, when should financial literacy education actually be delivered?
The research converges on decision-point delivery as the most effective model. The World Bank’s 2019 meta-analysis found 48% larger behavioral effects when financial education coincides with an actual financial decision. Federal Reserve Chairman Bernanke endorsed this approach in 2012, identifying five decision stages — earning, spending, saving, borrowing, protecting — each better addressed with targeted instruction when the decision is live rather than years in advance. For teenagers, the most productive financial education is experiential: first bank account at the moment of opening, first paycheck at the moment of earning, first credit decision at the moment of application — with a financially knowledgeable mentor present, not a curriculum completed two years earlier.
Does knowing your money personality help even if your prefrontal cortex isn’t fully developed yet?
Yes — and this is where the neuroscience intersects with the money personality research from the first post in this series. Boston Federal Reserve research showed that Big Five personality traits predict financial outcomes independently of knowledge levels. Unlike financial literacy knowledge (which decays within 20 months) or prefrontal cortex development (which takes until age 25), money personality patterns are identifiable earlier and more stable than classroom learning. Understanding whether a teenager has a spending-dominant or security-dominant money personality helps design the environmental structure — automatic savings, spending friction, peer accountability — that compensates for incomplete prefrontal control during the years when that control is still developing. Take the Money Personality Quiz to identify the behavioral patterns that shape your financial decisions.
Sources and Methodology
This post draws on the following primary sources:
- Arain M. et al. — “Maturation of the Adolescent Brain” (Neuropsychiatric Disease and Treatment, 2013) — Prefrontal cortex maturation timeline and governed functions
- National Institute of Mental Health — “The Teen Brain: 7 Things to Know” (2023) — Brain development stages and frontal cortex maturation
- Casey BJ, Jones RM, Hare TA — “The Adolescent Brain” (Annals of the New York Academy of Sciences, 2008) — PFC structural development and reward processing in adolescence
- Steinberg L. — “A Social Neuroscience Perspective on Adolescent Risk-Taking” (Developmental Review, 2008) — Dual systems model, peer influence doubling, reward-control asynchrony
- Hartley CA, Somerville LH — “The Neuroscience of Adolescent Decision-Making” (Current Opinion in Behavioral Sciences, 2015) — Delay discounting and reward reactivity trajectories
- Romer D. — “Adolescent Risk Taking, Impulsivity, and Brain Development” (Developmental Psychobiology, 2010) — Impulsivity types and executive function training
- Klein SD, Collins PF, Luciana M. — “Developmental Trajectories of Delay Discounting” (Cognitive Psychology, 2022) — Delay discounting stabilization timeline in longitudinal data
- Fernandes D., Lynch JG, Netemeyer RG — “Financial Literacy, Financial Education, and Downstream Financial Behaviors” (Management Science, 2014) — Meta-analysis of 201 studies; 0.1% behavioral variance; 20-month decay
- Hastings JS, Madrian BC, Skimmyhorn WL — “Financial Literacy, Financial Education and Economic Outcomes” (Annual Review of Economics, 2013) — Mixed evidence review; Jump$tart survey findings; automatic enrollment comparison
- Cole S., Paulson A., Shastry GK — “High School Curriculum and Financial Outcomes” (Journal of Human Resources, 2016) — State-mandated personal finance courses: no measurable effect on investment or credit outcomes
- Brown M. et al. — “State Mandated Financial Education and the Credit Behavior of Young Adults” (Federal Reserve, 2016) — Conflicting finding: improved credit scores for those up to age 29
- World Bank — “Does Financial Education Impact Financial Literacy and Financial Behavior, and If So, When?” (2019) — Teachable-moment delivery: 48% larger behavioral effect
- Bernanke BS — Speech on Financial Education, Federal Reserve Board (August 7, 2012) — Decision-point delivery endorsement; lifelong financial competency framework
- Federal Reserve Board — “Does the Age at Which a Consumer Gets Their First Credit Matter?” FEDS Notes (2021) — First credit entry ages; 70% of consumers enter credit before age 30; peak entry ages 18–20
- National Association of REALTORS — 2025 Profile of Home Buyers and Sellers (2025) — Median first-time homebuyer age 40; 24-year gap from high school financial literacy class
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



