
Quick Answer: A Lloyds Banking Group study found that 56% of UK adults — roughly 28.8 million people — now use AI tools for financial advice, with one in three consulting AI weekly. That scale should concern anyone who understands how these models are built. AI systems are only as good as their training data, and the internet they learned from is saturated with cultural assumptions about debt and money that are presented as facts. They are not facts. They are cultural myths — and now they’re being recited with algorithmic confidence to millions of people who have no idea where those beliefs came from.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Expert Context: I ran a credit counseling organization from 1994 to 2006. I watched from inside as industry marketing shaped what “responsible debt advice” looked like — credit counseling was the wholesome option, bankruptcy was shameful, and paying every dollar back was presented as a moral obligation. Those messages made it into countless articles, guidance documents, and online forums. That’s exactly the kind of content that trained the AI systems now advising tens of millions of people. The myths didn’t start with AI — AI just automated them.
Table of Contents
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
More than half of British adults now turn to AI for financial guidance — and a quarter of them are consulting it specifically for debt management strategies. The problem isn’t that AI is giving bad math. It’s that AI learned its beliefs about debt from the same cultural narratives that have been manipulating debtors for decades.
Key Terms Defined
Training data: The text corpus — articles, books, websites, forums — that AI language models learn from. The model doesn’t “know” facts; it learns statistical patterns about which words and ideas appear together. If the internet associates “bankruptcy” with “shame” and “failure” more often than “relief” and “fresh start,” the AI inherits that association.
Hallucination vs. bias: Hallucination is when AI invents facts that aren’t true. Bias is subtler — it’s when AI accurately reflects widespread beliefs that happen to be wrong, or incomplete, or shaped by industry interests rather than evidence. Bias from training data is harder to spot because the output isn’t obviously wrong; it just repeats assumptions you’ve heard a thousand times before.
LLM (Large Language Model): The technology behind ChatGPT, Copilot, Gemini, and similar AI tools. These systems are trained on enormous datasets and learn to produce text that resembles what they were trained on — including cultural attitudes, moral frameworks, and conventional wisdom, whether accurate or not.
The Lloyds Study and What It Doesn’t Say
The Lloyds Banking Group’s 2025 Consumer Digital Index — the UK’s largest annual study of digital and financial behavior — surveyed roughly 5,000 adults and found that AI has moved from novelty to primary resource faster than almost anyone predicted. According to Lloyds, users estimate AI-generated financial insights save them an average of £399 per year. ChatGPT is the most popular platform, used by 60% of AI financial advice seekers.
Coverage of this study has focused on the adoption numbers and the efficiency gains. What it hasn’t focused on is the foundation those answers rest on — and what’s embedded in that foundation.
AI doesn’t reason from first principles. It pattern-matches from text. When millions of articles, forum posts, and financial guidance documents present the same assumptions as established facts, those assumptions get encoded into the model. The output feels authoritative because it’s grammatically confident, internally consistent, and structurally similar to professional advice. None of that makes it right. And the problem extends beyond debt advice — AI chatbots are giving dangerously wrong Social Security and retirement advice too, with errors that can cost retirees $50,000 to $100,000 over a lifetime.
The Specific Myths I’ve Documented in AI Debt Advice
I’ve been testing how AI tools respond to debt questions since these systems became widely available, and I’ve documented a consistent pattern. Here are the cultural assumptions I’ve watched these models repeat as if they were financial facts:
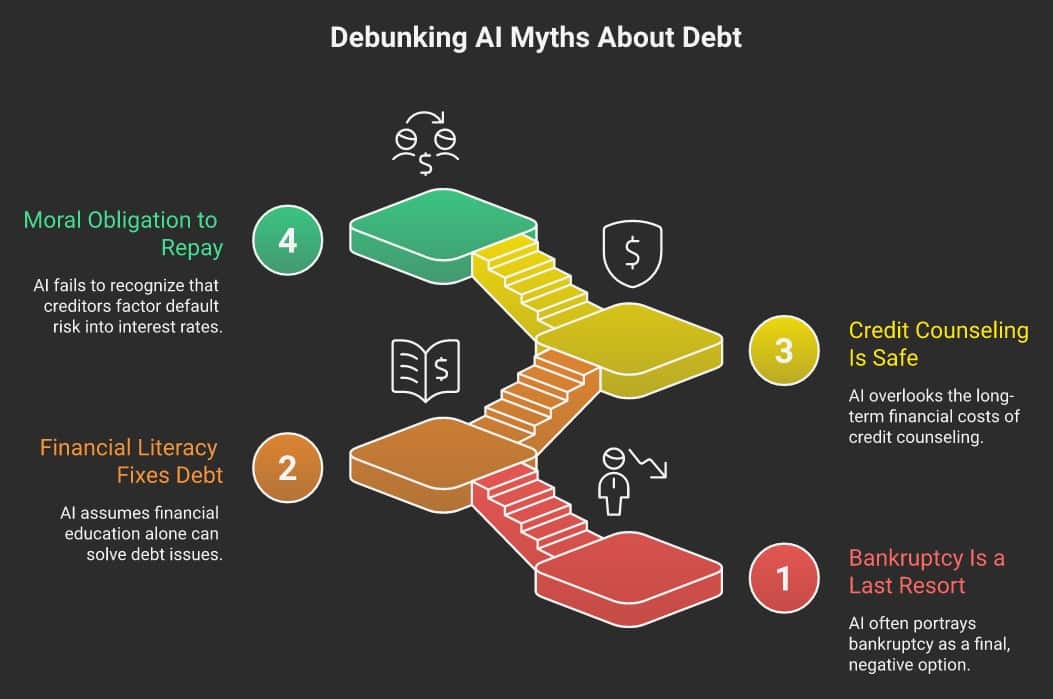
Myth 1: Bankruptcy Is a Last Resort — and a Moral Failure
What AI typically says: “Bankruptcy should only be considered as a last resort when all other options have been exhausted. It carries serious long-term consequences for your credit and financial reputation.”
What the research actually shows: A Federal Reserve study found that bankruptcy filers are better off financially within two to three years than comparable people who tried to avoid it. Bankruptcy is the only debt solution that protects retirement accounts, resolves debt immediately, and allows credit recovery to begin immediately. Framing it as a “moral failure” or “last resort” isn’t advice — it’s cultural shame dressed up as financial guidance. I filed bankruptcy in 1990 and rebuilt everything. It was the best financial decision I’ve ever made.
Myth 2: Financial Literacy Education Is the Solution
What AI typically says: “Improving your financial literacy can help you make better decisions about debt management, budgeting, and long-term planning.”
What the research actually shows: Multiple meta-analyses have found that financial literacy programs have minimal lasting impact on financial behavior. My own post on why financial education fails cites the research directly — behavior is driven by emotion, circumstance, and structural factors, not information deficits. People in debt usually know what they should do. The barrier is rarely knowledge. AI confidently prescribing financial literacy education as a debt solution is not evidence-based advice.
Myth 3: Credit Counseling Is the Wholesome, Safe Option
What AI typically says: “Nonprofit credit counseling agencies offer a safe, regulated path to debt relief through debt management plans, with professional counselors helping you develop a budget and negotiate with creditors.”
What the research actually shows: I founded a credit counseling organization. I know how the industry markets itself, and I know what happens when sales pressure meets nonprofit status. Credit counseling debt management plans (DMPs) are a legitimate option for some people — but the hidden cost is enormous. A five-year DMP typically costs a person around $400,000 in lost retirement compounding if they’re in their 30s or 40s. That opportunity cost is never mentioned in the AI’s recommendation because it’s never mentioned in the industry marketing that trained it. For many people, a Chapter 7 bankruptcy is faster, cheaper, and better for their long-term financial future — and AI almost never presents that comparison.
Myth 4: You Have a Moral Obligation to Repay Every Dollar
What AI typically says: “While bankruptcy is a legal option, many financial advisors recommend exploring every avenue to repay your debts before considering it, as honoring your commitments is important for your financial reputation.”
What the reality is: Creditors don’t apply moral frameworks to risk. They calculate expected default rates into their interest charges before you sign anything. When they sell your debt to a collector for 3 cents on the dollar, they’re not making a moral judgment — they’re executing a business decision. The moral framing of debt repayment is a manipulation tool, not a principle. As I’ve written for nearly 30 years: debt is math, not morality. AI has been trained on decades of shame-laden content that presents repayment as virtue. It has not been trained on the business logic of creditors, which is a completely different calculation.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Why This Happens — and Why It Matters at Scale
The Financial Planning Association’s research journal documented AI’s specific failures in financial reasoning: arithmetic errors, misunderstanding of the time value of money, and a pattern of producing “authoritative responses that were coherent and grammatically correct” while being fundamentally wrong. That’s the surface-level problem. The deeper problem is cultural.
The internet that trained these models contains decades of content shaped by:
– Debt industry marketing (which profits from keeping people in long-term plans)
– Cultural narratives about debt as moral failing
– Financial media that treats conventional wisdom as settled science
– Advice that was never tested against actual outcomes
None of that content is flagged as “industry bias” or “culturally loaded.” It’s just text on the internet, indistinguishable in form from evidence-based research. When an LLM learns from it, it learns the attitudes embedded in it — and then recites those attitudes with the confidence of a system that has processed millions of sources.
At the scale the Lloyds study documents — 28.8 million people, one in three consulting weekly — that’s not a quirk. That’s a delivery mechanism for culturally encoded myths operating at industrial scale. And unlike a human financial counselor, the AI doesn’t disclose its conflicts of interest, because it doesn’t know it has any.
What I’d Want AI to Say Instead
If an AI were trained on the actual research literature — on the Federal Reserve bankruptcy outcome data, on the behavioral economics of debt, on the hidden costs of DMPs, on what creditor behavior actually looks like — it would give fundamentally different advice. It might say:
- Bankruptcy isn’t shameful — it’s a legal financial tool with measurable outcomes that often outperform alternatives
- Credit counseling is one option — with real costs that need to be calculated, not just assumed to be “the safe choice”
- Financial literacy isn’t the answer to structural debt problems caused by wage gaps, medical costs, or life events
- Your creditors are making business decisions — you’re allowed to make them too, without moral judgment attached
- The math on bankruptcy is often better than five years of grinding through a DMP
That’s the advice I’ve been giving for 30 years, backed by research. It doesn’t appear in most AI responses about debt because it wasn’t the dominant narrative in the content those systems learned from.
If you want personalized guidance that accounts for your specific situation rather than a cultural default, start with the Find Your Path quiz — it’s built around actual options, not assumptions about which one is “wholesome.”
We Built a Different Kind of AI Answer
While researching this post, I want to be transparent about something: I built my own AI-powered chat tool — Ask Steve — specifically because I saw this problem happening. The cultural myths above aren’t hard to find in general-purpose AI responses. I’ve tested them myself.
The difference with Ask Steve is what it was trained on: more than 30 years of my front-line, real-world experience helping people with debt. Not blog posts that echo industry marketing. Not self-help books built on shame-based frameworks. My actual research, my documented insights from thousands of cases, and my contrarian evidence-based positions — including the ones general AI gets wrong.
It won’t recommend credit counseling because it sounds responsible. It won’t call bankruptcy a last resort. It won’t tell you to “improve your financial literacy” as a solution to structural debt. It gives you the same advice I’d give you directly — because that’s what it was built on.
Key Takeaways
- 56% of UK adults (28.8 million people) now use AI for financial advice; 26% use it specifically for debt management guidance
- AI tools are trained on internet text that encodes cultural myths about debt as facts — bankruptcy = moral failure, credit counseling = safe, financial literacy = solution
- None of these assumptions are well-supported by evidence; several are directly contradicted by research
- AI doesn’t disclose the cultural bias in its training data because it doesn’t know the bias is there
- At scale, AI financial advice is an industrial-strength delivery mechanism for industry narratives that haven’t been questioned in the way they should be
The Bottom Line
The Lloyds study confirms what I’ve been watching happen gradually: AI has become the first-call financial advisor for tens of millions of people. That would be good news if AI had learned from evidence-based research. Instead, it learned from the same cultural narratives that the debt industry has been distributing for decades — bankruptcy is shameful, credit counseling is virtuous, paying every dollar back is a moral obligation. Those are industry talking points dressed up as universal truths, and now an AI is reciting them with algorithmic confidence to 28 million people who have no way of knowing where those beliefs came from. The antidote isn’t better AI — it’s knowing what questions to push back on, and understanding that the most confident-sounding answer isn’t always the one rooted in evidence.
Frequently Asked Questions
Is AI financial advice safe to follow for debt decisions?
AI financial advice is useful for general information but carries a significant hidden risk: it reflects the cultural assumptions baked into its training data. For debt decisions, AI tools consistently underemphasize bankruptcy as a viable option, overemphasize the “wholesomeness” of credit counseling, and frame debt repayment in moral terms rather than financial ones. The Financial Planning Association’s research found AI consistently makes fundamental financial errors. For any major debt decision, consult a bankruptcy attorney (who can give you a free consultation) alongside or instead of AI advice.
Why does AI recommend credit counseling over bankruptcy so often?
Because the internet AI learned from promotes credit counseling as the “responsible” choice and treats bankruptcy as shameful — not because the evidence supports that framing. The actual research literature, including a Federal Reserve study on bankruptcy outcomes, shows bankruptcy filers do better financially than comparable people who tried to avoid it. AI hasn’t been trained on that literature at the same weight as industry marketing content.
How many people use AI for debt advice in the UK?
According to the Lloyds Banking Group 2025 Consumer Digital Index, 26% of the 28.8 million UK adults who use AI for financial matters consult it for debt management strategies — roughly 7.5 million people. One in three of total AI financial users consult it weekly or more frequently.
What cultural myths about debt has AI absorbed from its training data?
The most common ones I’ve documented: (1) bankruptcy is a moral failure or last resort, when research shows it often produces better outcomes than alternatives; (2) financial literacy programs solve debt problems, when behavioral research shows they don’t; (3) credit counseling is the safe, wholesome option, without disclosing its hidden retirement opportunity cost; and (4) you have a moral obligation to repay creditors, when creditors themselves operate on pure business logic and price your default rate into their interest charges before you ever sign anything.
What should I ask AI instead of relying on its default debt advice?
Push back on the defaults. Ask: “What does the research show about outcomes for people who file bankruptcy versus people who use debt management plans?” Ask: “What is the opportunity cost of a five-year debt management plan in lost retirement compounding?” Ask: “Are there situations where bankruptcy produces better long-term financial outcomes than paying every dollar back?” These questions force the AI to engage with the evidence rather than recite cultural defaults. You can also use my Find Your Path quiz to assess your specific situation against all available options — not just the ones that sound most virtuous.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



