

Quick Answer: No — a debt collector cannot have you arrested for not paying a civil debt. Threatening arrest to coerce payment is a violation of the FDCPA under § 807(4), which prohibits false representations of what can legally happen to you. In the United States, you cannot be jailed for failing to pay a credit card, medical bill, or personal loan. Any collector who says otherwise is either lying to scare you or running a scam — and either way, what they’re doing is illegal.
Expert Context: I’ve studied debt collector tactics since the 1990s — including as someone who was on the receiving end after my own bankruptcy in 1990. The arrest threat is one of the oldest psychological pressure tactics in collections. It works on people who don’t know their rights. Knowing what I know, if a collector said that to me, I’d laugh and call an FDCPA attorney.
I get variations of this question through the Ask Steve chat regularly — and every time I see it, it tells me the collector is either desperate, incompetent, or deliberately running a scam. None of those situations should result in you paying them a dime before you understand what’s actually going on.
The Question That Came In:
“A debt collector just called and told me they’re going to press criminal charges and have me arrested if I don’t pay by Friday. I have a couple thousand dollars on an old credit card I fell behind on. Can they actually do this? I’m terrified.”
The terror is exactly what they’re counting on. That’s how this tactic works — panic bypasses judgment, and people hand over money they don’t owe, to collectors who have no legal authority to do what they’re threatening.
Let me be direct: what this collector said is almost certainly illegal. Here’s exactly why — and what your next move should be.
Based on recent CFPB complaint data, threats of arrest or criminal prosecution are among the most commonly reported FDCPA violations. This is not a niche issue — it’s a documented pattern used by collectors who know that fear produces payment faster than anything else.
The Law Is Clear: You Cannot Be Arrested for Civil Debt
The United States abolished debtor’s prisons in the 1830s. Failing to pay a credit card, medical bill, personal loan, or most other consumer debts is a civil matter — not a criminal one. Civil debt can result in a lawsuit, a judgment, wage garnishment, or a bank levy. It cannot result in arrest or jail time.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
There is a narrow exception: if a court has ordered you to appear and you’ve ignored the order, a judge can hold you in contempt. But that’s not “arrested for not paying debt” — that’s “arrested for ignoring a court order.” It requires an actual lawsuit, a judgment, a court order, and deliberate noncompliance. No collector can trigger that with a phone call on Friday.
The Threat: “We’re going to press criminal charges and have you arrested if you don’t pay by Friday.”
The Reality: This is either a lie or a scam — and it’s illegal either way. Under FDCPA § 807(4), it is unlawful for a debt collector to represent or imply that you have committed a crime or will be subjected to arrest if you don’t pay. Collectors don’t have the power to press criminal charges. They don’t talk to prosecutors. They can’t get you arrested for unpaid credit card debt. Period.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
Two Scenarios — Both Illegal, One Much Worse
When a collector threatens arrest, one of two things is happening:
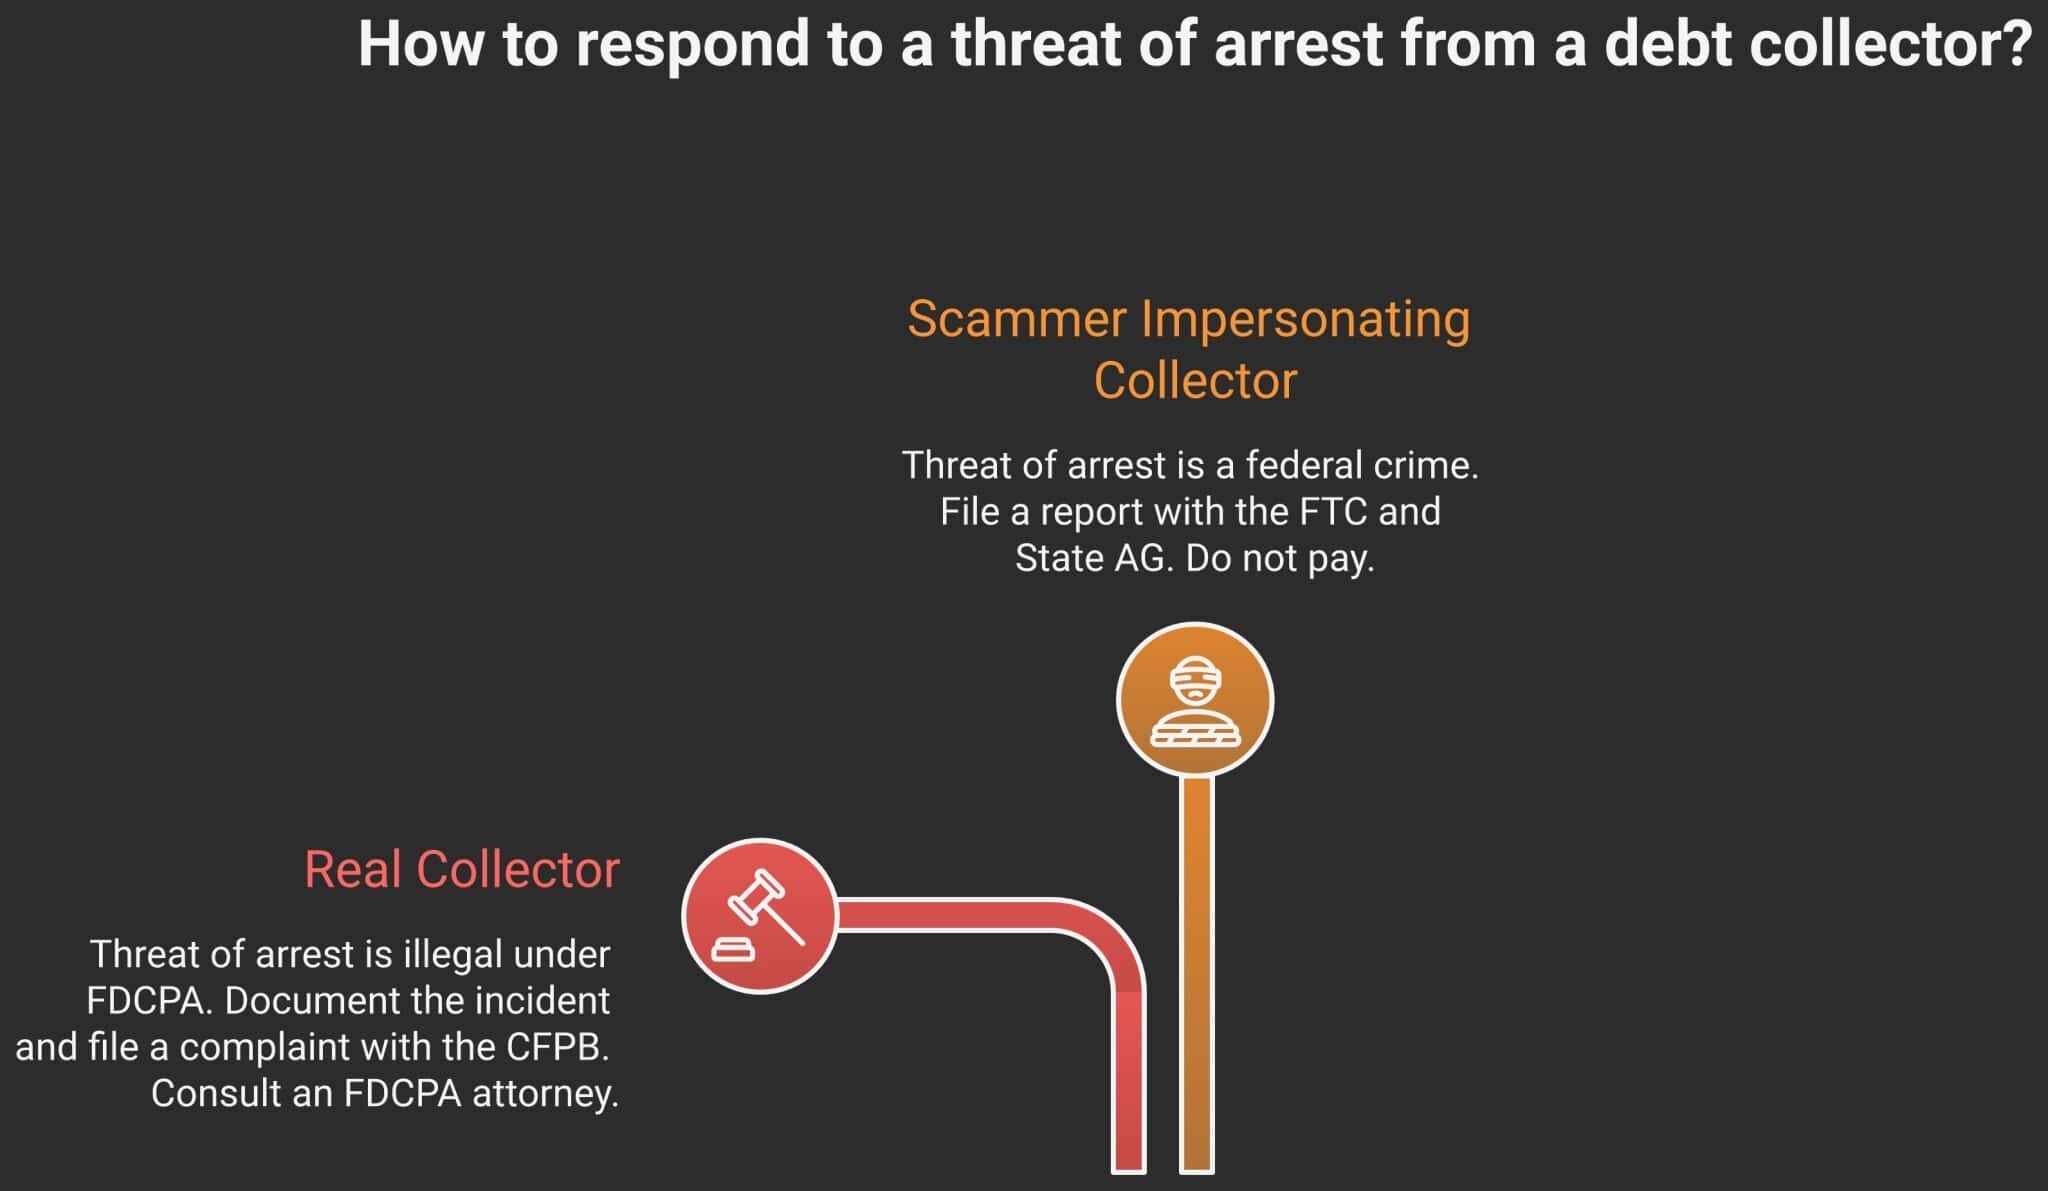
Scenario A: Legitimate Collector, Illegal Tactic
- A real debt collector who owns or services the debt
- Deliberately using false threat to pressure payment
- Violates FDCPA § 807(4) — clear civil case
- You may have a federal court claim against them
- File CFPB complaint + consult FDCPA attorney
Scenario B: Scammer Impersonating a Collector
- Fake “collector” using fear to extract immediate payment
- Often impersonates government, courts, or law enforcement
- May demand wire transfer, gift cards, or cryptocurrency
- You likely don’t owe them anything at all
- File FTC report + state AG complaint immediately
The criminal court angle — “we’ll press charges,” “the sheriff is on the way,” “you have a warrant” — is particularly associated with scammers because it creates maximum panic. Legitimate collectors, even bad ones, usually know this specific threat crosses a legal line that exposes them to lawsuits. Scammers don’t care because they’re not real companies.
My Take: This Is a Fear Tactic, and Fear Is the Product
I’ve watched the debt collection industry for decades. I know how the business works from the inside. The arrest threat exists for one reason: panic produces payment. A calm, informed person who knows their rights does not wire money to a stranger on a Friday afternoon. A frightened person who believes a deputy sheriff is coming to their home does.
The criminal court angle is specifically effective because most people have no idea that civil debt and criminal charges are completely separate systems. They’ve seen people arrested on TV. They conflate debt with crime. Collectors — legitimate and fraudulent — exploit that confusion intentionally.
Here’s what I tell people when this happens to me: laugh. Not because it’s funny, but because the laugh is the physical signal to your nervous system that you’re not actually in danger. Then document. Then act. The power in this situation is yours, not theirs — once you know that what they did is illegal.
If a collector threatens you with arrest for an unpaid credit card, don’t panic and don’t pay. Document it, report it, and call an FDCPA attorney. That threat just handed you a federal case.— Steve Rhode
What to Do Right Now
- Do not pay anything in response to the threat. Payment made under threat, especially via wire transfer, gift cards, or cryptocurrency — which scammers specifically request — is almost certainly unrecoverable. Do not act in the fear window. Wait 24 hours if you need to. No legitimate legal process happens “by Friday” over the phone.
- Write down everything immediately. Date, time, caller’s name (if given), company name (if given), exact wording of the threat, phone number. If they call again, record the call if your state allows one-party consent recording. This documentation is the foundation of any legal action you take.
- Verify whether the debt is real. If you think this might be a real debt you owe, send a written validation request to the collector by certified mail. Under FDCPA § 809, they must stop collection activity and provide verification. Do not call them back to “verify” — communicate in writing only.
- File a CFPB complaint. Go to CFPB.gov/complaint and report the threat. Include the exact wording used. This creates a federal record and may trigger a response from the company.
- File an FTC report if you suspect a scam. Report it at ReportFraud.ftc.gov. If the collector claimed to be a government agency, law enforcement, or a court officer, that’s impersonation — a separate crime on top of the FDCPA violation.
- Contact your state attorney general. Most state AGs have a consumer protection division. Threats of arrest by debt collectors are reportable in every state and many have stronger consumer protection laws than the federal FDCPA.
- Consult an FDCPA attorney. If this was a real collector making an illegal threat, you may have a federal case worth pursuing. Statutory damages up to $1,000 per violation, plus actual damages and attorney’s fees — and many FDCPA attorneys take these cases on contingency. NACA is the best starting point.
Red Flags That Indicate a Scam (Not a Real Collector):
- Demands payment via wire transfer, gift cards, Zelle, Venmo, or cryptocurrency
- Claims to be a sheriff, court officer, government agency, or law enforcement
- Refuses to provide a written validation notice or company address
- Says you must pay today or “the officer will be at your door by Friday”
- Can’t tell you the name of the original creditor
- Calls from a spoofed number that shows up as a government agency or court
No Article Replaces an Attorney Licensed in Your State: What I’ve covered here is educational — it is not legal advice. If a debt collector threatened you with arrest or criminal prosecution, you may have a federal court case under the FDCPA. An attorney can evaluate whether the specific facts give you a viable claim.
How to find a consumer law attorney who handles FDCPA cases:
- NACA — National Association of Consumer Advocates — Best starting point. Member attorneys specialize in consumer protection and many take FDCPA cases on contingency.
- Your state bar’s lawyer referral service — Search “[your state] bar association lawyer referral” for a low-cost initial consultation.
- LawHelp.org — Free and reduced-cost legal aid by state and issue.
- HelpIsHere.org — If you are a senior or have a disability, free or low-cost legal help may be available here.
Not sure if this is a real collector or a scam? That distinction matters — the response is different. Ask Steve in the chat — describe what they said, what they asked you to pay with, and whether you actually recognize the debt, and I’ll help you figure out what you’re dealing with.
Key Takeaways
- You cannot be arrested for failing to pay a credit card, medical bill, or personal loan — the U.S. has not had debtor’s prisons since the 1830s
- A debt collector who threatens arrest is violating FDCPA § 807(4), which prohibits false threats of criminal prosecution or arrest to collect a debt
- The threat may also indicate a scam — especially if they demand gift cards, wire transfers, or cryptocurrency, or claim to be law enforcement
- Do not pay anything in response to the threat. Panic is the product — slow down, document, and verify before any money moves
- File CFPB and FTC complaints, contact your state AG, and consult an FDCPA attorney — statutory damages up to $1,000 per violation apply, and many attorneys take these cases on contingency
The Bottom Line
A debt collector threatening to have you arrested for not paying a civil debt is violating the FDCPA — specifically § 807(4), which prohibits false threats of criminal prosecution. You cannot be jailed for unpaid credit cards, medical bills, or personal loans in the United States. The arrest threat is a psychological pressure tactic, and it’s either coming from a real collector breaking the law or a scammer trying to steal from you. Either way, do not pay in response to the threat, do not panic, and do not act on a Friday afternoon deadline. Document every word, file a CFPB complaint, report it to the FTC if it looks like a scam, and talk to an FDCPA attorney — what they said may have just handed you a federal case.
Free Tool — Debt Validation Letter Generator: Being contacted by a debt collector? The free Debt Validation Letter Generator creates a personalized FDCPA validation letter in seconds — forcing the collector to prove the debt is real before they can continue. Generate My Letter →
Frequently Asked Questions
Can a debt collector have me arrested for not paying a credit card bill?
No. Unpaid credit card debt is a civil matter, not a criminal one. Civil debt can result in a lawsuit and a judgment, but not arrest. A debt collector threatening arrest for unpaid credit card debt is making a false representation in violation of FDCPA § 807(4). The only way debt-related activity can result in arrest is if a judge holds you in contempt for ignoring a court order — and that requires an actual lawsuit, a judgment, a court order, and deliberate noncompliance. One real version of that court order is a debtor’s examination, where a creditor who already won a judgment can force you into court to answer questions about your money under oath — here’s what that looks like and how to handle it.
What if the collector says they’re calling from a law firm or a court?
This is a major red flag for a scam. Legitimate law firms collecting debts are still subject to the FDCPA and still cannot threaten arrest. If someone claims to be calling from a court, sheriff’s office, or government agency about unpaid debt, that is almost certainly a scam — and impersonating a government official is a federal crime separate from the FDCPA violation. Report it to the FTC at ReportFraud.ftc.gov and your state AG immediately. Do not pay anything.
Is there any situation where I could be arrested related to a debt?
There is a narrow scenario: if you’ve been sued, a court issued a judgment, a judge ordered you to appear for a debtor’s examination (to disclose your assets), and you ignored that court order — a judge could hold you in contempt of court. But this is not “arrested for debt.” This is “arrested for ignoring a court order.” It requires a full lawsuit process, a judgment, and a court-issued order that you then deliberately ignore. A collection call threatening this on Friday is not that.
Should I call the collector back to explain or negotiate after a threat like this?
No — not by phone. If you have a legitimate debt with this collector and want to address it, communicate in writing only. Send a written validation request by certified mail. That creates a paper trail, invokes your FDCPA § 809 rights, and stops collection activity until they validate. Calling them back puts you at a disadvantage — you have no record of the conversation and you may inadvertently make statements that complicate your situation.
What if I actually do owe the debt they’re calling about?
Owing a legitimate debt does not justify illegal collection tactics. Even if the debt is real, a collector threatening arrest is violating the FDCPA — and you still have rights. Send a written validation request, verify the debt is actually owed to this collector (debts are bought and sold), and if you want to resolve it, negotiate from a position of knowledge rather than fear. Owing a debt is not a reason to tolerate illegal threats — it’s a separate issue from how the collector is allowed to behave.
Know Your Rights: If a debt collector is contacting you, you have legal protections. See the complete list of FDCPA violations collectors commit most often. Use the free Debt Validation Letter Generator to demand proof of the debt, or check this collector’s complaint history with the Scam-O-Meter.
Dealing With Debt? Before you pay a collector, understand all your debt relief options — including ones the collector won’t tell you about. If the debt feels unmanageable, take the 2-minute bankruptcy quiz to see if the math favors a fresh start. Federal Reserve research shows filers recover faster than those who don’t file.



