
Quick Answer: Par Funding (Complete Business Solutions Group) was a Philadelphia merchant cash advance company that raised $547 million from more than 1,200 investors between 2011 and 2020. Its founder, Joseph LaForte, operated under the fake name “Joe Mack” to hide two prior felony convictions. All eight defendants pleaded guilty to wire fraud and related charges. LaForte was sentenced to 186 months in federal prison in March 2025. Investors are expected to recover approximately 80 cents on the dollar.
If you took out a merchant cash advance and are struggling to keep up, here is what happens when you default on an MCA — and what your options are.
Important: All eight defendants in the Par Funding case have pleaded guilty and been sentenced. This article is based on court records, Department of Justice press releases, and IRS Criminal Investigation findings — not allegations. Joseph LaForte and his co-defendants admitted to the conduct described here.
Fraud aimed at borrowers follows the same template. A separate MCA debt-settlement owner recently pleaded guilty to taking millions from small businesses with phony debt-relief promises.
Expert Context: I spent 30 years as an investigative writer tracking financial criminals — Ponzi schemers, embezzlers, affinity fraudsters. When I covered the Par Funding case for my true crime podcast, I recognized a pattern I’ve documented across dozens of schemes: a hidden criminal record, guaranteed above-market returns, and a plausible-sounding business underneath. Par Funding is a textbook case of sophisticated fraud hiding in plain sight.
Listen to the Full Episode: I covered Par Funding in depth on True Crime Cases You Haven’t Heard. Play it here or visit the episode page for show notes and transcript.
Part of the Investment Fraud Pattern Guide: This post is one case study in my complete Investment Fraud Pattern Guide — 30 years of documented schemes, the five patterns they all share, and the checks that would have stopped each one before a dollar was lost.
In July 2020, FBI agents raided the Philadelphia offices of Par Funding and uncovered nearly a decade of fraud built on a fabricated identity, impossible promised returns, and a business model that couldn’t deliver what investors were told they were buying.
Key Terms Defined
Merchant Cash Advance (MCA): A form of business financing where a company advances cash to a small business in exchange for a percentage of future revenue collected via ACH bank debits. Not technically a loan — most state usury laws don’t apply. The MCA industry is legal and widely used, but effective interest rates can be 40–100% APR equivalent.
Unregistered Securities: Investment products sold to the public without SEC filing. Selling unregistered securities is generally illegal unless an exemption applies. Par Funding sold investment contracts promising MCA-backed returns without proper registration.
Wire Fraud: Federal law (18 U.S.C. § 1343) criminalizing the use of electronic communications to execute a scheme to defraud. Up to 20 years per count — the charge that anchored most Par Funding prosecutions.
Who Was “Joe Mack” — and Who Was He Really?
The man who built Par Funding introduced himself to investors, lenders, and business partners as “Joe Mack” — a successful entrepreneur with a track record in alternative finance. The name was fictional.
His real name was Joseph LaForte. He had two prior felony convictions: a 1997 gambling conviction in New York, and a 2001 federal conviction for loan-sharking and extortion in New Jersey. Federal law bars convicted felons from working in the securities industry — which is precisely why the alias existed. A background check on “Joe Mack” returned nothing because that person didn’t exist. A background check on the man actually running the company would have ended every conversation before it started.
LaForte founded Par Funding (officially Complete Business Solutions Group, or CBSG) around 2011. Over the next nine years, he built it into a substantial operation with real offices, real employees, and a real MCA loan portfolio — layered over a fraudulent investment structure that was raising hundreds of millions from individual investors across the country.
How the Scheme Worked
Par Funding’s pitch to investors was straightforward: fund our merchant cash advance operations, and we’ll pay you 14–17% annually from the profits we generate lending to small businesses. The MCA industry is real. Returns in that range aren’t inherently impossible in a high-risk lending business. The pitch was plausible enough that 1,200 investors wrote checks.
The problem was the underlying math. Court documents and the receiver’s findings show that the actual MCA business wasn’t generating sufficient returns to sustain the payments Par Funding was making. New investor money was being used to pay existing investors — a Ponzi-like dynamic that could only continue as long as new capital kept flowing in. Par Funding also misrepresented the quality of its loan portfolio. Receivables were overstated. Non-performing accounts were presented as performing. The documents investors received described a business that existed, but not the one their money was actually in.
The Five Red Flags Investors Missed
Looking at Par Funding with what we know now, the warning signs were there throughout. This scheme didn’t succeed because it was brilliantly concealed — it succeeded because investors didn’t ask the questions that would have exposed it.
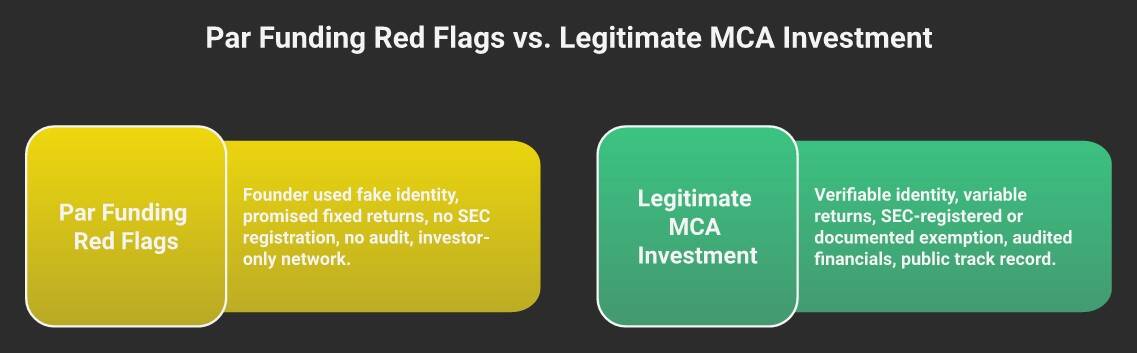
- The founder had no verifiable identity. “Joe Mack” had no prior professional history, no LinkedIn presence predating Par Funding, no news articles, no legal filings. A background check on “Joe Mack” turned up nothing because he didn’t exist. Requiring a verified identity — driver’s license, background check tied to a real person — would have ended this at the first meeting.
- Returns were fixed and above-market, regardless of conditions. Par Funding promised 14–17% annually. Legitimate investments that derive returns from a variable underlying portfolio — MCA receivables — produce variable returns. A fixed guarantee signals either that the guarantee is a lie or that the promised return is being manufactured through other means.
- The investment was unregistered. No Form D. No registration statement. A search of SEC EDGAR for Par Funding or Complete Business Solutions Group returns nothing for an investment product. Selling investment contracts without SEC registration is a federal securities law violation. This is publicly checkable in five minutes.
- No independent audit of the portfolio existed. Investors received documentation from Par Funding describing its receivables. That documentation came entirely from the company itself. No independent auditor verified that the receivables existed, were performing, or were worth what Par Funding claimed. Without an independent audit, investors were buying Par Funding’s word about Par Funding’s assets.
- Distribution was entirely through referrals. Par Funding built its investor base through word-of-mouth — one investor telling another. This social trust structure substitutes referral credibility for actual due diligence. When you invest because someone you trust vouches for the operator, you are doing their trust-screening, not yours.
The Claim: “The MCA industry is legitimate and returns like that are possible — that’s why it was credible.”
The Reality: The legitimacy of the MCA sector doesn’t validate any individual operator’s guaranteed returns. Par Funding used a real industry as cover for a fraudulent investment structure. A credible business backstory is a necessary condition for sophisticated fraud — not a defense against it. The more plausible the story sounds, the more important it is to verify independently what’s actually backing your investment.
The FBI Raid, Prosecution, and Sentencing
In July 2020, the U.S. Attorney’s Office for the Eastern District of Pennsylvania and the FBI executed a raid on Par Funding’s Philadelphia offices. The SEC simultaneously filed a civil enforcement action. LaForte was arrested in New Jersey.
Eight defendants ultimately faced criminal charges. All eight pleaded guilty. There were no acquittals, no hung juries — every defendant who went through the criminal process admitted to participating in the fraud. Joseph LaForte, the architect of the scheme, received 186 months in federal prison, sentenced March 26, 2025. Co-defendants received sentences reflecting their individual roles and cooperation with prosecutors.
The guilty pleas also facilitated asset recovery. Defendants agreed to forfeiture of assets as part of their plea agreements, giving the court-appointed receiver greater ability to pursue funds on behalf of investors.
What Investors Recovered — and the Receiver’s Work
Par Funding has an unusually good recovery story for a fraud of this size. A court-appointed receiver was placed in control of the company’s assets immediately after the 2020 raid. The receiver’s mandate was to identify, preserve, and liquidate assets to return money to investors. Based on receiver reports and recovery projections, investors are expected to recover approximately 80 cents on the dollar — roughly $480 million distributed or anticipated from an approximately $547 million fraud.
That outcome reflects two factors: aggressive asset recovery work by the receiver, including pursuing fraudulent transfer claims against third parties, and the fact that Par Funding did have a real MCA portfolio with actual receivable value. The portfolio was overstated and insufficient to sustain the fraud, but it wasn’t completely fabricated — there were real assets to liquidate.
If you were an investor in Par Funding and have not yet connected with the receiver’s process, the SEC’s enforcement page for Complete Business Solutions Group is the starting point.
What This Pattern Looks Like From the Inside
I’ve covered financial fraud cases for decades, and Par Funding follows a pattern I’ve documented across industries. The operators usually aren’t stupid people stumbling into fraud. LaForte built a real company with real employees, a real office, and a real loan portfolio — and then lied about that portfolio’s performance to justify promised returns it couldn’t actually produce. That layered structure is harder to detect from the outside than pure fabrication, which is why the scheme ran for nine years.
The alias is the element that stands out in this case. Building a completely fictional professional identity — not a nickname, not a shortened name, but an entirely fabricated person — requires planning and commitment from day one. You don’t construct a fake identity because you’re planning to run an honest business. The alias tells you that LaForte knew, at the founding, that the structure he was building couldn’t survive scrutiny of who he actually was.
Before Investing in Any Alternative Finance Product: Search SEC EDGAR for any company offering an investment. If no registration or exemption filing exists, that’s a federal securities law issue regardless of what the salesperson says about “accredited investors” or “private placements.” Also check the SEC’s enforcement actions database and run the operator’s name — their real name — through a background check service before writing a check.
How to Protect Yourself From This Pattern
- Verify the investment is registered: SEC EDGAR for federal registration, your state securities regulator for state registration
- Run a background check on the individual operators — not just the company name, but the people running it, with their full legal names
- Check FINRA BrokerCheck for any broker or adviser connected to the offering
- Require independent third-party audited financials — documents that came from the company itself are not verification
- Treat any promised fixed return above 10% as requiring extraordinary independent verification, not just the operator’s word
- Be cautious of referral-based investment distribution — social trust is not due diligence
Key Takeaways
- Par Funding raised $547 million from 1,200+ investors using a founder concealing two felony convictions behind a fake identity
- The scheme promised 14–17% annual returns on MCA investments — returns the actual business couldn’t generate
- All eight defendants pleaded guilty; LaForte received 186 months in federal prison in March 2025
- Investors are expected to recover approximately 80 cents on the dollar — an unusually high recovery rate for a fraud this size
- Every red flag — fake identity, unregistered securities, fixed above-market returns, no independent audit, referral-only distribution — was present from the beginning and publicly checkable
The Bottom Line
Par Funding raised half a billion dollars because 1,200 investors trusted a referral network instead of verifying what they were actually buying. The founder used a fake name to conceal two felony convictions, sold unregistered securities, and promised returns a legitimate business couldn’t produce. Every red flag attached to this scheme was verifiable before any money changed hands: the SEC registration status was checkable, the founder’s identity was checkable, independent audits were requestable. The 80% recovery rate is genuinely good news for victims — but it doesn’t undo what happened or change the playbook that made it work. If someone you trust vouches for an investment operator whose identity you’ve never independently verified, that trust is doing the work your due diligence should be doing.
Frequently Asked Questions
What was Par Funding’s actual business?
Par Funding (Complete Business Solutions Group, or CBSG) was a merchant cash advance company that advanced money to small businesses and collected repayment from daily revenue. The MCA business was real but insufficient to generate the 14–17% annual returns promised to investors. The shortfall was covered by using new investor money to pay existing investors — a Ponzi-like dynamic that ran for nearly a decade.
Why did Joseph LaForte use a fake name?
LaForte’s two prior felony convictions — a 1997 gambling conviction and a 2001 federal loan-sharking/extortion conviction — would have disqualified him from working in the securities industry and ended investor conversations immediately. The alias “Joe Mack” was designed to prevent background checks from surfacing this history. No investor knew his real identity during the years they invested with Par Funding.
Are Par Funding investors getting their money back?
Yes, in large part. A court-appointed receiver has been recovering assets since the 2020 raid. Based on receiver reports and projections, investors are expected to recover approximately 80 cents on the dollar — a significantly better outcome than most fraud victims achieve. If you were a Par Funding investor and haven’t connected with the receiver’s process, start with the SEC’s enforcement page for Complete Business Solutions Group.
Is the merchant cash advance industry itself fraudulent?
No. MCA is a legitimate sector of small business finance. Merchant cash advances are real products used by businesses that need fast capital and can’t access traditional bank loans. The industry has legitimate critics — mainly focused on effective interest rates and collection practices — but those are different issues from fraud. Par Funding used the MCA industry as cover for a fraudulent investment structure. The existence of that fraud doesn’t make the underlying industry illegitimate.
How can I verify whether an investment is SEC-registered?
Search SEC EDGAR for the company’s name. Look for Form D filings (private placement exemptions) or full registration statements. No filings means no registration. You can also call the SEC investor assistance line at 1-800-732-2899 to ask about any company’s registration status. Unregistered securities offerings are generally illegal — regardless of what the operator says about “private” investment structures.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



