
Quick Answer: Investment fraud follows five recurring patterns regardless of the industry used as cover: a hidden or fabricated operator identity, a legitimate-sounding business backstory, guaranteed above-market returns, referral-based distribution that substitutes social trust for due diligence, and regulatory arbitrage through unregistered securities. Every major scheme I’ve documented — from Par Funding’s $547 million MCA fraud to Eli Weinstein’s $200 million affinity scheme — hits all five. Every one of them had publicly checkable red flags before a dollar was lost.
Expert Context: I’ve spent 30 years as an investigative writer documenting financial criminals — Ponzi schemers, fake identity operators, affinity fraudsters, regulatory arbitrageurs. I also cover these cases on my true crime podcast, True Crime Cases You Haven’t Heard. After three decades of tracking these schemes, I can tell you: they don’t succeed because they’re brilliantly disguised. They succeed because investors don’t ask the five questions that would expose every one of them.
I’ve now covered enough of these cases to see the template clearly. The industry changes — merchant cash advances, trucking, crypto, real estate — but the five-pattern playbook underneath never does.
Key Terms Defined
Ponzi Scheme: A fraud where returns to existing investors are paid from new investor money rather than actual profits. Named for Charles Ponzi (1920). The scheme collapses when new investor inflows can no longer cover the payments owed to existing investors.
Unregistered Securities: Investment products sold without SEC filing. Most investment contracts require either registration or a documented exemption. Selling unregistered securities is a federal violation regardless of whether the underlying business is real.
Affinity Fraud: Investment fraud distributed through communities of shared identity — religious congregation, ethnic community, professional association. Social trust within the community substitutes for due diligence. The fraudster either is a member of the community or gains access through an initial recruiter who is.
Regulatory Arbitrage: Structuring a financial product to fall outside the regulatory framework that would require registration, audit, or oversight. Merchant cash advances aren’t loans under most state laws; certain crypto products avoid securities classification. Fraudsters specifically choose sectors where oversight is weakest.
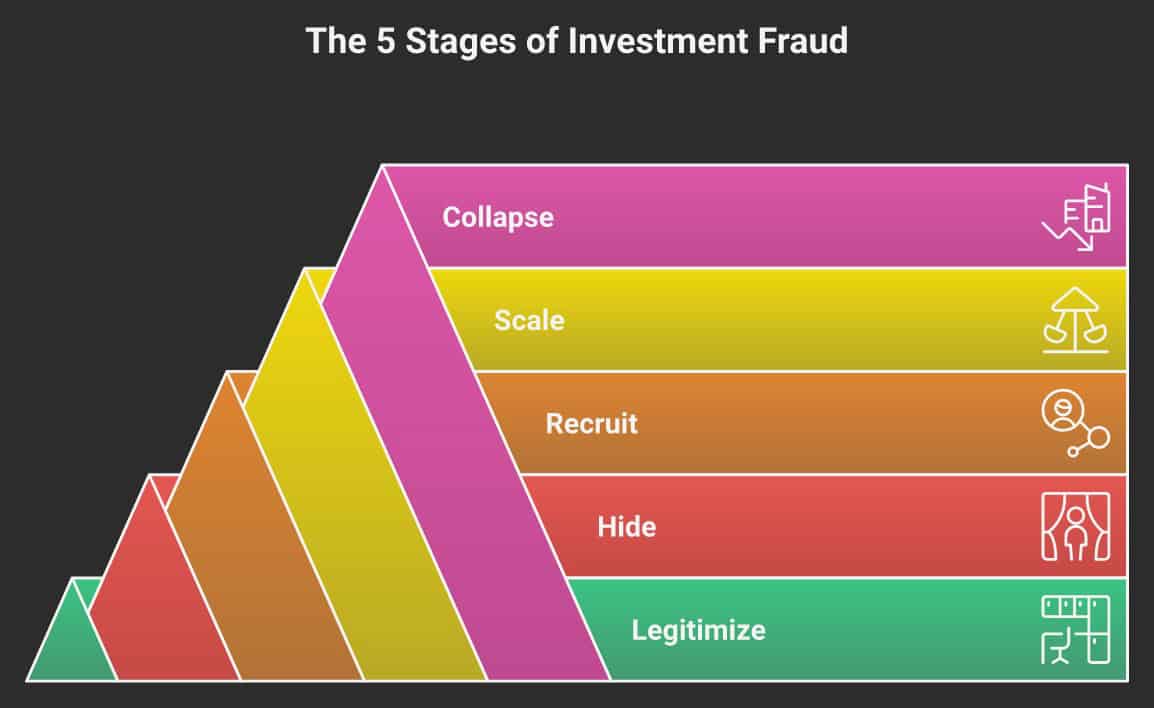
The 5 Patterns Behind Every Investment Fraud
These aren’t theories. They’re documented across every case in this guide. Check whether an investment opportunity hits all five — because the ones that do have never turned out to be legitimate.
Pattern 1: The Hidden or Fabricated Identity
The operator has something in their background that would end the conversation before it started. A prior felony. A prior enforcement action. A prior failed scheme. So they hide it — through an alias, through a corporate structure that buries their name, or through a new “clean” entity that doesn’t reference their history.
What to check: Verify the actual legal name of every person running the operation. Run it through your state’s criminal court records, federal PACER court records, and SEC enforcement actions. “We couldn’t find anything on him” after searching only the company name is not the same as a clean background check on the individual.
Case documented here: Joseph LaForte ran Par Funding as “Joe Mack” — concealing two prior felony convictions. No investor knew his real name. A background check on “Joe Mack” found nothing because that person didn’t exist.
Pattern 2: The Legitimate Industry Cover
Every scheme I’ve documented uses a real industry as its backstory. Merchant cash advances. Trucking. Cryptocurrency. Real estate. The industry is real — the problem is the investment structure layered on top of it. The legitimacy of the sector makes the pitch credible. It also makes due diligence feel unnecessary: of course trucking makes money, of course MCA generates returns.
What to check: Separate the business from the investment. Evaluate the investment product independently — does it have SEC registration? Is there an independent audit of the portfolio? Would you loan this person money without the industry backstory? The industry is not the investment.
Cases documented here: RivX used trucking as cover for an $8.39M investor fraud. SafeMoon used crypto legitimacy as cover while its CEO drained $9M from investor funds.
Pattern 3: The Guaranteed Above-Market Return
This is the mathematical tell that never changes. A real investment that derives returns from a variable underlying business produces variable returns. When an operator promises a fixed return — 14%, 17%, 20% annually, regardless of market conditions — one of two things is true: the return is a lie, or it’s being manufactured by using new investor money to pay existing investors.
There is no third option. Markets are variable. A guarantee is either fraud or a Ponzi dynamic — and usually both.
What to check: Ask how the return is calculated. Request the audited portfolio performance for the last three years. If returns are suspiciously consistent quarter over quarter, regardless of what was happening in the underlying sector, that consistency is not a selling point — it’s a red flag.
Cases documented here: Par Funding promised 14–17% annually from its MCA portfolio. Eli Weinstein promised consistent outsized returns from a real estate investment operation. Neither could deliver — both used new money to pay old investors.
Pattern 4: Referral-Only Distribution
Legitimate investment products are marketed publicly, with disclosed financials, to a wide audience. They have to be — public scrutiny is part of the price of public capital raising. When a high-return investment reaches you exclusively through a referral chain — a friend, a religious community, a professional network — ask why it’s not available to strangers.
Referral distribution serves two fraud functions: it reaches investors who are predisposed to trust the source, and it avoids the public scrutiny that would quickly expose the scheme. The social trust of the referral is not a substitute for due diligence. It’s the mechanism by which due diligence gets skipped.
What to check: Has this investment been disclosed to anyone outside the referral network? Is there a public track record? Could you find independent reviews or complaints? If the only people who know about this investment are the people the operator chose to tell, that is not a mark of exclusivity — it’s a warning.
Cases documented here: Eli Weinstein built his investor base through his Orthodox Jewish community — a classic affinity fraud. Pig butchering scams use manufactured romantic trust as the referral vector, costing U.S. victims $5.8 billion.
Pattern 5: Regulatory Arbitrage — Operating Where Oversight Is Weakest
Fraudsters don’t choose their industry randomly. They specifically seek sectors where the least regulatory oversight applies — where securities law has gaps, where state licensing requirements are weak, where the product can be structured to avoid SEC registration requirements.
Merchant cash advances aren’t loans under most state laws. Certain crypto products claim not to be securities. Some investment structures are presented as “private placements” that exempt them from registration — even when the exemption criteria aren’t actually met. The fraudster’s industry selection is itself a red flag: why is this investment structured to avoid the oversight that would verify what you’re being told?
What to check: Ask directly: “Why isn’t this investment registered with the SEC?” A legitimate answer involves a specific, documented exemption (Regulation D, accredited investor exception, etc.) with paperwork you can verify. “Because it’s private” is not an exemption. “Because it’s MCA, not a loan” is not a securities law exemption.
Cases documented here: The Utah $89M scheme exploited gaps in securities enforcement. Par Funding sold investment contracts without SEC registration — a search of EDGAR for the company returns nothing for any investment product.
The Five Checks — Before Any Dollar Changes Hands
- Verify the operator’s identity. Full legal name, background check, PACER federal court records search, SEC enforcement actions search. Not the company name — the person’s name.
- Confirm SEC registration or documented exemption. Search EDGAR for the company. If you find a Form D, verify the exemption claimed applies to your investor category. If you find nothing, that’s a federal securities law issue.
- Require independent third-party audited financials. Documents provided by the operator about the operator’s own portfolio are not verification. An independent auditor’s signed report is. Refuse to invest without one.
- Check FINRA BrokerCheck and your state securities regulator. Every state has a securities regulator with a public enforcement database. Check both. A prior state enforcement action or FINRA bar is public information — but only if you look.
- Ask why this investment isn’t publicly available. If the only people who know about this opportunity are people the operator personally chose to tell, ask why. The answer matters more than the promised return.
Cases Documented in This Guide
Par Funding: $547M MCA Fraud, Fake Identity, 186-Month Sentence
Founder Joseph LaForte operated as “Joe Mack” — concealing two prior felony convictions. All 8 defendants pleaded guilty. Investors expected to recover ~80¢ on the dollar.
Eli Weinstein: $200M Fraudster Got Clemency — Then Immediately Stole Again
Affinity fraud through the Orthodox Jewish community. Presidential clemency granted; scheme restarted. Documents the recidivist pattern that defines serial fraudsters.
Pig Butchering Scams: $5.8B in Losses and Growing
NY AG data on relationship-based investment fraud distributed through dating apps and social media. Referral trust operating at industrial scale.
SafeMoon CEO: 8 Years for Draining $9M from Crypto Investors
Crypto industry legitimacy used as cover. CEO personally drained investor funds while promoting the project publicly. Regulatory arbitrage through crypto’s securities classification gaps.
Utah Man Admits to $89M Investment Fraud Scheme
Classic guaranteed-return scheme with fabricated portfolio documentation. Exploited investor trust in the operator’s personal reputation within the community.
RivX Trucking Scam: $8.39M, FTC Shut Down
Trucking industry used as legitimate-seeming cover for fraudulent investor returns. FTC enforcement action documented the gap between promised and actual business operations.
Andris Pukke: 8 Years for Repeat Financial Fraud
Repeat offender who rebuilt a scheme after prior convictions — documenting the recidivist pattern and how prior legal history is concealed from new investors.
If You’ve Already Invested — What to Do
- File a complaint with the SEC immediately: sec.gov/tcr — tips and complaints. If a receiver is appointed, this puts you in the documented victim pool.
- File with your state securities regulator: Find yours at NASAA.org. State actions often move faster than federal ones.
- Preserve all documentation: Every email, every statement, every wire transfer confirmation, every phone recording you have. Court receivers need this to document your claim.
- Find other victims: Class actions and receiver processes have more leverage when victims are organized. Search for an existing attorney group or receiver’s website for the scheme.
- Consult a securities fraud attorney: Many take cases on contingency. NACA covers consumer-side securities cases. Your state bar’s referral service is another starting point.
- Affinity Fraud: How Scammers Target Your Church and Community — and the Red Flags in Every Case
Key Takeaways
- Every investment fraud documented here follows the same five-pattern playbook: hidden identity, legitimate industry cover, guaranteed above-market returns, referral distribution, and regulatory arbitrage
- All five checks — identity verification, SEC registration, independent audit, FINRA/state check, public availability question — are executable before any money changes hands
- Social trust from referrals is not due diligence — it’s the mechanism by which due diligence gets skipped
- A fixed return guarantee from a variable underlying business is either fraud or a Ponzi dynamic. There is no third option.
- Prior enforcement actions against an operator are public record — but only if you look up the person’s real legal name
Related: Day trading course sellers use the same playbook as investment fraudsters. See The Day Trading Fantasy for the full data on the FTC enforcement actions against Online Trading Academy, Warrior Trading, and IM Mastery Academy.
The Bottom Line
After 30 years covering financial criminals, I’ve stopped being surprised by the schemes themselves. What still surprises me is how consistently the same five red flags appear in every case — and how consistently investors don’t check them. Not because they’re lazy, but because the social context of the pitch makes checking feel like an insult. The referral came from a friend. The operator seems credible. The industry makes sense. That comfort is exactly what the fraud is designed to create. The five checks in this guide take less than an hour. Every scheme documented on this page could have been stopped by someone doing them.
Frequently Asked Questions
What’s the difference between investment fraud and a bad investment?
A bad investment fails because the underlying business underperformed — the market moved against it, management made mistakes, or the sector contracted. Investment fraud involves intentional misrepresentation: the operator lied about returns, concealed their identity or criminal history, sold unregistered securities, or used investor money for personal enrichment. Bad investments lose money. Fraud steals it. The legal distinction matters for recovery — fraud victims have recourse that bad-investment victims don’t.
How do I check if an investment opportunity is SEC-registered?
Search SEC EDGAR for the company name. Look for registration statements (S-1, etc.) or Form D filings (private placement exemptions). No filings means no registration. You can also call the SEC investor assistance line at 1-800-732-2899. Unregistered securities offerings are a federal violation regardless of what the operator says about “private” structures.
What is PACER and how do I use it to check an investment operator?
PACER (Public Access to Court Electronic Records) is the federal court records database. Create a free account and search by the operator’s full legal name — not just the company name. Federal criminal cases, prior civil judgments, and prior SEC enforcement actions are all in there. Most searches are free or cost a few cents per page. For a deeper dive, see my guide on using PACER to research any financial company.
Can I get my money back if I’ve been defrauded?
Sometimes — and more than most people expect. When federal or state action results in asset seizure, a receiver is typically appointed to recover funds for victims. The Par Funding receiver, for example, is projecting approximately 80% recovery. The key factors are how quickly action is taken (more assets remain), how much real underlying business existed, and whether victims are organized and documented. File with the SEC and your state regulator immediately — that puts you in the official victim record before the receiver’s process begins.
What’s the fastest way to spot a Ponzi scheme?
Ask for three years of audited returns from an independent third party. If returns are suspiciously consistent — same percentage, same quarter-over-quarter pattern regardless of what was happening in the underlying sector — that consistency is the tell. Real businesses have variance. A fixed-return guarantee from a variable business either means the guarantee is a lie or it’s being manufactured by using new money to pay old investors. Either answer is a Ponzi.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



