

Quick Answer: If your debt settlement company fails to settle an account before the creditor sues you, you’re at risk of a default judgment if you don’t respond — but being sued does not mean it’s too late. Creditors and collectors often settle even after a lawsuit is filed, and sometimes even after a default judgment is entered. The critical action is this: respond to the lawsuit before the deadline (usually 20–30 days depending on your state). Ignoring a lawsuit guarantees you lose. Responding keeps your options open.
Expert Context: I ran a nonprofit credit counseling organization and watched debt settlement marketing corrupt good intentions from inside the industry. The scenario of a creditor suing while a consumer is enrolled in a settlement program is one of the most predictable — and least-disclosed — risks of the debt settlement model.
This question came through the Ask Steve chat — and it exposes one of the most important things the debt settlement industry doesn’t tell you upfront: enrolling in a program doesn’t protect you from lawsuits.
The Question That Came In:
“I’ve been enrolled in a debt settlement program for about a year. One of my accounts apparently didn’t get settled and now I’ve been served with a lawsuit from the creditor. What happens now? Is it too late? My settlement company hasn’t told me anything useful.”
This is one of the highest-stakes situations in the debt settlement world — because the clock starts ticking the moment you’re served, and the wrong move (or no move) can cost you far more than the original debt.
Based on CFPB complaint narratives, lawsuits filed while consumers are enrolled in debt settlement programs represent one of the most common complaints in the debt relief category — and the most urgent situations I see come through.
Why This Happens: The Core Problem With Debt Settlement
Debt settlement programs don’t stop creditors from suing you. That’s a fundamental reality that most settlement companies bury in their disclosures. While you’re making deposits into an escrow account and the company is negotiating with some creditors, other creditors are watching — and when they decide the account is going nowhere, they file suit.
Common Misconception: “Being enrolled in a debt settlement program means my creditors have to work with the settlement company and can’t sue me.”
The Reality: Enrollment in a debt settlement program provides zero legal protection from lawsuits. Creditors can — and regularly do — sue accounts in settlement programs, especially when they believe the consumer has assets worth pursuing or when the debt has been sitting unsettled for too long.
What Happens If You Don’t Respond to a Lawsuit
This is the most important thing to understand: if you don’t respond to a civil lawsuit within the deadline (typically 20–30 days after being served, depending on your state), the court enters a default judgment against you.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
A default judgment gives the creditor the ability to:
- Garnish your wages (up to 25% of disposable income, depending on state)
- Levy your bank account
- Place a lien on property you own
- Renew the judgment when it expires (in most states)
Default judgments are serious — but they’re also avoidable if you act immediately after being served.
What to Do Right Now (In This Order)
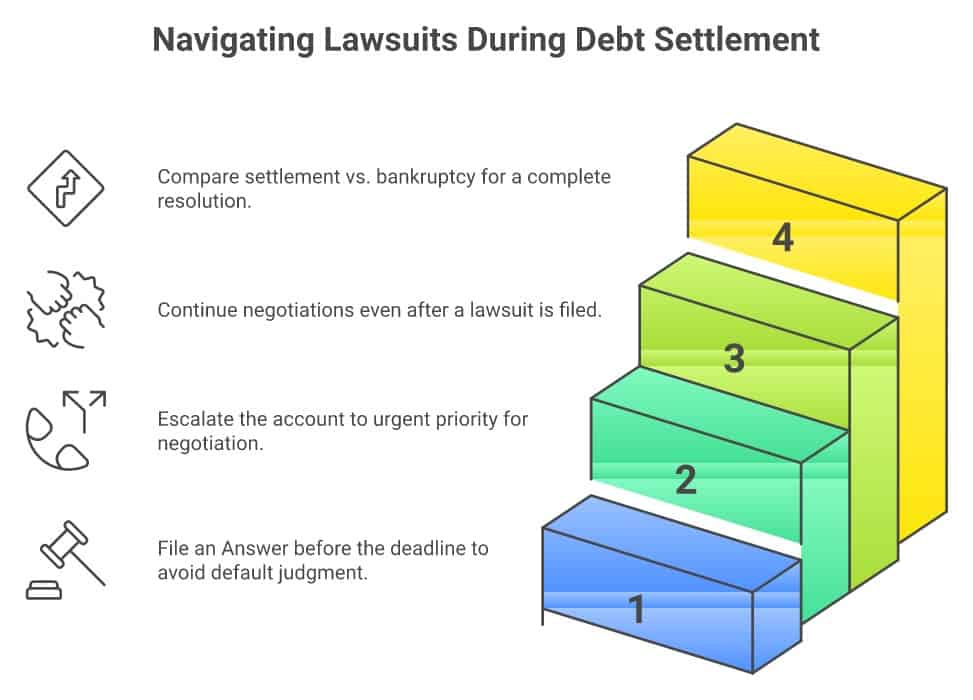
1. Don’t Ignore the Lawsuit — Respond Before the Deadline
The single most important thing is to file a response (called an “Answer”) before the deadline stated on the summons. You don’t need to win the case to benefit from responding — you just need to show up. Courts often schedule a hearing once you respond, which opens the door to negotiation before any judgment is entered.
If you can’t afford an attorney to respond, you may be able to file a pro se Answer yourself — check your courthouse’s self-help resources or LawHelp.org for assistance in your state.
2. Contact Your Debt Settlement Company Immediately
If your settlement company hasn’t already flagged this account as a priority, tell them about the lawsuit today. A legitimate settlement company should escalate this to the top of their queue — they need to reach the creditor or their attorney now, not next month. According to the CFPB’s guidance on debt settlement, you should be receiving regular updates on the status of all your enrolled accounts. If you’re not, that’s a problem with how the company is managing your case.
3. Understand That Negotiation Is Still Possible
Here’s the part that surprises most people: being sued doesn’t end your ability to negotiate. Many creditors and their attorneys settle accounts during active litigation — sometimes for less than the original offer, because a settlement avoids a drawn-out court process for everyone. Even after a default judgment is entered, some creditors will vacate (undo) the judgment as part of a settlement agreement.
The lawsuit is pressure, not a final answer. But you have to respond to keep that door open.
4. Evaluate Your Overall Situation
If one creditor has sued, others may follow. This is a signal worth taking seriously about the overall viability of your debt settlement strategy. Some questions to consider:
- How many accounts are still unsettled and how old are they?
- Do you have steady income that could be garnished?
- Is the total debt large enough that bankruptcy might make more sense as a clean resolution?
Use the Find Your Path quiz to evaluate whether staying in settlement or switching to bankruptcy better serves your situation at this point.
Are You Judgment-Proof? If you have no wage income (or exempt income like Social Security), no significant bank account balance, and no property to lien, you may be effectively judgment-proof — meaning even if the creditor wins, they can’t collect anything meaningful from you. This doesn’t eliminate the judgment, but it changes how urgent the immediate threat is. This is something to discuss with a consumer law attorney in your state.
Before You Sign With Any Debt Settlement Company: If you’re still evaluating debt settlement companies, run their contract through the free Contract Decoder first. Lawsuit risk, response obligations, and what the company does when you’re sued are typically buried in the fine print.
No Article Replaces an Attorney Licensed in Your State: This post gives you the framework to understand what’s happening, but a lawsuit with a live deadline is exactly the situation where you need someone qualified to evaluate your specific case. Courts are unforgiving about missed response deadlines.
How to find a consumer law attorney:
- NACA — National Association of Consumer Advocates — Specializes in FDCPA and debt-related consumer cases. Many take cases on contingency.
- Your state bar’s lawyer referral service — Search “[your state] bar association lawyer referral” for low-cost consultations.
- LawHelp.org — Free and reduced-cost legal aid by state and issue.
Have a specific situation to work through? The details matter a lot here — which state you’re in, how long ago you were served, what’s in your settlement company’s contract, and whether you have assets a creditor could take. Ask Steve directly in the chat and I’ll help you think through your options.
The Bottom Line
Being sued while enrolled in a debt settlement program is a real risk that most settlement companies don’t emphasize — and it means your program failed to settle that account before the creditor lost patience. The most important thing: respond to the lawsuit before the deadline on your summons (usually 20–30 days), or you lose by default and give the creditor the ability to garnish wages or levy accounts. Responding keeps the door open to negotiation — creditors settle during active litigation more often than most people realize. If a lawsuit has changed your math on debt settlement, use the Find Your Path quiz to evaluate whether bankruptcy would give you a cleaner resolution. And contact your settlement company immediately — if they’re not actively working this account, that’s a problem worth documenting.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
Frequently Asked Questions
Can I get sued while enrolled in a debt settlement program?
Yes — debt settlement programs provide no legal protection against lawsuits. Creditors can sue at any time, regardless of whether you’re enrolled in a settlement program. Enrollment means the settlement company is negotiating on your behalf, but it does not create a legal stay on collections or lawsuits. This is one of the most common situations in the debt settlement complaints the CFPB receives from consumers.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
What happens if I ignore a debt collection lawsuit?
If you don’t respond to a lawsuit within the court’s deadline (typically 20–30 days after being served, depending on your state), the court enters a default judgment against you. A default judgment gives the creditor the legal right to garnish your wages, levy your bank account, and place liens on property. Courts do not require the creditor to prove you actually owe the debt in a default — the fact that you didn’t show up is enough. Never ignore a lawsuit summons.
Is it too late to settle a debt after a lawsuit is filed?
No — and this surprises many people. Creditors and their collection attorneys often settle accounts during active litigation, because a negotiated settlement is faster and cheaper than going to trial. Some creditors even settle after a default judgment is entered, and may agree to vacate (reverse) the judgment as part of the settlement terms. The lawsuit creates urgency and leverage, but it doesn’t eliminate your ability to negotiate. You just need to respond to keep that option open.
What should I do if my debt settlement company isn’t responding about a lawsuit?
Contact them in writing (email leaves a paper trail) and tell them you’ve been served and need their immediate response on the account. Document every attempt to reach them. If they fail to act, you may have grounds for a complaint — file with the CFPB and your state attorney general. More urgently: don’t wait for them. The lawsuit deadline runs whether or not your settlement company acts, so consider consulting a consumer law attorney directly about your options on the sued account while the company handles others.
Should I stay in debt settlement or file bankruptcy if I’m being sued?
This is a case-by-case calculation. A lawsuit against one account while others are settled or near settlement may not change your overall strategy. But if the lawsuit signals that your program is falling apart — multiple accounts unsettled, creditors increasingly aggressive — bankruptcy may provide a cleaner resolution. Chapter 7 would discharge your unsecured debts in 3–4 months and, once filed, immediately triggers an automatic stay that stops the lawsuit in its tracks. Use the Find Your Path quiz or consult with a bankruptcy attorney to compare the math.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



