

Quick Answer: NCB Management Services is a for-profit debt collection company based in Trevose, Pennsylvania. If they’re contacting you, you have specific federal rights under the FDCPA. Here’s how to verify who they are, check their complaint history, and understand your options.
Before You Read This: I want to be upfront about what this page is and isn’t. I’m not rendering a verdict on NCB Management Services. This is a research guide — I’m showing you where to look so you can reach your own conclusions based on current information.
If you find something in the public record that concerns you, post it in the comments below. If you’re evaluating a settlement offer in writing, use my free Contract Decoder tool.
If you represent NCB Management Services and something here is inaccurate, contact me and I’ll review it promptly.
Each weekday I send one short email: one story that caught my attention, why it might matter to you, and one manageable thing you can do with it. A couple of minutes, and a dad joke.
In the latest issue (Nov 6): Owed money on an Amazon return? Check by Dec. 1
Free. I sell nothing. Unsubscribe any time.
If you have inside information you feel you need to share with me privately: don’t. Whatever you want to share should be posted in the comments — by you, with your name attached. I’m not willing to be anyone’s conduit for information they won’t stand behind themselves.
The most valuable thing on this page may not be what I’ve written — it’s the comments section below. People who’ve dealt with NCB Management Services share their experiences there. I’d encourage you to read them and add your own.
Who Is NCB Management Services?
An educated consumer is our best customer.— Sy Syms
Debt collector contacting you? My Ultimate Consumer Guide to Checking Out a Debt Relief Company includes a section on verifying debt collectors and understanding your rights before you respond.
NCB Management Services is a for-profit debt collection company. Rather than repeat what they say about themselves here, I’d encourage you to verify their identity through their BBB profile and state licensing records — especially if they’ve contacted you and you’re not certain the debt is legitimate.
Step 1: Verify Who They Are and Their Right to Collect
Before you respond to any debt collector, verify these things:
- Request a debt validation letter: Under the FDCPA, you have the right to request written verification of the debt within 30 days of first contact. Send the request via certified mail. They must stop collection attempts until they provide validation.
- BBB Profile: Check their Better Business Bureau profile — confirm the company name, address, and phone number match what they’ve given you. Scam collectors often impersonate legitimate agencies.
- State Licensing: Many states require debt collectors to be licensed. Check your state’s financial regulator or attorney general website to confirm NCB Management Services is licensed to collect in your state.
- CFPB Debt Collector Registration: The CFPB maintains a registration system for larger debt collectors. You can verify registered collectors at consumerfinance.gov.
Your FDCPA Rights: The Fair Debt Collection Practices Act prohibits debt collectors from calling before 8am or after 9pm, using abusive language, threatening arrest, or misrepresenting the amount owed. If NCB Management Services violates any of these, you can file a complaint with the CFPB and potentially sue them in federal court. Document every contact — date, time, what was said.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
Step 2: Check Consumer Complaints
The Consumer Financial Protection Bureau maintains a public database of complaints filed against debt collectors. Search for NCB Management Services directly:
Search NCB Management Services’ complaint history in the CFPB database →
When you’re reading complaints, look for:
- What the complaints are about — debt validation failures, harassment, wrong-person contact, disputed balances?
- How the company responded — did they resolve issues or just close them?
- Whether the same issue appears repeatedly — a pattern matters more than a single complaint
- Whether complaints describe the exact issue you’re experiencing — that’s the most useful signal
Step 3: Read What Others Have Experienced
NCB Management Services doesn’t have a Trustpilot profile, but there are other places to find consumer experiences:
How to evaluate online reviews of debt collectors: For debt collectors, reviews skew negative because people contact them involuntarily. What matters most isn’t the rating — it’s whether complaints describe illegal conduct (harassment, false statements, wrong-person contact) vs. normal collection activity people don’t like. Those are very different situations.
- BBB reviews: The BBB profile includes both ratings and complaint text — read the actual complaints, not just the summary
- Google reviews: Search “NCB Management Services reviews” — these are often more candid than BBB complaints
- Consumer forums: Sites like Reddit’s r/personalfinance and r/debtfree often have threads from people who’ve dealt with specific collectors. Search by company name.
- PACER/CourtListener: If they’ve sued consumers in federal court, those records are public. See Step 4.
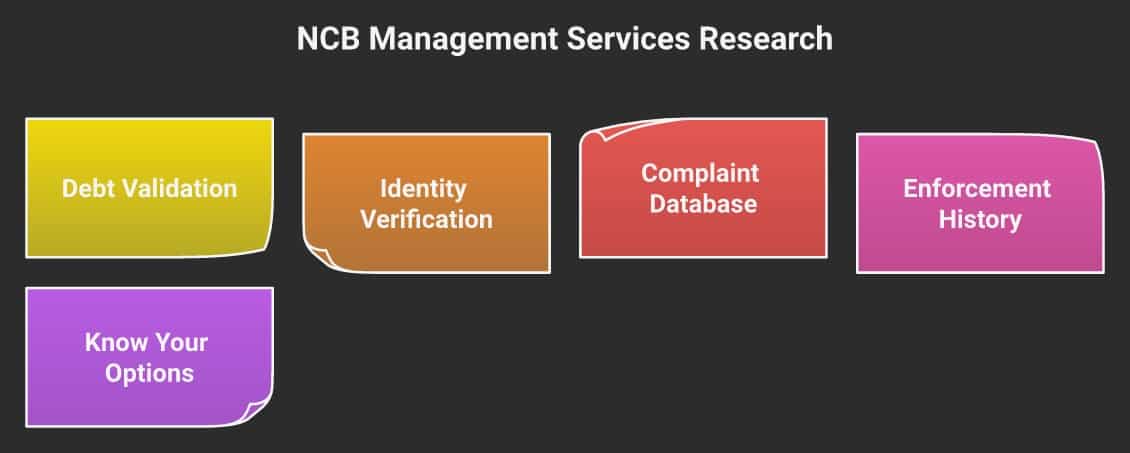
Step 4: Check Their Legal and Enforcement History
Debt collectors are among the most-regulated industries under the CFPB. Here’s where to look for enforcement history:
- CFPB Enforcement Actions: Search the CFPB’s enforcement action database for “NCB Management Services” and any related entity names
- FTC Actions: The FTC publishes all enforcement cases — the FTC has historically brought major FDCPA cases against debt collectors
- State Attorney General: Search “NCB Management Services attorney general” — many debt collection enforcement actions happen at the state level
- Federal Court Records: CourtListener searches 1.3 billion federal court documents for free — search for cases where NCB Management Services is a defendant (FDCPA lawsuits) and cases where they’re a plaintiff (lawsuits against consumers). Both are useful. For the official PACER system, see my guide to using PACER.gov.
Context Matters: A company that has faced enforcement action isn’t automatically acting illegally in your case — what matters is what the action was for and whether that conduct matches what you’re experiencing. A company with no enforcement history may simply not have been scrutinized yet.
Step 5: Know Your Options Before You Respond
Before agreeing to anything in writing: Run the settlement offer or payment agreement through my free Contract Decoder tool. Paste it in and get a plain-English breakdown of what you’re agreeing to.
You have more options than most people realize when dealing with a debt collector. Get clarity on these before you respond:
- Is the debt actually yours — name, account number, original creditor, and amount all match your records?
- Is the debt within the statute of limitations in your state? Paying or acknowledging an old debt can restart the clock.
- Has the debt already been discharged in bankruptcy or settled?
- If you’re considering a settlement, get the agreed amount and settlement terms in writing before you pay anything
- If you believe they’ve violated the FDCPA, consult a consumer protection attorney — many take these cases on contingency
- If the debt is legitimate and unaffordable, run your situation through my Find Your Path tool to understand your full range of options
Statute of Limitations Warning: Making a payment on a time-barred debt can restart the statute of limitations in many states, giving the collector new legal power to sue you. Know your state’s SOL before you pay anything on an old debt. Run your situation through Find Your Path to understand what applies to you.
Key Takeaways
- Request written debt validation before responding — you have 30 days under the FDCPA
- Verify their identity through the BBB profile and state licensing records
- Read CFPB complaints for patterns of harassment, validation failures, or wrong-person contact
- Check CourtListener for both FDCPA cases against them and collection lawsuits they’ve filed
- Know your state’s statute of limitations before making any payment on old debt
- The comments section below contains real experiences from real consumers — read them
Want the full research playbook? My Ultimate Consumer Guide to Checking Out a Debt Relief Company covers every tool and source in this guide — plus detailed walkthroughs for reading BBB profiles and searching federal court records on CourtListener.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Frequently Asked Questions
Who is NCB Management Services and why are they calling me?
NCB Management Services is a debt collection company based in Trevose, Pennsylvania. They collect on behalf of original creditors or purchase debt portfolios. If they’re contacting you, they believe you owe a debt — but you have the right to request written verification before responding or paying anything.
How do I make NCB Management Services stop calling?
Under the FDCPA, you can send a written cease-communication request via certified mail. Once they receive it, they must stop contacting you except to confirm they’re ceasing contact or to notify you of a specific legal action. Send it certified mail with return receipt so you have proof of delivery.
How do I file a complaint against NCB Management Services?
File a complaint with the CFPB at consumerfinance.gov/complaint, with your state attorney general’s office, and with the FTC at reportfraud.ftc.gov. If they’ve violated the FDCPA, you may also have the right to sue them — consult a consumer protection attorney.
Is NCB Management Services a scam?
NCB Management Services appears to be a legitimate registered debt collection company with a BBB profile. However, scammers do impersonate legitimate collectors. Verify their identity by checking that the name, address, and phone number match the BBB listing, and always request written debt validation before paying anything.
Do I have to pay NCB Management Services?
That depends on whether the debt is valid, whether it’s within your state’s statute of limitations, and whether you have any defenses. I’d encourage you to run your situation through my Find Your Path tool before making any payments — there are more options than most people realize, including debt settlement, bankruptcy, and in some cases doing nothing if the debt is time-barred.
Share Your Experience with NCB Management Services
If you’ve dealt with NCB Management Services — as a consumer, a former employee, or someone researching them — I’d encourage you to share your experience in the comments. Your perspective helps others know what to expect.
To share your experience: Scroll to the bottom of this page — the comments box is there.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Chapter 7 bankruptcy generally ends in a discharge for individual filers in more than 99% of cases, excluding cases dismissed or converted (U.S. Courts) — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.
Browse all Debt Collectors & Debt Buyers reviews, or see the full Company Reviews directory.



