

Quick Answer: Grace Debt Relief is a for-profit debt settlement company based in San Diego, California. To evaluate whether they’re right for your situation, I’d encourage you to check their complaint history with the CFPB, read consumer reviews, and check their legal and enforcement history. Here’s how to do each of those.
Before You Read This: I want to be upfront about what this page is and isn’t. I’m not rendering a verdict on Grace Debt Relief. This is a research guide — I’m showing you where to look so you can reach your own conclusions based on current information.
If you find something in the public record that concerns you, post it in the comments below. If you’re evaluating their enrollment agreement or any contract, use my free Contract Decoder tool.
If you represent Grace Debt Relief and something here is inaccurate, contact me and I’ll review it promptly.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Oct 8): A parent's nursing home bill can become yours
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
If you have inside information you feel you need to share with me privately: don’t. Whatever you want to share should be posted in the comments — by you, with your name attached. I’m not willing to be anyone’s conduit for information they won’t stand behind themselves.
The most valuable thing on this page may not be what I’ve written — it’s the comments section below. People who’ve actually worked with Grace Debt Relief share their experiences there. I’d encourage you to read them and add your own.
Who Is Grace Debt Relief?
An educated consumer is our best customer.— Sy Syms
New here? My Ultimate Consumer Guide to Checking Out a Debt Relief Company walks through how to vet any debt relief company before you sign anything.
Grace Debt Relief is a for-profit debt settlement company. Rather than repeat what they say about themselves here, I’d encourage you to read their own website and California state business filings — that way you’re seeing it directly from primary sources, not filtered through me.
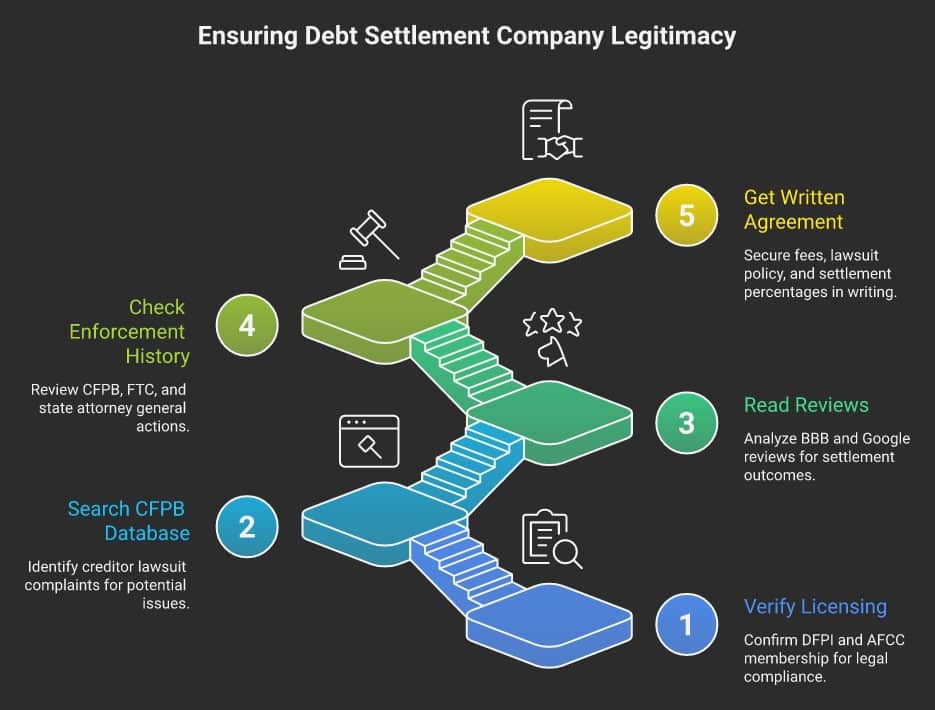
Step 1: Check Their Credentials
Before anything else, verify what credentials they hold. Here’s what to check for a debt settlement company:
- California DFPI Licensing: Debt settlement companies in California must comply with the California Debt Settlement Services Act and may need to be licensed with the California Department of Financial Protection and Innovation (DFPI). Verify their licensing status before enrolling.
- AFCC Membership: The American Fair Credit Council is the trade association for debt settlement companies. Verify whether Grace Debt Relief is a current AFCC member — membership status can change.
- State Licensing in Your State: Debt settlement companies must be licensed in each state they operate in. Check with your state’s department of consumer affairs or financial regulation to confirm they’re licensed in your state before you enroll.
- BBB Profile: Check their Better Business Bureau profile — look at the rating, years in business, and especially the complaint history and how they responded to each one.
A Note on BBB Grades: A high BBB grade doesn’t necessarily mean a company is right for you — it means they respond to complaints filed through the BBB. Read the actual complaint text and the company’s responses. That’s the useful part. See my full guide to what BBB letter grades actually mean →
Step 2: Check Consumer Complaints
The Consumer Financial Protection Bureau maintains a public database of complaints filed against financial companies. You can search for Grace Debt Relief directly:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Search Grace Debt Relief’s complaint history in the CFPB database →
When you’re reading complaints, look for:
- What the complaints are about — fees charged before settlements, creditor lawsuits during the program, communication problems?
- How the company responded — did they resolve issues or just close them?
- Whether the same issue appears repeatedly — a pattern matters more than a single complaint
- Complaints from clients who were sued by creditors while enrolled — that’s a known risk in debt settlement programs
Step 3: Read What Others Have Experienced
Grace Debt Relief doesn’t appear to have a Trustpilot profile, but there are other places to find consumer experiences:
How to evaluate reviews: Look beyond the star rating. What matters most is whether reviews describe actual outcomes — debts settled at what percentage, total cost vs. what was quoted, program completed as promised. Outcome reviews tell you far more than enrollment-experience reviews.
- BBB reviews: The BBB profile includes both ratings and complaint text — read the actual complaints, not just the summary
- Google reviews: Search “Grace Debt Relief reviews” or “Grace Debt Relief San Diego reviews” — Google reviews often surface candid accounts from people who’ve been through the program
- Consumer forums: Reddit’s r/personalfinance and r/debtfree often have threads from people who’ve worked with specific companies. Search by name.
Step 4: Check Their Legal and Enforcement History
For-profit debt settlement companies are subject to enforcement from federal and state regulators. Here’s where to look:
- CFPB Enforcement Actions: Search the CFPB’s enforcement action database for “Grace Debt Relief” and related names
- FTC Actions: The FTC publishes all enforcement cases — search for the company and its principals. The FTC’s Telemarketing Sales Rule prohibits collecting advance fees in debt settlement.
- California DFPI and AG: Search “Grace Debt Relief California attorney general” or “Grace Debt Relief DFPI” — California has active consumer protection enforcement in the debt relief space
- Federal Court Records: CourtListener searches 1.3 billion federal court documents for free — search for cases where Grace Debt Relief is a party. For the official PACER system, see my guide to using PACER.gov.
The Debt Settlement Risk Nobody Talks About: During a debt settlement program — which can take two to four years — your enrolled accounts go delinquent and your credit score drops significantly. Creditors may sue you during this period. The company typically can’t prevent lawsuits, and some lawsuits result in wage garnishment. Whether this risk is acceptable depends on your income, assets, and how aggressively your creditors historically pursue judgments.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Step 5: Ask the Right Questions Before You Enroll
Before signing anything: Run their enrollment agreement through my free Contract Decoder tool. Paste it in and get a plain-English breakdown of what you’re agreeing to — including when fees are charged and what happens if a creditor sues you.
Before you commit to a debt settlement program, get clear answers — in writing — to these questions:
- What is the total cost — all program fees — as a percentage of enrolled debt or settled debt?
- When are fees collected — before or after settlements are reached with each creditor?
- What happens if a creditor sues me during the program? Will they assist with legal defense?
- What is the typical settlement percentage for my specific creditors — based on actual results, not marketing claims?
- What happens to my dedicated account if I cancel?
- What is the realistic timeline for my specific debt level and creditors?
Before You Commit: Debt settlement isn’t right for everyone. Run your situation through my Find Your Path tool to see whether settlement, bankruptcy, a debt management plan, or another option fits your situation better. The retirement cost most people never calculate applies to settlement programs too.
Key Takeaways
- Verify California DFPI licensing and state licensing in your own state before enrolling
- Read CFPB complaints specifically for creditor lawsuit experiences during enrollment
- No Trustpilot profile — use BBB reviews and Google reviews as alternatives
- Check CFPB, FTC, and California AG/DFPI enforcement actions
- Get fee structure, lawsuit policy, and settlement percentage ranges in writing before you sign
- The comments section below contains real experiences from real clients — read them
Want the full research playbook? My Ultimate Consumer Guide to Checking Out a Debt Relief Company covers every tool and source in this guide — plus detailed walkthroughs for reading BBB profiles and searching federal court records on CourtListener.
Frequently Asked Questions
What is Grace Debt Relief?
Grace Debt Relief is a for-profit debt settlement company based in San Diego, California. They enroll clients in programs where unsecured debts are negotiated with creditors, typically after accounts become delinquent. The specific terms, fees, and realistic outcomes for your situation are something you need to verify directly with them and get in writing before enrolling.
How do I file a complaint against Grace Debt Relief?
You can file a complaint with the CFPB at consumerfinance.gov/complaint, with the California Department of Financial Protection and Innovation, with your own state’s consumer protection agency, and with the BBB. Filing with the CFPB creates a public record and triggers a required company response.
Is Grace Debt Relief a legitimate company?
Grace Debt Relief is a registered for-profit company with a BBB profile. Whether debt settlement is the right approach for your specific situation — and whether this company delivers on its promises — is what their complaint history, reviews, and a direct consultation can help you evaluate.
Will debt settlement hurt my credit score?
Yes, significantly. During a debt settlement program, your enrolled accounts go delinquent — which damages your credit score. The settled accounts then show as “settled for less than the full amount” on your credit report. The credit damage is typically severe while in the program and takes years to recover.
What’s the difference between debt settlement and a debt management plan?
A debt management plan (DMP) lowers interest rates, but you still repay the full balance over three to five years, and five years of those payments can cost $400,000+ in lost 401(k) contributions and employer match, which is why it is worth pricing bankruptcy before choosing a DMP or debt settlement. Debt settlement involves stopping payments to creditors, which damages your credit, while saving toward negotiated lump-sum payoffs. Run your situation through my Find Your Path tool to compare.
Share Your Experience with Grace Debt Relief
If you’ve worked with Grace Debt Relief — as a client, a former employee, or someone who evaluated them and decided not to enroll — I’d encourage you to share your experience in the comments. Your perspective helps others make a more informed decision.
To share your experience: Scroll to the bottom of this page — the comments box is there.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.
Browse all Debt Settlement Companies reviews, or see the full Company Reviews directory.



