

Quick Answer: Yes, student loan interest keeps accruing during the bankruptcy automatic stay — the stay stops collection activity and required payments, but it does not stop interest from compounding on your balance. In Chapter 7, this typically means 3–6 months of accrual. In Chapter 13, interest can compound for 3–5 years, sometimes leaving borrowers owing more than when they filed. But here’s what most people asking this question are missing: 87% of borrowers who pursue student loan discharge in bankruptcy succeed. If you’re worried about interest growing during the stay, the more important question is whether you’re pursuing discharge at all.
Expert Context: I filed bankruptcy in 1990 after my real estate business collapsed. I know exactly what it feels like to watch numbers grow on paper while you’re legally prevented from doing anything about them. I also founded a credit counseling organization and spent years watching people obsess over the wrong financial metrics. The question about interest during the stay is real — but it’s often a symptom of a much bigger missed opportunity.
The Automatic Stay: What It Actually Stops (And What It Doesn’t)
When you file for bankruptcy, the automatic stay kicks in immediately under 11 U.S.C. § 362. It’s one of the most powerful legal protections in the bankruptcy code. The moment your case is filed, creditors must stop:
- All collection calls and letters
- Wage garnishment
- Lawsuits to collect debts
- Repossessions and foreclosures
- Required loan payments
But the automatic stay has limits that catch people off guard. It does not stop:
- Interest from accruing on your outstanding balances
- Criminal proceedings
- Child support and alimony obligations
- Certain tax collection by the IRS
This is the answer to your specific question: your student loan servicer cannot call you, cannot garnish your wages, and cannot demand payment — but the interest meter keeps running. The balance grows quietly in the background throughout your bankruptcy case.
The Myth: “The bankruptcy stay freezes everything. My balance is locked in place while I’m in bankruptcy.”
The Reality: The stay freezes collection activity — not interest accrual. Your student loan balance is growing during the stay whether you know it or not. The legal protection is real and valuable, but the balance clock never stops.
Chapter 7 vs. Chapter 13: Why the Difference Matters Enormously
How much the interest accrual hurts you depends almost entirely on which chapter you filed.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Chapter 7 (3–6 Months)
- Interest accrues, but only for the short duration of the case
- On $50,000 in loans at 7% interest, you’d accrue roughly $1,750–$3,500 during the stay
- If you pursue and win discharge, all of it — principal and accrued interest — disappears
- If loans survive (no discharge attempt), you exit with balance + a few months of interest
Chapter 13 (3–5 Years)
- Interest compounds for years — this is a genuinely serious problem
- On $50,000 at 7%, you could exit owing $20,000+ more than you entered
- Chapter 13 plans often don’t include student loan payments, meaning interest grows unchecked
- Borrowers regularly emerge from Chapter 13 deeper in student loan debt than before they filed
The math is different enough that it changes the strategic calculus completely. A Chapter 7 filer asking about interest during the stay has a different problem than a Chapter 13 filer asking the same question.
The Number Nobody Mentions When You Ask About Accruing Interest
Here’s where I want to shift your attention, because I think you might be solving the wrong problem.
If you have student loans and you’re in bankruptcy — or considering it — the question of whether interest accrues during the stay is secondary to a much more important question: Are you pursuing discharge of those student loans?
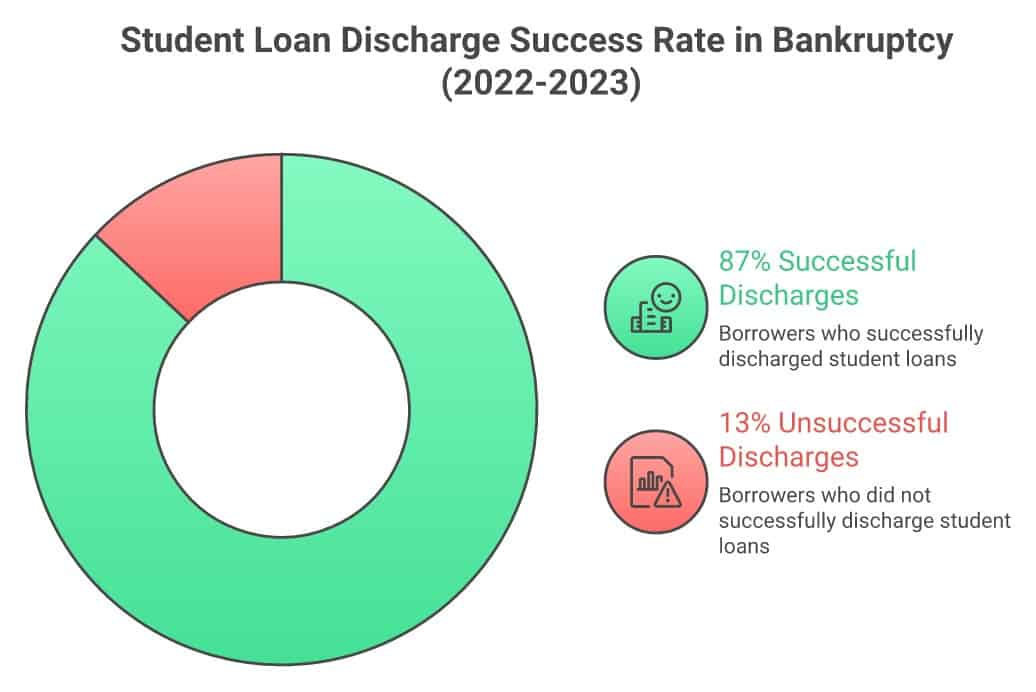
A 2025 study by Jason Iuliano, a law professor at the University of Utah’s S.J. Quinney College of Law and published in the American Bankruptcy Law Journal, found that 87% of borrowers who took the extra step of pursuing student loan discharge in bankruptcy succeeded in eliminating most or all of their loans. That’s up from 61% in 2017 and roughly 40% in 2007.
But out of more than 3 million student loan borrowers who filed for bankruptcy between 2011 and 2024, only 7,293 even tried.
That gap — between 3 million and 7,293 — is not a gap in eligibility. It’s a gap in awareness.
The fear of interest accruing on your student loans during bankruptcy is real. But it’s a much smaller problem than the opportunity most people leave completely untouched. — Steve Rhode
What Changed in 2022 (And Why It Matters for Your Decision)
For decades, student loan discharge in bankruptcy required proving “undue hardship” — a standard courts interpreted so harshly that it effectively made discharge impossible for most people. That changed significantly in November 2022 when the U.S. Department of Education and the Department of Justice issued new guidance that simplified and standardized the process.
Under the 2022 guidance, borrowers can submit a detailed financial hardship attestation rather than enduring years of aggressive court battles. The process was designed to treat student loans more like other unsecured debts in bankruptcy — which is what they are.
Practical Step: If you’re in bankruptcy or considering it, ask a bankruptcy attorney specifically about filing an adversary proceeding to pursue student loan discharge. Don’t assume your loans can’t be discharged — that assumption has cost millions of people a real opportunity.
If You’re in Chapter 13, Here’s the Specific Problem You Face
For Chapter 13 filers, the interest accrual question has real teeth. Your plan runs for 3–5 years, and during that time:
- Your plan payments go toward priority debts (mortgage arrears, taxes, secured debt) first
- Student loans typically sit as unsecured non-priority debt, receiving little or no plan payments
- Interest compounds throughout — at federal loan rates (typically 5–8%), this adds up significantly
- You can emerge from a 5-year Chapter 13 plan owing substantially more than when you started
This is one of the arguments for pursuing adversary discharge proceedings for student loans even while in Chapter 13, or for consulting with a bankruptcy attorney about the structure of your plan. The interest problem is computable — an attorney can show you exactly what the math looks like at the end of your plan, which is information you need to make an informed decision.
The Emotional Reality of Watching a Balance Grow
I want to acknowledge something directly: watching a balance grow while you’re legally prevented from making payments is psychologically brutal. It feels like you’re doing something wrong by not paying. It triggers shame. It looks like the problem is getting worse while you’re supposed to be getting help.
That feeling is real, but the frame is distorted. The automatic stay is not trapping you in debt — it’s protecting you from collection while you reorganize. The interest that accrues during a typical Chapter 7 case (a few thousand dollars at most for most borrowers) is almost always smaller than the wage garnishment you were facing, the lawsuits being filed against you, or the compounding damage of trying to service unaffordable debt without any legal protection.
Never do this: Don’t cash out a retirement account to pay down student loan interest that accrued during the stay. The tax penalties, early withdrawal fees, and long-term opportunity cost make that one of the most expensive financial moves you can make. Protect your retirement — always.
Key Takeaways
- The automatic stay stops collection activity and required payments — it does NOT stop interest from accruing
- In Chapter 7 (3–6 months), accrual is limited and potentially irrelevant if you pursue discharge
- In Chapter 13 (3–5 years), interest can grow significantly — this is a real problem worth addressing with a bankruptcy attorney
- 87% of borrowers who pursue student loan discharge in bankruptcy now succeed — this is the most important number in this conversation
- Only 7,293 out of 3+ million eligible borrowers even tried to get their student loans discharged — most leave this option completely on the table
- The 2022 DOJ guidance made the discharge process significantly more accessible
Before You Decide: Debt decisions made under stress often backfire. Take the Your Brain on Debt quiz to understand how fear and shame may be affecting your thinking before you commit to any path.
The Bottom Line
Yes, interest keeps accruing on your student loans during the bankruptcy stay. For Chapter 7 filers, it’s a few months of growth that disappears entirely if you pursue discharge — and you have an 87% chance of succeeding if you try. For Chapter 13 filers, the multi-year accrual is a genuine financial problem that deserves an honest conversation with your attorney about whether to pursue discharge. The math of interest accruing during the stay is answerable. The bigger question — whether you’re pursuing the one option that could make all of it irrelevant — is the one most people never ask.
Going deeper: If you’re in bankruptcy or considering it, my Chapter 7 Bankruptcy Complete Guide covers the full automatic stay mechanics, what to expect at each stage, and how the discharge process actually works — including the adversary proceeding for student loans.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
Does the bankruptcy automatic stay completely stop student loan interest?
No. The automatic stay under 11 U.S.C. § 362 stops collection activity, communications, wage garnishment, and required payments — but interest continues to accrue on student loan balances throughout the bankruptcy case. The balance grows even while you’re legally protected from having to make payments.
How much interest will accrue on my student loans during Chapter 7 bankruptcy?
Chapter 7 typically concludes in 3–6 months. On a $50,000 student loan balance at 7% annual interest, you’d accrue roughly $1,750–$3,500 during the case. If you pursue and win discharge (87% success rate for those who try), all of that accrued interest is eliminated along with the principal. If your loans survive bankruptcy without a discharge attempt, you exit owing the original balance plus that accrued interest.
Why can’t I make student loan payments during bankruptcy?
You’re generally not required to make payments during the stay, but you’re typically not prohibited from making voluntary payments if you choose to and your bankruptcy trustee permits it. However, making voluntary payments on student loans while in bankruptcy can be complicated — some trustees view it as preferential treatment of one creditor over others. Ask your bankruptcy attorney before making any payments during the case.
What is the 87% student loan discharge success rate based on?
A 2025 study by law professor Jason Iuliano (University of Utah, S.J. Quinney College of Law), published in the American Bankruptcy Law Journal, analyzed 652 bankruptcy cases from October 2022 to November 2023 that included adversary proceedings for student loan discharge. 87% of those borrowers succeeded in eliminating most or all of their student loans — up from 61% in 2017 and roughly 40% in 2007. The improvement is largely attributed to the November 2022 DOJ/Department of Education guidance that simplified and standardized the discharge process.
Does student loan interest keep accruing differently during Chapter 13 vs. Chapter 7?
Yes — and the difference is significant. In Chapter 7, interest accrues for 3–6 months. In Chapter 13, it accrues for 3–5 years. Because Chapter 13 plans often allocate little or no payments to student loans (which are treated as unsecured non-priority debt), borrowers can emerge from a completed Chapter 13 plan owing substantially more in student loans than when they filed. This makes the interest accrual question much more serious for Chapter 13 filers, and it’s one of the reasons consulting with a bankruptcy attorney about adversary proceedings makes sense regardless of which chapter you filed.
Still hearing that student loans can never be wiped out in bankruptcy? That’s a myth — see what actually changed in 2022 and who qualifies now.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



