

Part of the Chapter 7 Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
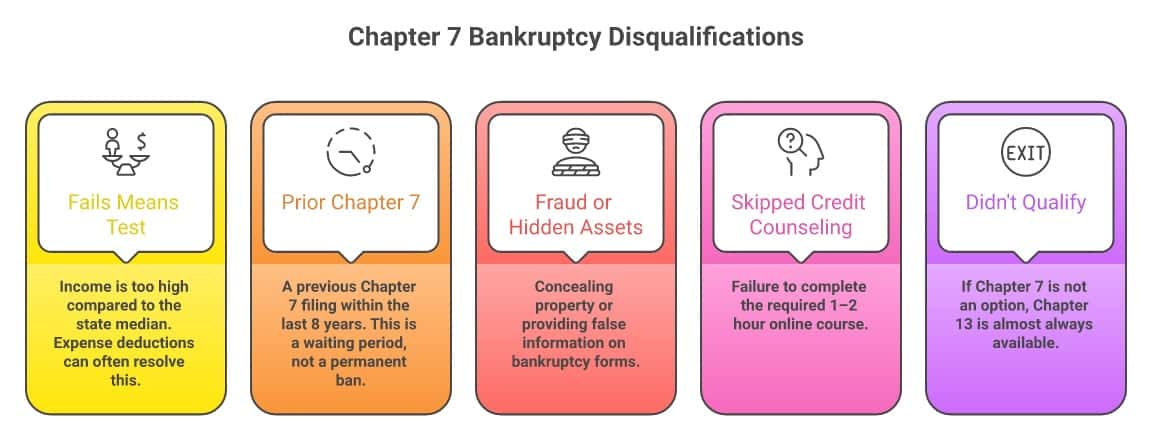
Quick Answer: Most people who fear they’re disqualified from filing bankruptcy aren’t. The real disqualifiers for Chapter 7 are narrow: failing the means test (income too high), a prior Chapter 7 discharge within 8 years, documented fraud, or skipping the required credit counseling course. If your income is too high for Chapter 7, Chapter 13 is usually still available. The fear of being disqualified keeps more people from getting relief than the actual disqualifiers do.
Expert Context: I filed bankruptcy in 1990 when my real estate business failed. I’ve spent the decades since helping people understand their debt options — including the ones that overwhelming debt and fear prevent them from looking at clearly.
The question “what disqualifies you from filing bankruptcy” is almost always asked by someone afraid they won’t qualify. And underneath that fear is usually a deeper one: that they’re stuck, that there’s no way out, that every door is closed.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Let me give you the short version first: the disqualifiers for Chapter 7 bankruptcy are narrower than you’ve been led to believe. The law is designed to give people a fresh start. The barriers are real but specific — and most people who need bankruptcy can get it.
The Main Chapter 7 Disqualifiers
The Means Test: The One Real Hurdle for Most People
Chapter 7 requires you to pass the means test — a calculation that compares your average monthly income over the past six months to the median income for a household of your size in your state. If your income is below the median, you automatically qualify. No further analysis needed.
If your income is above the median, you move to the second part of the test, which looks at your disposable income after allowed expenses — housing, car payments, food, healthcare, and others defined by IRS standards. Many people who initially appear to “fail” the first part of the means test pass the second part after deducting these allowable expenses.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Math Works in Your Favor More Often Than You Think: The means test was designed to catch people with genuine ability to repay — not people who are truly overwhelmed. If you have high expenses relative to your income (medical bills, high rent, dependents), those deductions often bring your disposable income well below the threshold.
What happens if you fail both parts of the means test? You can’t file Chapter 7 — but Chapter 13 is almost always still available. Chapter 13 reorganizes your debt into a 3–5 year repayment plan. It’s not the instant fresh start of Chapter 7, but it still stops collections, stops wage garnishment, and gives you a structured path forward.
Free Tool — Bankruptcy Means Test: Wondering if you qualify for Chapter 7 bankruptcy? The free Bankruptcy Means Test checks eligibility based on your state, household size, and income — including state exemptions. Check My Eligibility →
Prior Bankruptcy Discharge: Timing, Not Permanent Disqualification
If you received a Chapter 7 discharge in the past, you can’t get another Chapter 7 discharge for 8 years from the date of that previous filing. The waiting periods for all combinations:
- Chapter 7 → Chapter 7: 8 years from prior filing date
- Chapter 13 → Chapter 7: 6 years (with exceptions if you paid most unsecured debt)
- Chapter 7 → Chapter 13: 4 years
- Chapter 13 → Chapter 13: 2 years
Notice what these are: waiting periods, not permanent bans. If you’re outside those windows, a prior filing doesn’t disqualify you. And even inside the window, Chapter 13 may still be available depending on your situation.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Fraudulent Transfers: The One That Actually Matters
This is the disqualifier that’s genuinely serious, and it’s the one most people worried about disqualification aren’t actually doing. Fraudulent transfers — moving assets to family members to hide them from creditors, running up luxury charges right before filing, destroying financial records — these can get your case dismissed and could result in criminal charges.
Specific Thresholds to Know: Luxury purchases over $725 on a single creditor within 90 days of filing are presumed fraudulent. Cash advances over $1,000 within 70 days of filing are presumed fraudulent. These are rebuttable presumptions — you can explain them — but they create scrutiny. Don’t make major purchases in the months before you file.
If you haven’t concealed assets or lied on financial forms, fraud isn’t your disqualifier. Most people who ask “what disqualifies me?” are asking out of fear, not because they’ve done anything wrong.
The Credit Counseling Requirement: Not Actually a Barrier
Federal law requires completing an approved credit counseling course within 180 days before filing. The course typically takes one to two hours and can be done online for $15 to $50, with fee waivers available for low-income filers.
This requirement disqualifies almost no one who’s serious about filing. It’s a procedural step, not a substantive barrier.
What the Fear of Disqualification Actually Costs You
Here’s what I’ve observed over decades of helping people with debt: the fear of being disqualified keeps more people from getting relief than the actual disqualifiers do. People assume they earn too much. They assume a prior hardship disqualified them permanently. They assume the system isn’t designed for people like them.
The question “can I even file?” is usually asked by someone who needs to file but is scared to find out the answer.— Steve Rhode
That fear has a real cost. A Federal Reserve study found that people who file bankruptcy recover financially faster than people who avoid filing and continue to struggle. The cost of delaying shows up in credit damage from ongoing missed payments, in garnished wages, and in retirement accounts drained to pay unsecured debt that bankruptcy would have discharged.
The way to find out whether you qualify is to spend an hour with a bankruptcy attorney — many offer free consultations. The means test calculation is specific to your income, household size, and state. No article (including this one) can tell you definitively whether you pass without those numbers in hand.
Don’t Rule Yourself Out Before Talking to an Attorney: I have seen people assume they earn too much, own too much, or did something that would block them — and in case after case, those assumptions were wrong. A good bankruptcy attorney knows the deductions, exemptions, and strategies that don’t show up in a Google search. You might be surprised what a skilled attorney can find when they look at your actual numbers. Get facts. Not assumptions.
Key Takeaways
- The Chapter 7 means test is the main hurdle — but most people who genuinely need relief pass it after allowable expense deductions
- Prior bankruptcy creates waiting periods, not permanent disqualification
- Fraud is the only disqualifier that’s truly serious — it only applies if you’ve actually hidden assets or lied on forms
- The credit counseling requirement is a 1–2 hour online course, not a substantive barrier
- If you don’t qualify for Chapter 7, Chapter 13 is almost always still available
- Fear of disqualification keeps more people from getting help than actual disqualifiers do
- Never assume you don’t qualify — a good bankruptcy attorney can often find exemptions and deductions that change the math entirely
Frequently Asked Questions
What income is too high to file Chapter 7 bankruptcy?
There’s no single dollar amount — it depends on your state, household size, and allowable expense deductions. The means test compares your average monthly income over the past six months to the median for your state and household size. Many people who exceed the median still pass after the second-stage deduction of allowed expenses. A bankruptcy attorney can run this calculation for your specific situation, often in a free consultation.
Can I refile bankruptcy if I was denied?
It depends on why you were denied. If your case was dismissed for failing the means test, you can refile if your financial situation changes or switch to Chapter 13. If dismissed for fraud or abuse, there may be a 180-day bar on refiling. A voluntary dismissal and refiling within 12 months limits the automatic stay to 30 days. If there were two dismissals in 12 months, you may not get an automatic stay without court approval. An attorney can assess the specific timing in your case.
What happens if you don’t pass the means test?
Chapter 13 bankruptcy is usually still available. Chapter 13 reorganizes your debt into a 3–5 year repayment plan based on what you can afford to pay. It still stops wage garnishment and collection activity, still protects your home from foreclosure if you’re behind, and still discharges remaining eligible debt at the end of the plan. It requires more commitment than Chapter 7 — the multi-year repayment plan has a roughly 30–35% completion rate — but it’s a real path for people who don’t qualify for Chapter 7.
Does bankruptcy disqualify you from getting a job?
Federal law prohibits government employers from discriminating in hiring based on bankruptcy. Private employers are not covered by the same prohibition, and some financial services roles may scrutinize bankruptcy history. That said, ongoing debt distress — garnishments, judgments, unresolved delinquencies — can create its own employment complications. Most people find that resolving their financial situation, even through bankruptcy, does less long-term damage than years of unresolved debt.
Can you file bankruptcy if you own a home?
Yes — owning a home doesn’t disqualify you from filing bankruptcy. Whether you keep the home depends on your state’s homestead exemption, how much equity you have, and whether you’re current on the mortgage. In most Chapter 7 cases with modest equity, people keep their home. In Chapter 13, the home is generally protected as long as you stay current through the repayment plan. Homestead exemptions vary significantly by state, which is another reason to consult a local bankruptcy attorney.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



