

Quick Answer: Debt settlement fees are regulated by federal law — specifically the FTC’s Telemarketing Sales Rule (16 CFR § 310.4), which bans all upfront fees before a debt is actually settled. Companies can only charge you after a settlement has been reached AND you’ve made at least one payment toward it. If a debt settlement company is charging you fees before that point, what they’re doing is illegal. There is no universal “fair” benchmark for the fee percentage itself — typical ranges run 15–25% of either enrolled debt or settled amount — but the timing and structure of those fees is strictly regulated.
Expert Context: I ran a credit counseling organization from 1994, and I watched debt settlement companies evolve from a fringe practice into a massive marketing machine. I’ve seen the fee structures from the inside — how companies justify them, how they bury them in contracts, and how clients end up paying more than they expected. The advance fee ban didn’t exist when I was running my org, and the damage that caused to consumers was significant. I know exactly what “fair” looks like in this space — and what doesn’t.
This question came through the Ask Steve chat — and it’s one I hear constantly from people who’ve already signed up with a debt settlement company and are starting to notice fees they didn’t fully understand when they enrolled.
The Question That Came In:
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
“I’m working with a debt settlement company and they’re charging me fees every month. I was told they were ‘processing fees’ and ‘maintenance fees’ — but my debts haven’t been settled yet. I thought the fees were part of the service. Are these fees fair?”
What makes this tricky is that the word “fair” has two different answers: legally, charging fees before settlement is not just unfair — it’s illegal. Practically, consumers get confused because companies disguise these fees under innocent-sounding names.
I want to give you a direct answer here, because a lot of debt settlement marketing obscures this deliberately: the law is actually quite clear on this.
Based on CFPB complaint narratives, fee structure confusion is one of the most frequently reported issues consumers face with debt settlement companies — right alongside settlements that never materialize and credit damage that lasted longer than promised.
What the Law Says About Debt Settlement Fees
The FTC’s Telemarketing Sales Rule (16 CFR § 310.4(a)(5)) includes a complete advance fee ban for debt relief services sold via telemarketing — which covers virtually all debt settlement companies.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Under this rule, a debt settlement company cannot collect any fee from you until:
- A settlement has been reached on a specific debt
- The settlement amount and terms are in writing
- You have made at least one payment toward the settled debt
This isn’t a disclosure requirement. It’s a ban. Companies that charge monthly “maintenance fees,” “processing fees,” or “account fees” before any debt has been settled are in violation of federal law.
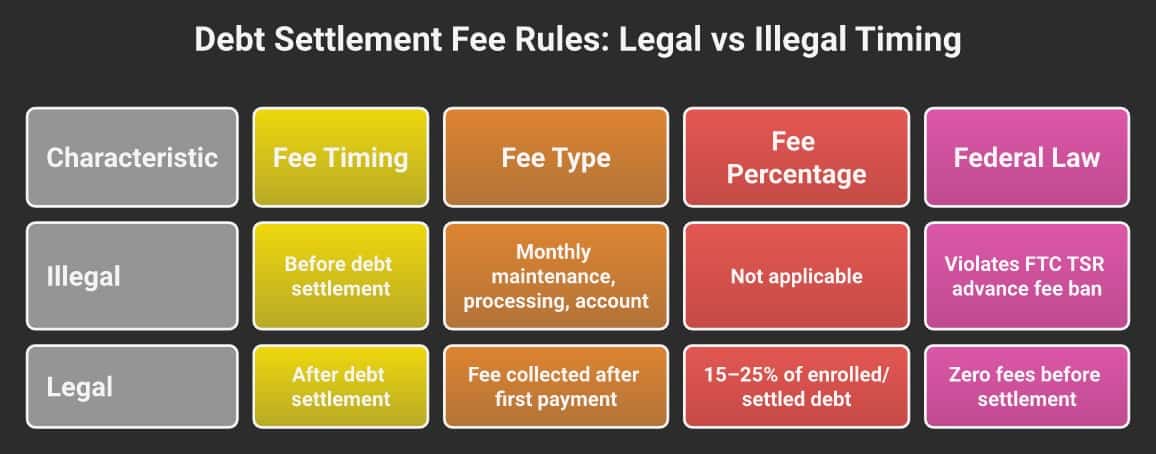
What “Before Settlement” Fees Look Like in Practice: Companies often rename advance fees to obscure what they are. “Monthly program fees,” “account management fees,” “escrow account fees,” and “processing fees” charged before any debt is settled are almost always advance fees by another name. If a debt hasn’t been settled and you’ve paid money to the company — not to a creditor — that pattern warrants scrutiny.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
What “Fair” Actually Means on the Fee Percentage
Federal law regulates the timing of fees — not the percentage. Once a settlement has been reached and you’ve made your first payment, companies can charge whatever their contract specifies. That’s where “fair” gets complicated.
Here’s what I’ve seen and what the industry actually charges:
- 15–20% of enrolled debt: Most common structure — calculated on the total amount you enrolled when you signed up, regardless of how much actually gets settled. For context on what creditors actually accept as settlement amounts, that’s a separate calculation from what the company charges you
- 20–25% of settled amount: Less common but arguably more aligned with actual results — you pay a percentage of what was actually reduced
- Hybrid models: Some companies charge a combination — a smaller percentage on enrolled debt plus a percentage on the amount saved
The enrolled-debt structure deserves scrutiny: if you enroll $30,000 in debt and the fee is 20% of enrolled debt, you owe $6,000 in fees regardless of whether the company settles $30,000 or $15,000 or $5,000. The company’s fee isn’t tied to their performance.
Common Misconception: “Monthly fees are just part of the service — all companies charge them.”
The Reality: Legitimate debt settlement operations don’t charge monthly fees before settling your debts. The advance fee ban exists specifically because pre-settlement fees harm consumers — they drain money that could go toward settlements, and they benefit the company regardless of outcomes. If a company is charging you monthly before settling anything, that’s a regulatory violation, not standard industry practice.
My Take on Debt Settlement Fee Structures
Here’s the uncomfortable truth: the fee structure I’ve described — even when fully legal — is often not in your best interest.
When you enroll in debt settlement, you’re typically told to stop making payments to creditors and instead deposit money into a dedicated account. While that account builds, your credit takes damage, your balances grow with late fees and interest, and creditors may sue you. The company’s fee comes out before you see any settlement money.
By the time everything resolves, your “settlement” may save less than advertised once you factor in the fees, the interest that accrued during the program, and any tax consequences on forgiven debt. That’s not to say settlement never works — it does, in the right circumstances. But “fair” fees in an unfair structure still leave many people worse off than they expected.
Settlement is most viable when you already have cash available to settle quickly, not when you’re waiting years for an account to build while paying fees.
The scam isn’t always the settlement itself — it’s the marketing that convinces people settlement is the right tool when it isn’t.— Steve Rhode
What to Do If You’re Already Enrolled
- Review your contract for fee language — specifically what triggers fee collection. If fees are not tied explicitly to settlement completion and first payment, that’s worth questioning
- Check your account statement — if you’ve paid fees and no debts have been settled, document those payments with dates and amounts
- File a complaint — the FTC complaint form and your CFPB complaint submission are both appropriate. Most state attorneys general also have consumer complaint divisions
- Consult a consumer attorney — if you’ve paid fees before settlement, you may have claims under the FTC Act, state consumer protection laws, or UDAP statutes
- Consider your options — use the Find Your Path quiz to evaluate whether debt settlement is still the right approach for your situation, or whether alternatives like bankruptcy or a debt management plan would serve your future better
Before Signing Any Debt Relief Contract: Run it through the Contract Decoder first. It flags exactly the kind of fee language that confuses people in this type of situation — and it’s free.
No Article Replaces an Attorney Licensed in Your State: What I’ve covered here is educational — it gives you the framework to understand your rights, but it is not legal advice and cannot account for the specifics of your situation. If you’ve been charged advance fees by a debt settlement company, you need someone qualified to evaluate your actual case under your state’s laws.
How to find a consumer law attorney who handles these cases:
- NACA — National Association of Consumer Advocates — The best starting point for UDAP and FTC Act cases. Member attorneys specialize in consumer protection law and many take cases on contingency.
- Your state bar’s lawyer referral service — Search “[your state] bar association lawyer referral.” Most offer a low-cost initial consultation.
- LawHelp.org — Free and reduced-cost legal aid organized by state and issue.
- HelpIsHere.org — Free or low-cost legal help for seniors and people with disabilities.
Have a similar question? Every situation is different. Ask Steve directly in the chat — describe your specific situation and I’ll help you think through your options.
The Bottom Line
Debt settlement fees are federally regulated under the FTC’s Telemarketing Sales Rule: no fees can be collected before a specific debt is settled and you’ve made your first payment. “Monthly maintenance fees,” “processing fees,” or any other charge collected before settlement is a violation of federal law — not standard practice. The fee percentage itself (typically 15–25% of enrolled or settled debt) is not federally regulated, but the enrolled-debt model means you pay regardless of outcomes. If you’ve already been charged pre-settlement fees, document them and file complaints with the FTC, CFPB, and your state AG — and consult a consumer protection attorney about your options.
Frequently Asked Questions
Are debt settlement fees tax deductible?
Generally, no — debt settlement fees paid to a for-profit company are not tax deductible for consumers. The forgiven debt itself may create a taxable event (the creditor may issue a Form 1099-C), which can add an unexpected tax bill. Consult a tax professional about your specific situation.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
Can I negotiate debt settlement myself without paying fees?
Yes. You can contact creditors directly to negotiate settlements — no company required. Many creditors will negotiate directly, especially on accounts that are significantly past due. The risk of DIY settlement is mainly timing and knowing what to say, but the process itself doesn’t require a middleman. If you want help without the fees, a nonprofit credit counseling agency through the NFCC can provide guidance at low or no cost.
What happens if I stop paying a debt settlement company?
If you stop depositing into your settlement account, the company may close your program. Any money already in your account should be returned to you (minus any fees already collected in compliance with the advance fee rule). Check your contract for cancellation terms and confirm in writing that any remaining balance will be refunded. If debts haven’t been settled, you’ll likely face collection activity from the creditors directly.
How do I tell if a debt settlement fee is legal?
The test is simple: has a specific debt been settled, and have you made at least one payment toward that settlement? If the answer to either is no, any fee charged before that point is almost certainly in violation of the FTC’s advance fee ban. Legitimate companies structure fees as a percentage of settlement amounts collected — not monthly maintenance charges before any settlement occurs.
Are debt settlement fees worth it?
That depends entirely on your situation. Settlement makes the most sense when you have a lump sum available and need to resolve specific accounts quickly. It makes the least sense when you’re enrolling in a 3–4 year program and paying fees on enrolled debt that may never fully settle. Before committing, use the Find Your Path quiz to compare your options — including bankruptcy, which often resolves more debt faster with less total cost than settlement.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



