

Quick Answer: If you are simultaneously supporting aging parents and raising children, you are part of the sandwich generation — and the standard debt advice does not apply to you. A 2023 Urban Institute study found that caregiving mothers lose an average of $295,000 in lifetime earnings and retirement income. Pew Research reports that 23% of American adults are in this position. A peer-reviewed study in the Journal of the American Geriatrics Society found that 23.5% of sandwich generation caregivers report substantial financial difficulties — nearly double the rate of other caregivers. Your debt is not caused by overspending. It is caused by a structural squeeze that no budget can fix. Here are your actual options.
Expert Context: I founded Myvesta, a credit counseling organization, in 1994 and ran it for over a decade with 70 employees — including staff psychologists, lawyers, and CPAs. Sandwich generation clients walked through our doors constantly: people who made good money but were drowning because they were paying for Mom’s home care, their kids’ daycare, and their own mortgage at the same time. The standard advice I was trained to give them — “let’s build a budget” — failed every single time. The math was broken before they sat down. This post is the advice I wish I had been equipped to give them.
You are not overspending. You are not irresponsible. You are caught between two generations who need you, and the math does not work. That is not a character flaw. That is a structural financial crisis affecting 23% of American adults — roughly 60 million people — and almost nobody in the debt advice world is talking about it honestly.
About This Research
This analysis draws on 7 primary sources including the Urban Institute’s 2023 report on lifetime caregiving costs, a peer-reviewed study published in the Journal of the American Geriatrics Society, the Pew Research Center’s sandwich generation survey, the 2025 Caregiving in the U.S. report by AARP and the National Alliance for Caregiving, and data from Health Affairs on the $107 billion annual earnings loss among American caregivers. All statistics are linked to their original sources below.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Key Terms Defined
Sandwich Generation: Adults simultaneously providing care or financial support to aging parents (age 65+) AND raising or financially supporting their own children. The term was coined by social worker Dorothy Miller in 1981. Pew Research Center defines it as adults with a parent 65+ who are raising a minor child or financially supporting an adult child.
Filial Responsibility Laws: State statutes that can legally obligate adult children to pay for an indigent parent’s basic needs, including medical bills and nursing home care. Currently on the books in 24 states, though rarely enforced.
Judgment Proof: A legal status where a person’s income and assets are protected from creditor collection — meaning even if a creditor wins a lawsuit, they cannot collect. Many sandwich generation caregivers are effectively judgment proof and do not know it.
The Scale of the Crisis: This Is Not a Niche Problem
According to Pew Research Center’s 2022 survey, about 23% of U.S. adults — roughly one in four — are part of the sandwich generation. Among Americans in their 40s, that number jumps to 54%. More than half of people in their peak earning years are financially squeezed from both directions.
The 2025 Caregiving in the U.S. report from AARP and the National Alliance for Caregiving found that 63 million Americans now serve as caregivers — a 50% increase since 2015. Twenty-nine percent of those caregivers are sandwich generation, supporting both children and adults simultaneously.
And it is getting worse. The population is aging. Adult children are staying financially dependent longer. Healthcare costs are rising. The math is breaking for more families every year.
Finding 1: Caregiving Costs $295,000 Over a Lifetime — and Nobody Tells You Before You Start
The Urban Institute’s 2023 study, funded by the U.S. Department of Labor’s Women’s Bureau, used dynamic microsimulation to calculate the lifetime employment-related cost of family caregiving. The findings are devastating:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
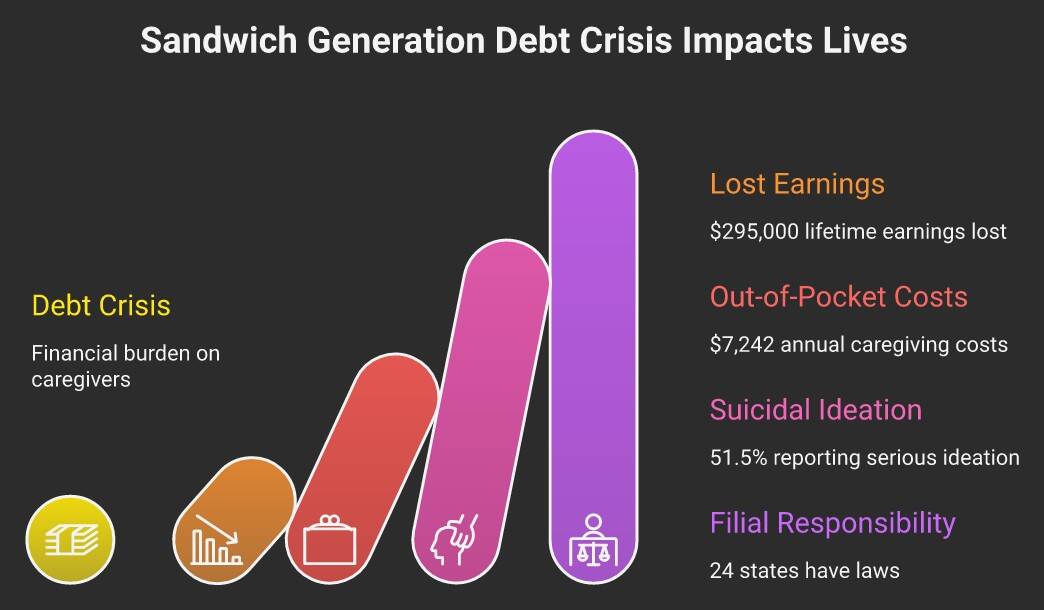
- Average lifetime cost: $295,000 in lost earnings and retirement income
- For college-educated mothers: $420,000
- Lost lifetime earnings alone: $237,000 (80% of total cost)
- Lost retirement income from Social Security and employer plans: $58,000 (20% of total cost)
- Less-educated mothers lose 26% of their potential lifetime earnings to caregiving
Read that last number again. If you did not finish high school and you are providing family care, you are losing more than a quarter of everything you would have earned over your entire life.
And this study only measures employment-related costs. It does not include the $7,242 per year in out-of-pocket expenses that AARP’s caregiving cost study found caregivers spend — money that comes directly out of their household budget. That is $36,000 over a five-year caregiving period, on top of the lost earnings.
The Dogma: “Sandwich generation caregivers just need a better budget. Track your spending, cut unnecessary expenses, and you’ll get ahead.”
What the Research Shows: The Urban Institute found that caregivers lose $295,000 over a lifetime not because of spending habits, but because caregiving forces them to reduce work hours, miss promotions, take lower-paying jobs, or leave the workforce entirely. You cannot budget your way out of a $295,000 structural earnings loss. The math is broken before you open the spreadsheet.
Finding 2: The Emotional Toll Is Worse Than the Financial One
A 2023 peer-reviewed study published in the Journal of the American Geriatrics Society, analyzing data from the National Study of Caregiving, found that sandwich generation caregivers experience dramatically worse outcomes than other caregivers:
- 23.5% report substantial financial difficulties — nearly double the 12.2% rate among non-sandwich caregivers
- 44.1% experience substantial emotional difficulties (vs. 32.2%)
- CDC data cited in the study found that 51.5% of sandwich generation caregivers endorsed serious past-month suicidal ideation
Let me say that plainly: more than half of sandwich generation caregivers have had serious thoughts about ending their lives in the past month.
If you are in crisis: Call or text 988 (Suicide and Crisis Lifeline). You can also text HOME to 741741 (Crisis Text Line). These services are free, confidential, and available 24/7. Financial problems have solutions — even when it does not feel that way.
When I ran Myvesta, our research screened 136 people dealing with serious debt and found that 49% screened positive for depression symptoms on the CES-D — an elevation over the general population best stated as a range of roughly two to five times, not a single multiplier, after correcting a comparison I had wrong for years. The sandwich generation data is even worse. And this is why “just budget better” is not just unhelpful advice — it is dangerous advice. You are telling a person who may be experiencing suicidal ideation to try harder. That is not a financial plan. That is cruelty dressed up as responsibility.
Debt is 90% emotional and 10% financial math. For the sandwich generation, even the 10% that is math is rigged against you.— Steve Rhode
Finding 3: You May Be Legally Required to Pay Your Parents’ Bills — in 24 States
Here is something almost nobody in the debt advice world talks about: 24 states have filial responsibility laws that can legally require adult children to pay for an indigent parent’s care.
These states are: Alaska, Arkansas, California, Connecticut, Delaware, Georgia, Indiana, Kentucky, Louisiana, Massachusetts, Mississippi, Nevada, New Jersey, North Carolina, North Dakota, Ohio, Oregon, Pennsylvania, Rhode Island, South Dakota, Tennessee, Vermont, Virginia, and West Virginia.
In most states, these laws are rarely enforced because Medicaid typically covers long-term care costs. But when a parent does not qualify for Medicaid — because of pension income, property, or a gap in coverage — nursing homes and creditors can and do come after adult children.
The Pittas Case: In 2012, a Pennsylvania appeals court ordered an adult son to pay his mother’s $93,000 nursing home bill under the state’s filial responsibility law. The mother’s pension prevented her from qualifying for Medicaid. Pennsylvania remains the only state to have actively enforced these laws in the past 25 years — but the statutes are on the books in 23 other states, and a nursing home or collection agency could attempt to use them anywhere they exist.
The practical implication: if you live in one of these 24 states and your parent needs long-term care they cannot afford, you could face a legal obligation on top of the moral one. And this potential liability does not appear on any budget worksheet.
Finding 4: The Standard Debt Advice Is Built for a Different Person
Every major personal finance framework — the debt snowball, the debt avalanche, credit counseling DMPs, debt settlement — assumes a single set of household expenses that can be reduced. They assume that the person in debt controls their own spending.
The sandwich generation caregiver controls almost none of it:
What You Can Control
- Your own discretionary spending
- Some household expenses
- Whether you seek help
What You Cannot Control
- Your parent’s medical costs
- Your children’s basic needs
- Whether your parent qualifies for Medicaid
- Whether your employer offers flexible scheduling
- The $7,242/year in out-of-pocket caregiving costs
- The promotions you miss while caregiving
This is what I mean when I say debt is the symptom, not the problem. The problem is a structural squeeze — two generations of non-negotiable obligations pressing against a single income that was never designed to support three generations. The debt is what is left over when that math breaks.
The Dogma: “You chose to help your parents. That’s admirable, but you need to set boundaries and stop enabling them financially.” (If the problem is an aging parent who is genuinely in debt and won’t stop spending, see what actually helps in that situation.)
What the Research Shows: In 24 states, filial responsibility laws can make this a legal obligation, not a choice. Even where it is not legally required, the academic research shows that the emotional cost of refusing care — guilt, family rupture, watching a parent suffer — produces worse mental health outcomes than the financial strain of providing it. Telling someone to “set boundaries” with a parent who needs daily assistance is not financial advice. It is a fantasy.
Your Actual Options — All of Them
Here is what nobody in the sandwich generation advice space tells you: you have legal tools designed specifically for situations where the math is broken beyond repair. These are not shameful last resorts. They are rational financial instruments.
Option 1: Bankruptcy (The Option Nobody Mentions)
Chapter 7 bankruptcy discharges unsecured debt — credit cards, medical bills, personal loans — in approximately 90 days. Your retirement savings are 100% protected under federal law and the Supreme Court’s 1992 ruling in Patterson v. Shumate.
For a sandwich generation caregiver, bankruptcy does several things that no other option does:
- Eliminates the debt caused by the caregiving squeeze — in 90 days, not 5 years
- Protects your 401(k), IRA, and pension completely
- Stops wage garnishment immediately via the automatic stay
- Frees up income to continue supporting your parent and children without accumulating new debt
- Credit scores typically recover within 2 years — the Federal Reserve research shows bankruptcy filers do better than those who grind through repayment
I filed bankruptcy in 1990 when my real estate business crashed. It was the most painful financial decision of my life — and the best one. I rebuilt everything. The shame I felt was based on myths, not math.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Option 2: Judgment Proof Status (The Option You May Already Have)
If your income comes primarily from Social Security, disability, pensions, or you earn below your state’s garnishment threshold, you may be judgment proof. This means that even if a creditor sues you and wins, they cannot collect anything.
For many sandwich generation caregivers — especially those who have reduced work hours or left the workforce to provide care — judgment proof status is a real possibility. If you are judgment proof, the rational strategy may be to do nothing about unsecured debt and let the statute of limitations run.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Option 3: Debt Settlement (When You Have Some Resources)
If you have accumulated savings or receive a lump sum (tax refund, inheritance, insurance payout), settlement can reduce unsecured debt by 40-60%. Settlement is viable — the scam is not whether creditors settle, it is the predatory marketing by companies that charge fees before settling anything.
Option 4: Credit Counseling / DMP (Know the Real Cost First)
A debt management plan through a nonprofit credit counseling agency reduces interest rates and consolidates payments over 3-5 years. It can work — but you need to know the real cost.
I calculated the retirement opportunity cost of a 5-year DMP: a 35-year-old who pauses $400/month in 401(k) contributions during a DMP loses approximately $247,000 in retirement savings at age 65. For a sandwich generation caregiver who is already losing $295,000 in lifetime earnings to caregiving, adding another $247,000 in lost retirement savings is financially catastrophic.
The Compound Cost for a Sandwich Generation Caregiver:
$295,000 (lifetime caregiving earnings loss, Urban Institute) + $36,000 (5 years of out-of-pocket caregiving costs at $7,242/year, AARP) + $247,000 (retirement opportunity cost of a 5-year DMP) = $578,000 in total lifetime financial damage
Compare that to Chapter 7 bankruptcy: 90 days, $0 retirement loss, debt discharged, income freed up to resume saving immediately.
Option 5: Government Benefits You May Not Know About
- Medicaid for your parent: If your parent qualifies, Medicaid covers long-term care costs and eliminates filial responsibility exposure in most states
- FMLA leave: Up to 12 weeks of unpaid, job-protected leave for caregiving under the Family and Medical Leave Act
- Caregiver tax credits: The Child and Dependent Care Credit and medical expense deductions can reduce your tax burden
- State caregiver support programs: Many states offer respite care, caregiver stipends, and adult day care subsidies through Medicaid waiver programs
- Area Agency on Aging: Free local resource that connects families with elder care services — call 211 or visit eldercare.acl.gov
What This Means for You
If you are reading this and recognizing yourself — supporting a parent, raising children, watching the debt pile up despite working hard and spending carefully — I want you to understand something clearly:
This is not your fault. The math is broken. Caring for two generations on one income was never sustainable without structural support that does not exist in the United States. You are not failing at money management. You are succeeding at an impossible task, and the debt is the collateral damage.
The question is not “how do I budget better.” The question is: which legal and financial tools can I use to protect my future while continuing to care for the people who need me?
Key Takeaways
- 23% of U.S. adults are sandwich generation caregivers — 54% of those in their 40s (Pew Research Center)
- Caregiving mothers lose an average of $295,000 over a lifetime in earnings and retirement income; $420,000 for college-educated women (Urban Institute, 2023)
- 51.5% of sandwich generation caregivers report serious suicidal ideation — this is a mental health crisis, not a budgeting problem (PMC/Journal of the American Geriatrics Society)
- 24 states have filial responsibility laws that can legally obligate you to pay your parents’ care costs
- Bankruptcy protects 100% of retirement savings, discharges unsecured debt in ~90 days, and frees income for ongoing caregiving — making it the strongest option for many sandwich generation caregivers
The Bottom Line
The sandwich generation debt crisis is not caused by overspending — it is caused by a structural squeeze that no budget can fix. The Urban Institute calculates the lifetime cost at $295,000 in lost earnings and retirement income for caregiving mothers, with college-educated women losing $420,000. The AARP and National Alliance for Caregiving report that 25% of all caregivers are taking on debt and 50% report negative financial impact. A peer-reviewed study found that sandwich generation caregivers experience financial hardship at nearly double the rate of other caregivers. If you are in this situation, your debt is not a moral failure — it is a math problem. And the most powerful math tool available to you may be Chapter 7 bankruptcy: 90 days, full retirement protection, and the immediate ability to redirect income toward the people who need you instead of toward creditors who bought your debt for pennies on the dollar.
Frequently Asked Questions
Am I legally required to pay my parents’ medical bills?
It depends on your state. Twenty-four states have filial responsibility laws that can require adult children to pay for an indigent parent’s care. However, these laws are rarely enforced because Medicaid typically covers long-term care. The main risk arises when a parent does not qualify for Medicaid and a nursing home or creditor sues. Pennsylvania is the only state to have actively enforced these laws in the past 25 years. If you live in a filial responsibility state, consult an elder law attorney about your exposure.
Can I file bankruptcy if my debt is from helping my parents?
Yes. Chapter 7 bankruptcy discharges unsecured debt regardless of how it was incurred — including credit card debt used for a parent’s medical bills, personal loans taken to cover caregiving costs, and medical debt from your own care. Your retirement accounts (401(k), IRA, pension) are 100% protected under federal law. The fact that your debt arose from caregiving is not a disqualifying factor; it is one of the strongest cases for why bankruptcy exists.
How much does the average sandwich generation caregiver spend on parents?
According to the AARP’s caregiving cost study, family caregivers spend an average of $7,242 per year out of pocket on caregiving expenses — approximately 26% of their annual income. For caregivers experiencing work conflicts (schedule changes, missed time), the average rises to $10,525 per year. This is on top of the $295,000 in lifetime earnings lost to reduced work hours and missed career advancement that the Urban Institute documented in 2023.
Will my parent’s debt become my responsibility when they die?
Generally, no. A deceased person’s debts are paid from their estate — not from their children’s assets. For a full explanation of exactly why, see Mom or Dad Died With Credit Card Debt: You Probably Don’t Owe It. There are exceptions — joint account holders, co-signers, and spouses in community property states can be liable. In filial responsibility states, a nursing home could theoretically pursue an adult child even after the parent dies. Medicaid can also recover costs from the deceased parent’s estate (including forcing the sale of their home), which can affect any inheritance you expected. Do not let debt collectors pressure you into paying debts that are not legally yours.
What should I do first if I am drowning in sandwich generation debt?
Three steps, in this order: (1) Talk to your doctor about your mental health — the research shows that sandwich generation caregivers experience depression and suicidal ideation at alarming rates, and you cannot make good financial decisions while in crisis. (2) Determine whether you are judgment proof — if your income is below your state’s garnishment threshold, you may not need to do anything about unsecured debt right now. (3) Consult a bankruptcy attorney for a free evaluation — not because bankruptcy is always the answer, but because understanding your full range of options is the only way to make an informed decision. Do not start a debt management plan or settlement program without first understanding the retirement opportunity cost.
Sources and Methodology
This post draws on the following primary sources:
- Johnson, R.W., Smith, K.E., Butrica, B.A. — Lifetime Employment-Related Costs to Women of Providing Family Care (Urban Institute, February 2023) — Primary source for $295,000 lifetime caregiving cost, education and race breakdowns, retirement income losses. Funded by U.S. Department of Labor, Women’s Bureau.
- National Study of Caregiving — A National Profile of Sandwich Generation Caregivers (Journal of the American Geriatrics Society, 2023) — Peer-reviewed study providing financial hardship rates (23.5%), emotional difficulty rates (44.1%), and CDC suicidal ideation data (51.5%) among sandwich generation caregivers.
- Pew Research Center — More Than Half of Americans in Their 40s Are Sandwiched (April 2022) — Authoritative demographic data: 23% of U.S. adults in sandwich generation, 54% of those in their 40s, breakdowns by age, education, and income.
- AARP and National Alliance for Caregiving — Caregiving in the U.S. 2025 — 63 million caregivers (50% increase since 2015), 29% sandwich generation, 25% taking on debt, 50% negative financial impact.
- AARP — Family Caregivers Experience High Out-of-Pocket Costs (2021) — $7,242 average annual out-of-pocket cost, 26% of caregiver income, racial and age disparities.
- Health Affairs — Work-Related Opportunity Costs of Providing Unpaid Family Care (2020) — $107 billion annual lost earnings among U.S. family caregivers; 80% from reduced labor force participation.
- Nolo — Filial Responsibility: When Children Must Pay Their Parents Medical Debt (updated 2025) — Comprehensive state-by-state guide to filial responsibility laws; 24 states listed; enforcement conditions and defenses.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



