

Quick Answer: Money fights are the second leading cause of divorce — but the fights aren’t really about money. Research from 100 married couples tracked over 15 days found that money conflicts last twice as long as other disagreements, are more likely to recur, and both partners describe them as more threatening to the relationship. A University of Michigan study explains why: savers and spenders are biologically drawn to each other, then fight about money for decades without understanding that the real conflict is about control, security, and identity — not the credit card bill.
Expert Context: At Myvesta, the credit counseling organization I founded in 1994, we had psychologists on staff specifically because we couldn’t separate the debt from the relationship. Couples would come in for a debt management plan and leave in marriage counseling. After watching this pattern hundreds of times — the saver screaming at the spender, the spender hiding purchases, both convinced the other was the problem — I stopped seeing debt as the issue. Debt is what’s left over when the math is broken. But in a marriage, the math breaks because two people with opposite money personalities are trying to share one financial life without understanding each other.
If debt is tearing your relationship apart, the worst thing you can do is have another conversation about the budget. The research says the problem isn’t the numbers — it’s that you and your partner are speaking different money languages and nobody taught either of you to translate.
About This Research
This analysis draws on peer-reviewed research from the Journal of Family Psychology, the Journal of Financial Therapy, Journal of Financial Counseling and Planning, University of Michigan research on tightwad-spendthrift attraction, original Olson & Rick (2018) research on couples managing debt together, Bankrate’s 2025 Financial Infidelity Survey, Debt.com’s 2025 Divorce Survey, and 30 years of direct observation from my work at Myvesta and GetOutOfDebt.org.
Key Terms Defined
Tightwad-Spendthrift Scale: A research tool developed by Scott Rick at the University of Michigan that measures emotional reactions to spending — not how much you spend, but how spending makes you feel. Tightwads feel pain when spending; spendthrifts don’t feel enough pain. Both are unhappy with their own tendencies.
Financial Infidelity: Keeping financial secrets from a partner — hidden debt, secret accounts, concealed spending. Bankrate’s 2025 survey found 40% of Americans in relationships have committed it. 43% of adults consider it at least as harmful as physical infidelity.
Debt Concordance: Whether partners agree on how much debt they have. Research shows couples who agree on their debt levels report significantly higher relationship satisfaction — even when the debt itself is high. Agreement matters more than the amount.
Savers Attract Spenders — That’s Biology, Not a Character Flaw
The most important finding in relationship finance research is one most couples never learn: you were drawn to your partner partly BECAUSE you handle money differently.
Scott Rick and colleagues at the University of Michigan surveyed over 1,000 married and unmarried adults across three studies and found that tightwads and spendthrifts systematically attract each other. The more dissatisfied someone is with their own spending tendencies, the more attracted they are to someone with the opposite approach.
Read that again. The more unhappy you are about your own relationship with money, the more you seek out someone who handles it the opposite way.
A tightwad who hates how painful it is to spend is drawn to someone who spends freely — because that ease looks like freedom. A spendthrift who feels guilty about overspending is drawn to someone disciplined — because that control looks like security. Each sees in the other what they wish they had in themselves.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
But here’s the twist the research also found: the more spouses differ on the tightwad-spendthrift dimension, the more they argue about money and the less satisfied they are with the marriage. The very thing that attracted you becomes the thing that drives you apart.
Savers attract spenders — that’s biology, not a character flaw. What couples need is understanding and awareness, not anger and guilt.— Steve Rhode
I watched this at Myvesta for over a decade. Couples would come in and the saver would say “she won’t stop spending” and the spender would say “he controls every dollar.” They were both right. And they were both missing the point — neither one’s relationship with money was “correct.” They were just different, and nobody had ever shown them how to work with that difference instead of against it.
Money Fights Are Different From Every Other Kind of Fight
Here’s something the research confirms that every married person already knows: money arguments hit different.
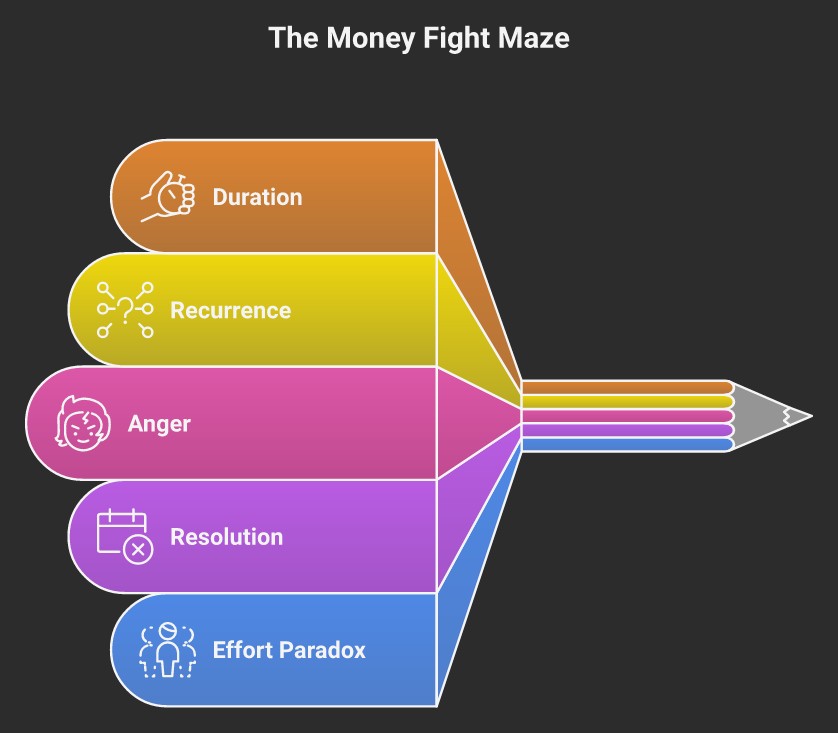
A study published in Family Relations tracked 100 married couples over 15 days, recording every conflict in real time. Money fights made up about 19% of all arguments — not even the most frequent topic (children topped the list). But money fights were categorically more destructive:
- Duration: Money arguments lasted an average of 30.6 minutes — twice as long as non-money conflicts (15.3 minutes)
- Recurrence: 60% of husbands said money fights were about recurring, unsolved problems (vs. 48% for other topics)
- Emotional intensity: Husbands displayed significantly more anger during money conflicts. Both partners showed more depressive behavior — withdrawal, sadness, fear
- Resolution failure: Couples were nearly twice as likely to postpone money discussions rather than resolve them (27.7% postponement vs. 15.5% for other topics)
And the most telling finding: wives used more problem-solving tactics during money fights than any other type of conflict (49.7% vs. 40.5%) — yet the arguments still went unresolved. More effort, worse outcomes. That’s because the conflict isn’t about the numbers. It’s about what the numbers represent.
The Dogma: “If couples just communicated better about their budget, money problems would go away.”
The Reality: Research shows couples already try harder to resolve money fights than any other type of conflict — and still fail. The problem isn’t communication volume. It’s that they’re arguing about the wrong thing. The budget spreadsheet is the battlefield. The actual war is about security, control, identity, and fear.
What You’re Actually Fighting About (It’s Not the Credit Card Bill)
A 2023 study in the Journal of Financial Therapy analyzed what couples actually fight about when they fight about money. The researchers coded over 1,000 Reddit posts about severe financial conflicts AND tracked 481 married couples’ real-time disagreements. The top themes weren’t about numbers:
“Perceived irresponsibility” was the #1 trigger — nearly 40% of all money conflicts. That’s not a budget discussion. That’s one partner calling the other reckless. That’s judgment, shame, and moral superiority wrapped in a dollar sign.
At Myvesta, our psychologists saw this constantly. The saver isn’t really angry about the $200 purchase. They’re terrified of financial insecurity — maybe because they grew up without money, or watched their parents lose everything. The spender isn’t really being “irresponsible.” They’re using money to feel safe, loved, or in control of something — because something else in their life feels out of control.
When I wrote about this in The Path to Happiness and Wealth in 2002, I described money as “an over-the-counter drug” — a legal tool we use to make ourselves feel differently. That applies inside marriages too. One partner medicates with spending. The other medicates with hoarding. Neither understands the other’s prescription because neither understands their own.
The Secret No One Talks About: 40% Hide Money From Their Partner
Bankrate’s 2025 Financial Infidelity Survey found that 40% of Americans in committed relationships have kept a financial secret from their partner. One in three has spent more than their partner would be comfortable with. Nearly a quarter (23%) have hidden debt. And 43% of adults say financial secrecy is at least as damaging as physical infidelity.
Younger couples are worse: 67% of Gen Z and 57% of Millennials have committed financial infidelity, compared to 33% of Boomers.
But here’s what those statistics miss — and what I learned from watching it happen: financial infidelity is almost never about greed. It’s about shame. The spender hides purchases because they know the saver will judge them. The judgment reinforces the shame. The shame drives more hiding. And the hiding destroys the trust that the relationship needs to survive.
Warning: If your partner is hiding significant debt, that is a serious issue — but confrontation without understanding makes it worse. Approach it as “I need to understand what’s happening” rather than “you’ve been lying to me.” The distinction matters. One opens a door. The other slams it.
What the Research Found That Surprised Even Me
Here’s the finding that changes everything: it’s not how much debt you have that predicts relationship satisfaction. It’s whether you agree on how much you have.
A study on debt concordance and relationship quality found that 55% of couples agreed on their outstanding debt — and those couples reported significantly higher relationship satisfaction than the 45% who didn’t agree. The actual dollar amount of debt was not significantly associated with satisfaction. What mattered was agreement.
Concordant couples were also far less likely to argue about money: 38% never argued about finances, compared to 26% of discordant couples.
This confirms what I’ve been telling people for 30 years: debt is not the enemy of your marriage. Secrecy is. A couple with $80,000 in debt who are both on the same page will do better than a couple with $15,000 where one partner doesn’t know about $10,000 of it.
Couples Actually Make BETTER Financial Decisions Together — With One Condition
Here’s the good news that nobody reports. Research by Olson and Rick (2018) found that couples manage debt more optimally when working together than when working individually — but only when they understand each other’s financial confidence.
The key finding: it’s not financial literacy that predicts who should lead the money decisions. It’s financial confidence. The partner who feels more capable and assured about financial decisions tends to make better choices — and when both partners recognize which one has more financial confidence, the couple outperforms individuals.
Financial literacy (knowing the right answers on a test) didn’t predict who took the lead in managing shared finances. Financial confidence (feeling capable of making good decisions) did. And here’s the kicker: couples who did a simple “financial warm-up” exercise — getting to know each other’s financial confidence levels — immediately improved their joint debt management.
Start Here — Together: Take the free Money Personality Quiz — both of you. Not to fix the other person, but to understand each other. When you see your partner’s results next to yours, you’ll understand why you fight about money. The quiz won’t solve the debt, but it will change the conversation from blame to understanding. That’s where real solutions start.
The Dogma: “The partner who knows more about finances should handle the money.”
The Research: Olson and Rick (2018) found that financial literacy does NOT predict who leads household finances or who makes better decisions. Financial confidence — feeling capable, not actually knowing more — is what predicts better outcomes. The partner who “knows” more isn’t necessarily the one who should lead. The partner who feels more capable often makes better calls, even with less technical knowledge.
Free Tool — Money Personality Quiz: Your spending habits are as individual as your debt. The free Money Personality Quiz identifies your money type — and why standard budget advice probably isn't working for you. Discover Your Type →
What to Do About the Debt — Together
Once you understand each other’s money personality and agree on the reality of your debt, you can actually address it. Here are the options — and yes, some of them will surprise you:
Bankruptcy (Yes, Together)
Married couples can file jointly. It eliminates unsecured debt in 90-120 days, protects retirement accounts, and — contrary to what you’ve been told — Federal Reserve research shows filers recover financially within 2-3 years. I filed in 1990. My marriage survived. The debt didn’t.
Debt Management Plan
Structured repayment through a credit counseling agency. Reduces interest rates. Good if the spending behavior is under control. But run the retirement math first — 5 years of payments can cost $400K+ in lost retirement growth.
Address the Spending First
If the debt came from compulsive or emotional spending, eliminating it without addressing the behavior puts you right back here. Read my post on spending addiction and what actually works — and take the Money Personality Quiz together.
Strategic Inaction
If you’re judgment proof (no seizable assets, income below garnishment thresholds), sometimes the best move for the marriage is to stop feeding the debt stress and focus on rebuilding your life together.
Not sure which fits your situation? Take the free Find Your Path quiz together — it walks through your specific numbers. Or ask Steve directly — describe your situation and I’ll help you think through your options as a couple.
Key Takeaways
- Savers and spenders are biologically attracted to each other — then spend decades fighting about money without understanding why (University of Michigan, 1,000+ adults)
- Money fights last twice as long as other arguments and both partners use more problem-solving tactics — yet they still go unresolved because the real conflict is about identity, control, and fear
- It’s not how much debt you have that hurts the marriage — it’s whether you agree on how much you have. Agreement predicts satisfaction; the dollar amount doesn’t.
- Couples who understand each other’s financial confidence make BETTER decisions together than either would alone
- 40% of Americans hide money from their partner — driven by shame, not greed. Confrontation without understanding makes it worse.
- The Money Personality Quiz taken together is the first step — not to fix anyone, but to finally understand each other’s money language
The Bottom Line
If you’re lying awake right now while your partner sleeps, thinking about the debt and wondering whether this marriage can survive it — you’re not alone. Forty-two percent of divorced couples say credit card debt played a role. But here’s what those statistics don’t tell you: the debt isn’t what kills marriages. The silence does. The judgment does. The assumption that your partner’s relationship with money is wrong and yours is right — that’s what kills it. Research shows that couples who simply agree on how much they owe have significantly higher satisfaction than couples with less debt who don’t agree. The path forward isn’t another budget meeting. It’s understanding why you and your partner handle money differently — and recognizing that you chose each other partly because of that difference. Take the Money Personality Quiz together. Not to win an argument, but to finally hear what your partner has been trying to say in a language you didn’t speak. I’ve watched this save marriages. It starts with understanding.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
Frequently Asked Questions
Is money really the number one cause of divorce?
Money is consistently the second leading cause of divorce behind infidelity, contributing to an estimated 22-40% of divorces depending on the study. But a study of reasons for divorce found that financial disagreements in early marriage are uniquely predictive of later divorce — more so than disagreements about children, in-laws, or household responsibilities. The distinction matters: it’s not debt that predicts divorce, it’s disagreement about money.
My partner hides spending from me. Is this financial abuse?
Hidden spending isn’t automatically financial abuse — 40% of Americans do it, usually driven by shame, not malice. Financial abuse is a specific pattern of controlling behavior: restricting access to money, preventing a partner from working, forcing financial dependence. If your partner hides purchases because they fear your reaction, the issue is the dynamic between you — not necessarily abuse. If your partner controls ALL money and gives you no access or autonomy, that’s a different situation entirely and you should contact the National Domestic Violence Hotline.
Should couples combine finances or keep them separate?
The research doesn’t prescribe one approach. What matters is agreement — couples who agree on their financial arrangement (whether combined or separate) have higher satisfaction than couples who don’t agree on the arrangement. The worst setup is one partner wanting combined finances and the other maintaining secret separate accounts. Pick a system together, make it transparent, and revisit it when circumstances change.
Can filing bankruptcy together save a marriage?
Married couples can file jointly in Chapter 7, eliminating shared unsecured debt in 90-120 days. I filed bankruptcy in 1990 — my marriage survived and we rebuilt together. Federal Reserve research shows filers recover financially within 2-3 years. When the debt is the source of constant fighting, eliminating it removes the battlefield. But bankruptcy doesn’t change money personalities — you still need to understand each other’s patterns or you’ll rebuild the same debt.
How do we start the money conversation without fighting?
Don’t start with the numbers. Start with understanding. Take the Money Personality Quiz separately, then compare results together. It shifts the conversation from “you spend too much” to “oh, that’s why you react to money that way.” Olson and Rick’s research found that couples who did a simple financial “warm-up” exercise — learning each other’s financial confidence levels — immediately made better joint decisions. Understanding comes before strategy. Always.
Part of the Money Psychology Hub: This post is one piece of my complete Why Financial Education Fails research collection.
Part of the Debt & Marriage Hub: This post is one piece of my complete Debt and Marriage Guide — research on financial infidelity, hidden debt, the conversations that save marriages, and recovery options most advice ignores.
Part of a Research Series: This post is part of Why Financial Education Fails: The Research on Money Psychology and Behavior — a complete collection of research on financial education, money psychology, and debt behavior research.
Sources and Methodology
This post draws on the following primary sources:
- Papp, L.M., Cummings, E.M., & Goeke-Morey, M.C. — “For Richer, for Poorer: Money as a Topic of Marital Conflict in the Home” (2009), Family Relations — 100 couples tracked over 15 days; money conflict duration, intensity, and resolution patterns
- Britt-Lutter, S. et al. — “When Couples Fight About Money, What Do They Fight About?” (2023), Journal of Financial Therapy — Analysis of 1,014 Reddit posts + 481 married couples; categorization of financial conflict themes
- Rick, S.I., Small, D.A., & Finkel, E.J. — “Fatal (Fiscal) Attraction: Spendthrifts and Tightwads in Marriage” (2011), Journal of Marketing Research — 1,000+ adults; tightwad-spendthrift attraction and marital satisfaction
- Olson, J.G. & Rick, S.I. — “Managing Debt and Managing Each Other: The Interpersonal Dynamics of Joint Financial Decisions” (2018), SSRN — Financial confidence vs. literacy in couples’ debt management; couples outperform individuals
- Britt-Lutter, S. & Huston, S.J. — “Debt Concordance and Relationship Quality” (2020), Journal of Financial Counseling and Planning — Agreement on debt levels predicts satisfaction more than debt amount itself
- Bankrate — “Financial Infidelity Survey” (2025) — 40% hide money from partners; generational breakdowns; 43% say financial secrets equal physical infidelity
- Debt.com — “Debt and Divorce Survey” (2025) — 42% say credit card debt played a role in divorce, up from 29% two years prior
- Federal Reserve Bank of New York — “Insolvency After the 2005 Bankruptcy Reform” (2015) — Bankruptcy filers financial recovery within 2-3 years
- Scott, S.B. et al. — “Reasons for Divorce and Recollections of Premarital Intervention” (2013), Couple and Family Psychology — Financial disagreements as unique predictors of later divorce
- Rhode, S. — The Path to Happiness and Wealth (2002), Myvesta Foundation — Original observations on money as self-medication and money personality frameworks from 30 years of counseling couples in debt
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



