

Part of the FDCPA Rights Hub: This post is one piece of my complete Debt Collectors and Your FDCPA Rights: The Complete Guide — what collectors can and cannot do, how to stop calls, demand validation, fight back in court, and sue collectors who cross the line.
Quick Answer: A bank levy allows a debt collector with a court judgment to freeze and seize funds directly from your checking or savings account — often with no advance warning. Federal benefits like Social Security are protected, and filing for bankruptcy triggers an automatic stay that immediately halts active levies.
Expert Context: I’ve studied collector tactics since the 1990s, including as someone on the receiving end after my own bankruptcy in 1990. A bank levy is one of the scariest things a debt collector can do — but it’s also one of the most beatable if you know your rights and act fast.
A bank levy isn’t a threat letter or a collection call. It’s an action already in motion — and by the time you notice your account balance has dropped to zero, the money may already be gone.
You landed here because someone is chasing you for money. That part does end — and what happens next is the part almost nobody writes about.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
With American credit card debt hitting $1.28 trillion at the end of 2025 according to the Federal Reserve Bank of New York, and average credit card interest rates above 21%, more consumers are falling behind on payments than at any point in recent memory. When debts go unpaid long enough, collectors don’t just call — they sue. And when they win, a bank levy is one of the most aggressive tools in their arsenal.
What Is a Bank Levy?
Is this already happening to you? If your bank account has been frozen or levied right now, see the emergency crisis guide for a step-by-step 48-hour action plan.
Key Terms Defined
Bank Levy: A court-authorized order directing your bank to freeze and turn over funds in your account to satisfy a debt judgment. Unlike wage garnishment, a levy can drain an account entirely in one action.
Writ of Execution: The specific court order a debt collector obtains after winning a judgment, which authorizes the bank to release your funds to the collector.
Automatic Stay: A federal bankruptcy protection under 11 U.S.C. § 362 that immediately halts most collection actions, including active bank levies, the moment a bankruptcy case is filed.
Once a debt collector wins a lawsuit against you and a court issues a judgment, they can request a writ of execution — a court order directing your bank to freeze the funds in your account and turn them over to the collector, up to the full amount owed.
Your bank is legally required to comply. When the levy order arrives, your financial institution will freeze your funds, often without notifying you first. You may only discover it when a transaction gets declined or your balance reads zero.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Why a Bank Levy Is More Dangerous Than Wage Garnishment
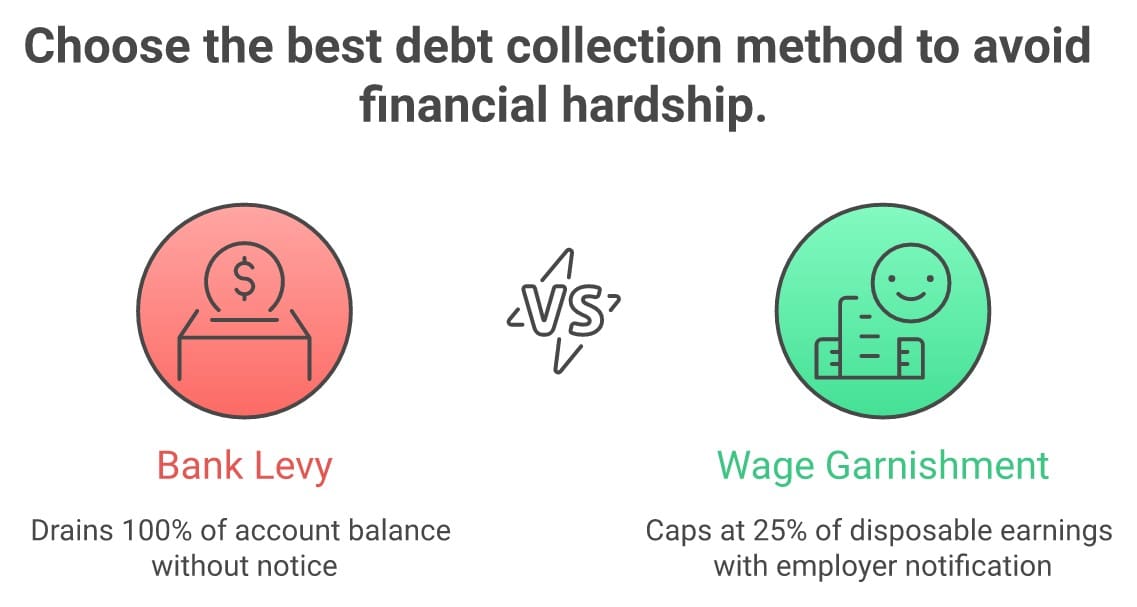
Most people have heard of wage garnishment, which is limited by federal law to 25% of your disposable earnings. A bank levy has no such cap. It can drain an account entirely — up to the full judgment amount — in a single action.
And it doesn’t stop at one account. If you have multiple accounts at the same bank, all of them can be frozen simultaneously. If your account doesn’t hold enough to cover the full judgment, the collector can come back for additional levies later. The exposure doesn’t end until the debt is paid, settled, discharged in bankruptcy, or the judgment expires.
What Money Is Protected From a Bank Levy
Not everything in your account is fair game. Under federal law, certain funds are automatically protected from levies when they arrive via direct deposit:
- Social Security benefits
- Supplemental Security Income (SSI)
- Veterans’ benefits
- Federal disability payments
- Federal Railroad retirement payments
- Civil Service Retirement (CSR) and FERS payments
Banks are required to automatically protect two months’ worth of these directly-deposited federal benefits before freezing any funds. State laws may add additional protections — some states protect a minimum bank balance or shield child support payments from collection. The specifics vary significantly by state, which is why knowing your state’s exemption rules matters.
Warning: If your federal benefits are deposited into an account that also receives non-exempt income, the protected and unprotected funds get mixed together. While the bank must protect two months of direct-deposited benefits, proving which funds are exempt can become complicated. Consider keeping benefit deposits in a separate account.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
How to Stop a Bank Levy
If a levy hits your account, you have a limited window to act. Most states give you only days — not weeks — to file a claim of exemption if protected funds were seized. Here are your real options:
Actions That Can Stop a Levy
- File a claim of exemption — if protected funds were seized, you can petition to get them back
- Negotiate a settlement — collectors want money, and many will release a levy for a lump-sum payment or short-term arrangement (get it in writing)
- Challenge the judgment — if you were never properly served with lawsuit papers, the judgment itself may be invalid
- File for bankruptcy — triggers an automatic stay that immediately halts the levy
What Won’t Help
- Ignoring it — the money is already frozen or gone
- Moving money after the levy — this can be seen as fraudulent transfer
- Calling the collector to argue — without legal leverage, you have no bargaining power
- Waiting it out — collectors can return with additional levies
The Option Nobody Talks About: Bankruptcy Stops Levies Instantly
I filed bankruptcy in 1990 when my real estate business collapsed. That automatic stay didn’t just stop the collection calls — it stopped everything. It was the first moment I could breathe.— Steve Rhode
Here’s what most bank levy articles won’t tell you: Filing for bankruptcy triggers an automatic stay under federal law that immediately halts most collection activity — including an active bank levy. The moment the case is filed, the collector must stop.
The Dogma: “Bankruptcy ruins your credit for 10 years — it should be your absolute last resort.”
The Reality: Federal Reserve research shows bankruptcy filers are better off financially within 2-3 years. A bank levy that drains your checking account can cause bounced rent checks, missed car payments, and cascading financial damage that takes far longer to recover from than a bankruptcy filing.
Chapter 7 bankruptcy can discharge qualifying unsecured debts entirely — meaning the judgment behind the levy disappears. Chapter 13 lets you restructure what you owe through a court-supervised repayment plan. Either way, the levy stops the moment you file.
I ran a credit counseling organization for over a decade. I watched people spend years grinding through debt management plans while collectors circled. Sometimes the fastest, most protective move is the one everyone is afraid to make.
Not Sure Which Path Fits Your Situation? Take the free Find Your Path quiz to see all your options — including the ones nobody else will mention.
The Bottom Line
A bank levy is one of the most aggressive collection tools available — it can drain your account with no advance warning. Federal benefits are protected, but everything else is fair game once a collector has a judgment. Your best defense is acting fast: file exemption claims within your state’s deadline, negotiate from a position of legal knowledge, and seriously consider whether bankruptcy’s automatic stay is the fastest way to stop the bleeding. Don’t let fear of the word “bankruptcy” cost you more than the levy itself.
Part of the Chapter 7 Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
Part of the Consumer Bankruptcy Research Hub: This post is one piece of my complete guide to The Benefits of Consumer Bankruptcy — 30 years of peer-reviewed research on outcomes, credit recovery, retirement protection, and who benefits most from filing.
Related: Wage Garnishment: The Complete Guide to Your Rights and Options — all your options in one place.
Running your own business and the levy hit your business operating account, not a personal one? See I’m Self-Employed and a Creditor Just Levied My Business Bank Account. Here’s What to Do Right Now. for how entity structure changes what a creditor can actually reach.
FAQ
How long does a bank levy last on your account?
A bank levy typically freezes your account for a limited period set by state law — usually 10 to 21 days — during which you can file a claim of exemption. After that window, the frozen funds are released to the creditor. However, if the first levy doesn’t satisfy the full judgment, the collector can request additional levies in the future until the debt is paid, settled, or discharged.
What money is exempt from a bank levy by a debt collector?
Federal benefits including Social Security, SSI, veterans’ benefits, and federal disability payments are automatically protected — banks must shield two months’ worth of directly-deposited benefits. Many states add additional protections, such as minimum balance exemptions or protections for child support payments received.
Can a debt collector levy your bank account without a court judgment?
In most cases, no. A debt collector must first sue you, win the case, and obtain a court judgment before requesting a bank levy. The exception is government agencies like the IRS or Department of Education, which can garnish certain benefits (up to 15% of Social Security) without a court order for federal debts.
Can filing bankruptcy stop a bank levy?
Yes — immediately. Filing for bankruptcy triggers an automatic stay under federal law (11 U.S.C. § 362) that halts most collection actions, including active bank levies. Chapter 7 can discharge the underlying debt entirely, while Chapter 13 restructures it through a repayment plan.
How do I get money back after a bank levy?
File a claim of exemption with the court within your state’s deadline if you believe protected funds were seized. You’ll need to show that the levied funds came from exempt sources (like Social Security). If the collector failed to follow proper legal procedure — such as not properly serving you with the lawsuit — consult a consumer law attorney, as the underlying judgment may be challengeable.



