

Quick Answer: Paying off someone else’s debt feels like love — but research shows it often functions as enabling, allowing the behavior that created the debt to continue while destroying your own financial security. A 2025 retirement study found that only 15% of Americans would reduce financial support to family members to protect their own retirement — making it the absolute last thing they’d cut, below lowering their own standard of living or going back to work. Fifty percent of parents provide an average of $1,474/month to adult children, often at the direct expense of their own retirement savings. The instinct to rescue is human. But the math doesn’t care about your intentions.
If you cosigned a loan and the borrower stopped paying, here is exactly what to do right now.
Expert Context: At Myvesta, the credit counseling organization I founded in 1994, we had psychologists on staff because we couldn’t untangle the debt from the relationships. Some of the most devastating cases I saw weren’t people who overspent on themselves — they were people who bankrupted themselves trying to save someone they loved. A mother who drained her 401(k) to pay her son’s gambling debts. A wife who took out credit cards in her name to cover her husband’s business losses. A daughter who moved her mother in and lost her own home paying the medical bills. In every case, the person who came to us wasn’t the one who created the debt. They were the one who tried to fix it — and got swallowed by it.
If someone you love is drowning in debt and you’re thinking about jumping in after them, this post is the life preserver nobody hands you before you leap.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
About This Research
This analysis draws on the 2025 PROTECTED RETIREMENT INCOME AND PLANNING (PRIP) Study, Savings.com parental support research, Hazelden Betty Ford Foundation research on enabling, Cambridge Health Alliance Division on Addiction family research, filial responsibility law analysis, peer-reviewed research on gambling’s impact on partners, and 30 years of direct case work at Myvesta and GetOutOfDebt.org.
Key Terms Defined
Financial Enabling: Doing financially for someone what they could and should be doing for themselves — especially when it allows destructive behavior to continue. Hazelden Betty Ford defines enabling as actions that remove the natural consequences of someone’s behavior, preventing them from experiencing the reality that might motivate change.
Financial Codependency: A pattern where one person’s financial identity becomes wrapped around rescuing or supporting another — deriving their sense of worth from being the financial savior. The enabler needs to be needed.
Filial Responsibility: Laws in 28 states that can legally obligate adult children to pay for an indigent parent’s care, including nursing home bills. Rarely enforced, but real — one Pennsylvania court ordered a son to pay $93,000 for his mother’s nursing home.
The Pattern I Saw Hundreds of Times
At Myvesta, the pattern was always the same. Someone would come in — usually a woman, usually in her 50s or 60s — and she’d say “I don’t understand how I got here. I was never a big spender.” And she wasn’t. The debt wasn’t hers. It was her son’s credit cards she took over when he lost his job. Or her husband’s medical bills that she put on her cards when insurance didn’t cover them. Or her mother’s nursing home that ate through the savings account she’d built for 30 years.
The debt belonged to someone she loved. The consequences belonged to her.
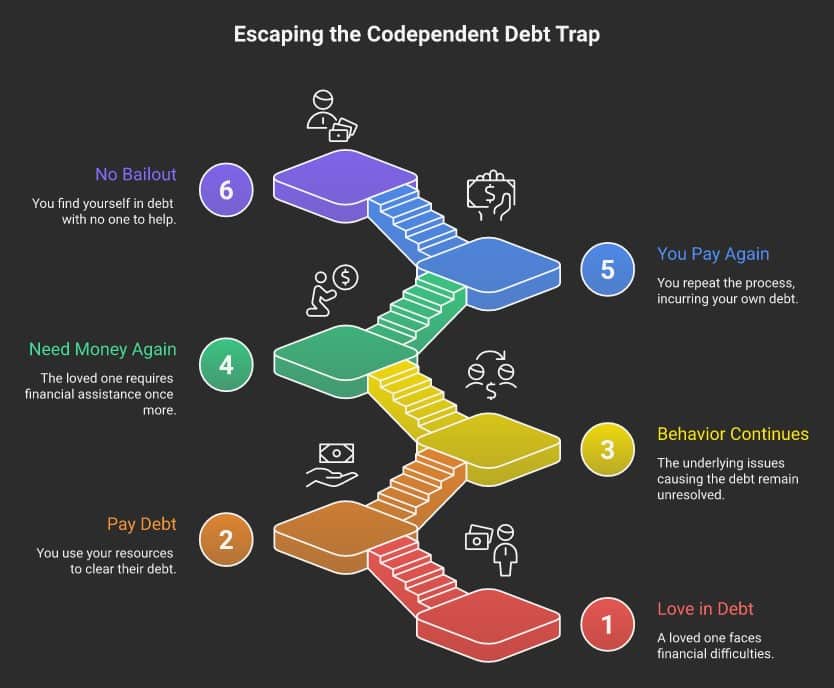
This is the trap nobody warns you about: the person who pays someone else’s debt rarely gets thanked. They get expected. The first bailout is a gift. The second is an obligation. By the third, it’s assumed. And somewhere along the way, the person doing the rescuing has more debt than the person they’re trying to save.
Treat yourself like a business — make decisions like a boardroom, not a panic room. Would a boardroom drain its operating reserves to cover another company’s losses? Then why are you doing it with your retirement?— Steve Rhode
The Numbers Nobody Runs Before Writing the Check
Here’s the math that guilt doesn’t let you do:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The 2025 PRIP Study found that Americans would rather adopt a lower standard of living (58%), return to work (54%), or put off medical care than reduce financial support to family members. Only 15% would cut family support to protect their own retirement — making it the absolute last sacrifice they’d consider.
Meanwhile, 50% of parents are sending an average of $1,474 per month to adult children. That’s $17,688 per year. At a 7% average return, that money invested in retirement instead would grow to:
A quarter million dollars. That’s not the money you’re giving away — that’s the money you’re never going to have because compound growth doesn’t wait for you to finish rescuing everyone else.
I’ve said it a thousand times and I’ll say it here: never cash out retirement to pay unsecured debt. Not yours, and certainly not someone else’s. That $50,000 you pull from your 401(k) to pay your son’s credit cards? After taxes, penalties, and lost growth, it costs you $150,000 or more in retirement income. And his spending pattern didn’t change because you paid the bill.
The Dogma: “Good parents help their children financially, no matter what.”
The Reality: Research shows 75% of parents provide financial support to adult children — yet 53% of those children are already capable of meeting their basic needs. Parents contribute more than 2x to adult children each month than to their own retirement accounts. This isn’t support. It’s a wealth transfer that leaves the parent vulnerable and the child dependent.
When the Person You’re Rescuing Has an Addiction
The most dangerous version of this trap involves addiction — gambling, substances, or compulsive spending. The Hazelden Betty Ford Foundation defines enabling as actions that remove the natural consequences of someone’s behavior, preventing them from experiencing the reality that might motivate change.
In gambling addiction specifically, peer-reviewed research on partners of problem gamblers found that partners routinely take on financial responsibilities for the gambler’s debt — working extra jobs, juggling accounts, paying off creditors — while the gambler continues gambling. The research found this creates a codependent cycle where the partner’s mental and physical health deteriorates (insomnia, depression, panic attacks, high blood pressure) while the gambler faces no financial consequences for their behavior.
The r/problemgambling post that surfaced this topic said it plainly: “I paid off his debts… now I’m $20K in debt because of him.” She paid. He gambled. She paid again. Now she’s the one who can’t sleep at night.
If the person you’re rescuing is a parent who won’t stop spending, here’s what actually helped — including the one conversation worth having and the financial boundaries you can’t skip. More broadly, if they have an addiction or compulsive spending problem, read my deep dive on what the research says actually works for spending addiction. The short version: the debt is the symptom. The addiction is the fire. Paying off the charred wood doesn’t put out the fire.
Warning: If you’re in a relationship where your partner’s spending, gambling, or substance use is creating debt that you’re being pressured to pay — and you feel you can’t say no — that dynamic may cross from codependency into financial abuse. If you’re afraid of what happens when you don’t pay, that fear is information. The National Domestic Violence Hotline (1-800-799-7233) has counselors who understand financial abuse specifically.
The Legal Side: When the Law Says You DO Owe
Most of the time, you are NOT legally responsible for someone else’s debt. But there are real exceptions:
- Cosigned loans: If you cosigned, you owe 100% if the borrower defaults. Period.
- Community property states: In 9 states, debt acquired during marriage may be both spouses’ responsibility.
- Filial responsibility laws: 28 states have laws that can obligate adult children to pay for a parent’s care. In a 2012 Pennsylvania case, a court ordered a son to pay $93,000 for his mother’s nursing home bill.
- Authorized user debt: If you’re an authorized user on someone’s credit card, you may or may not be liable depending on the state and card agreement.
For the full breakdown of filial responsibility laws: I wrote a detailed analysis at 29 States Have a Law That Could Make You Pay Your Parent’s Nursing Home Debt.
- You are NOT responsible for a parent’s credit card debt after death (unless you cosigned)
- You are NOT responsible for a sibling’s debt — ever, in any state
- You are NOT responsible for a partner’s pre-relationship debt (unless you cosigned or are in a community property state)
- Debt collectors who tell you otherwise are lying — and violating the FDCPA
The Dogma: “You inherit your parents’ debt when they die.”
The Reality: In the vast majority of cases, a parent’s debt dies with them. The estate may be responsible — meaning the debt gets paid from whatever assets the parent left — but the children are not personally liable. Debt collectors will absolutely call you and imply otherwise. They are counting on your guilt and your ignorance of the law. The FTC is clear: family members typically do not have to pay the debts of a deceased relative from their own money.
The One Question to Ask Before You Write the Check
Before you pay someone else’s debt — whether it’s a parent, a partner, an adult child, or a sibling — ask yourself this:
The Question: “If I pay this debt and nothing changes about the behavior that created it, will I be okay with having spent this money?”
If the answer is no — if paying this debt only makes sense if the person changes — then you’re not making a financial decision. You’re making a bet. And you’re betting YOUR financial security on SOMEONE ELSE’S behavior change.
That’s a bet you will lose most of the time. Not because people don’t want to change. But because research shows that even with professional treatment, relapse rates for behavioral problems run 47%. Without treatment? Much higher.
The most loving thing you can do is often the hardest: let them experience the consequences of their own financial decisions. Consequences are information. When you remove them, you remove the information they need to change.
What You Can Do Instead of Paying Their Debt
- Help them find their own path. Send them to Find Your Path — it walks through their specific situation and shows them options they probably don’t know about (including bankruptcy, which may be the fresh start they need)
- Understand your own money patterns first. Take the Money Personality Quiz — codependent rescuers often have specific money personality patterns that make them vulnerable to this trap
- Offer support without money. Drive them to a free credit counseling session. Help them organize their bills. Be present without being their ATM.
- Protect your retirement above everything. You can recover from almost any financial setback except running out of time. Retirement savings that compound for 10-15 years cannot be replaced.
- Get help for yourself. Co-Dependents Anonymous (CoDA) and Gam-Anon (for families of gamblers) exist because you’re not the first person to face this. The pattern is well-understood. You don’t have to figure it out alone.
Already took on someone else’s debt? Ask Steve directly — describe your situation and I’ll help you think through your options. The debt you took on for someone else is still YOUR debt now, and all the options (bankruptcy, settlement, strategic inaction) are available to you.
Key Takeaways
- 50% of parents support adult children at an average of $1,474/month — 75% of those children are already capable of meeting their own needs
- Parents contribute 2x more to adult children monthly than to their own retirement accounts
- Only 15% of Americans would reduce family financial support to protect their own retirement — it’s the very last thing people will cut
- Financial enabling removes consequences that motivate change — you pay, they don’t change, you pay again
- 28 states have filial responsibility laws that could make you legally liable for a parent’s care (but enforcement is rare)
- The one question that matters: “If nothing changes, am I okay with this money being gone?”
The Bottom Line
If you’re reading this because someone you love is in debt and you’re wondering whether to bail them out — I know how that feels. The guilt is real. The fear of what happens if you don’t help is real. But here’s what 30 years of watching this play out has taught me: the person who pays someone else’s debt almost always ends up in worse shape than the person they were trying to save. The research confirms it — parents give more to adult children than to their own retirement, and only 15% would ever stop. That’s not love making a financial decision. That’s guilt making it. Treat yourself like a business. Would a boardroom drain its reserves to cover another company’s losses? Your retirement, your credit, your financial future — those are not less important than someone else’s debt. They’re more important, because nobody is going to bail YOU out when the money runs out. The most loving thing you can do might be the hardest: help them find their own path instead of walking it for them.
Frequently Asked Questions
Am I legally responsible for my parents’ debt after they die?
In most cases, no. A parent’s debt is paid from their estate (whatever assets they left), not from the children’s personal finances. The exceptions: if you cosigned a loan, if you’re in a community property state and the debt was marital, or if filial responsibility laws apply in your state (28 states have them, though enforcement is rare). The FTC confirms that family members generally don’t owe a deceased relative’s debts from their own money.
How do I stop enabling without abandoning someone I love?
Replace money with support. Drive them to a free credit counseling appointment. Help them apply for programs they qualify for. Send them to Find Your Path to see their actual options. Be emotionally present without being financially responsible. Hazelden Betty Ford defines the line clearly: healthy support encourages recovery and independence; enabling removes consequences and maintains dependence.
My adult child keeps asking for money. How much is too much?
If you’re contributing more to your child than to your own retirement, that’s a mathematical problem with a ticking clock. Research shows 75% of supported adult children can already meet their basic needs. The question isn’t “how much is too much” — it’s “what am I giving up that I can never get back?” Time in the market cannot be replaced. Your child has decades to earn. You may not.
What if my partner’s gambling or spending puts me in debt?
This is the most dangerous version of financial codependency. Research on gambling partners shows the non-gambling partner’s health deteriorates — depression, insomnia, panic attacks — while covering the gambler’s debts. If the behavior hasn’t changed after you’ve paid once, paying again won’t change it either. Read my research on spending addiction and consider whether the relationship dynamic crosses into financial abuse.
I already took on someone else’s debt. What are my options?
Debt you assumed for someone else is legally YOUR debt now — and all options are available to you. Bankruptcy can discharge it (I filed in 1990 and rebuilt everything). Settlement may reduce it. If you’re judgment proof, strategic inaction is viable. The debt doesn’t care how you got it — and neither does the solution. Take the Find Your Path quiz to see which option fits, or ask Steve directly.
Part of a Research Series: This post is part of Why Financial Education Fails: The Research on Money Psychology and Behavior — a complete collection of research on financial education, money psychology, and debt behavior research.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
Sources and Methodology
This post draws on the following primary sources:
- Protected Retirement Income and Planning (PRIP) Study (2025) — Only 15% would reduce family support to protect retirement; Americans rank it as their absolute last sacrifice
- Savings.com — “Financial Support for Adult Children Study” (2025) — 50% of parents support adult children at $1,474/month average; 75% of supported children can meet their own needs
- Bankrate — “Parents Sacrifice for Adult Children Survey” (2024) — 61% of parents with adult children have sacrificed financially; parents contribute 2x more to children than retirement
- Hazelden Betty Ford Foundation — “Signs That You Are Enabling Someone” — Clinical definition of enabling vs. healthy support in addiction contexts
- Cambridge Health Alliance, Division on Addiction — “Supporting Families of Those with Gambling Problems” — Provider guidance on family dynamics in gambling addiction
- Patford, J. — “Impacts of Gambling Problems on Partners” (2009), Asian Journal of Gambling Issues and Public Health — Partner health impacts, financial responsibility patterns, codependency in gambling
- World Population Review — “Filial Responsibility Laws by State” (2026) — 28 states with filial responsibility laws
- Nolo — “Filial Responsibility: When Children Must Pay Parents’ Medical Debt” — Legal analysis including the $93,000 Pittas case in Pennsylvania
- Federal Trade Commission — “Debt Collection FAQs” — Confirmation that family members generally don’t owe deceased relatives’ debts
- Hague et al. — “Treatments for Compulsive Buying” (2016), Comprehensive Psychiatry — 47% relapse rate cited for behavioral treatment outcomes
- Rhode, S. — The Path to Happiness and Wealth (2002), Myvesta Foundation — Case observations on codependent financial patterns from 30 years of debt counseling
- Graeber, D. — Debt: The First 5,000 Years (2011) — Historical and cultural analysis of debt as moral obligation, guilt, and family duty
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



