

Part of the FDCPA Rights Hub: This post is one piece of my complete Debt Collectors and Your FDCPA Rights: The Complete Guide — what collectors can and cannot do, how to stop calls, demand validation, fight back in court, and sue collectors who cross the line.
Quick Answer: Zombie debt is old debt — often past the statute of limitations — that collectors try to revive. They buy it for pennies on the dollar and use fear, shame, and confusion to get you to pay or accidentally restart the legal clock. Federal law (Regulation F) prohibits them from suing you on time-barred debt. If a collector calls about a debt you don’t recognize from years ago, the most important thing you can do is say nothing until you know your rights.
Expert Context: I’ve helped people deal with debt since 1994, including running a nonprofit credit counseling organization with 70 employees. I’ve seen every zombie debt tactic in the book — and they all rely on one thing: you not knowing the rules. Once you know the rules, collectors lose their leverage.
A debt you thought was dead just showed up again. A collector is calling about a credit card you forgot about ten years ago, a medical bill from a hospital visit in 2016, or — in the worst cases — a second mortgage your bank told you was forgiven during the 2008 crisis. Welcome to the world of zombie debt.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
This is happening to millions of Americans right now. A Bloomberg News investigation found that more than 600,000 second mortgages from before the 2008 financial crisis remain outstanding, with debt collectors buying them for pennies and demanding payment plus years of accumulated interest. The Consumer Financial Protection Bureau has received thousands of complaints from homeowners blindsided by debts they thought were gone.
Here’s what you need to know — and more importantly, what you need to not do.
What Is Zombie Debt?
Zombie debt is any old obligation that a collector tries to revive after you believed it was resolved, forgiven, or expired. The most common types:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- Time-barred debt: Past the statute of limitations in your state. The collector can’t sue you, but they can still call and try to collect.
- Discharged debt: Debt that was included in a bankruptcy discharge. Attempting to collect on discharged debt violates federal law.
- Paid or settled debt: Debt you already resolved that gets resold to a new buyer who doesn’t have (or ignores) your payment records.
- Zombie mortgages: Second liens from the 2008 crisis that banks wrote off or stopped collecting, now being purchased by debt buyers demanding full payment plus years of interest.
How the Zombie Debt Business Works
Understanding the economics tells you everything about the tactics.
When a creditor gives up on collecting a debt, they write it off (charge-off) and may sell it to a debt buyer. The sale price: 4 to 7 cents per dollar. Your $10,000 credit card balance becomes a $400-$700 investment for the buyer.
That buyer doesn’t need you to pay the full $10,000 to profit. If they convince you to pay even $2,000 on a debt you may not legally owe, they’ve made a 300-500% return. This is why their tactics focus on fear and confusion — not legal action. They know the law may be on your side. They’re betting you don’t.
The Clock-Reset Trap: In many states, making even a small payment on a time-barred debt — or acknowledging in writing that you owe it — restarts the statute of limitations. A $25 payment on a debt that expired three years ago can give the collector the legal right to sue you for the full amount. This is the single most important thing to understand about zombie debt: say nothing and pay nothing until you know the rules in your state.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Your Rights Under Federal Law
The CFPB’s Regulation F (the updated Fair Debt Collection Practices Act rules) provides specific protections:
What Collectors Cannot Do With Zombie Debt
- Sue you or threaten to sue on a debt past the statute of limitations
- Collect on discharged bankruptcy debt — this violates the bankruptcy discharge injunction
- Misrepresent the amount owed, the age of the debt, or your legal obligation
- Harass you with repeated calls, threats, or abusive language
- Contact your employer, family, or friends about the debt (with limited exceptions)
What Collectors Can Still Do
- Contact you by phone or mail to request payment — even on time-barred debt
- Report the debt to credit bureaus if it’s within the 7-year credit reporting window
- File a proof of claim in bankruptcy proceedings
Some states require collectors to include a specific disclosure on their validation notice when collecting time-barred debt. California and New York City have additional disclosure requirements. Check the CFPB’s guide for your state.
The Zombie Mortgage Crisis (2025-2026)
The largest zombie debt story right now involves second mortgages from the 2008 housing crisis. Here’s what happened:
- Millions of homeowners took out second mortgages (home equity loans, HELOCs) before 2008.
- When the housing market crashed, banks stopped collecting on many of these second liens. They stopped sending statements. They stopped reporting to credit bureaus. Some told borrowers the debt was forgiven.
- The banks wrote the loans down on their books — but never formally discharged them.
- Now, debt collectors have purchased these old second mortgages and are demanding full payment plus 10-15 years of accumulated interest.
- Because mortgages are secured by your home, these collectors can threaten foreclosure — unlike unsecured credit card zombie debt.
Senator Elizabeth Warren sent a letter to the independent monitor of the National Mortgage Settlement demanding answers. The CFPB issued guidance reminding collectors that the FDCPA and Regulation F apply to these mortgages. But only four states have passed legislation specifically addressing zombie mortgages.
Zombie debt works because of shame and confusion. The collector knows you feel guilty about an old debt — and they’re counting on that guilt to override your legal rights. The moment you understand the rules, they lose their power over you.— Steve Rhode
What to Do If a Zombie Debt Collector Contacts You
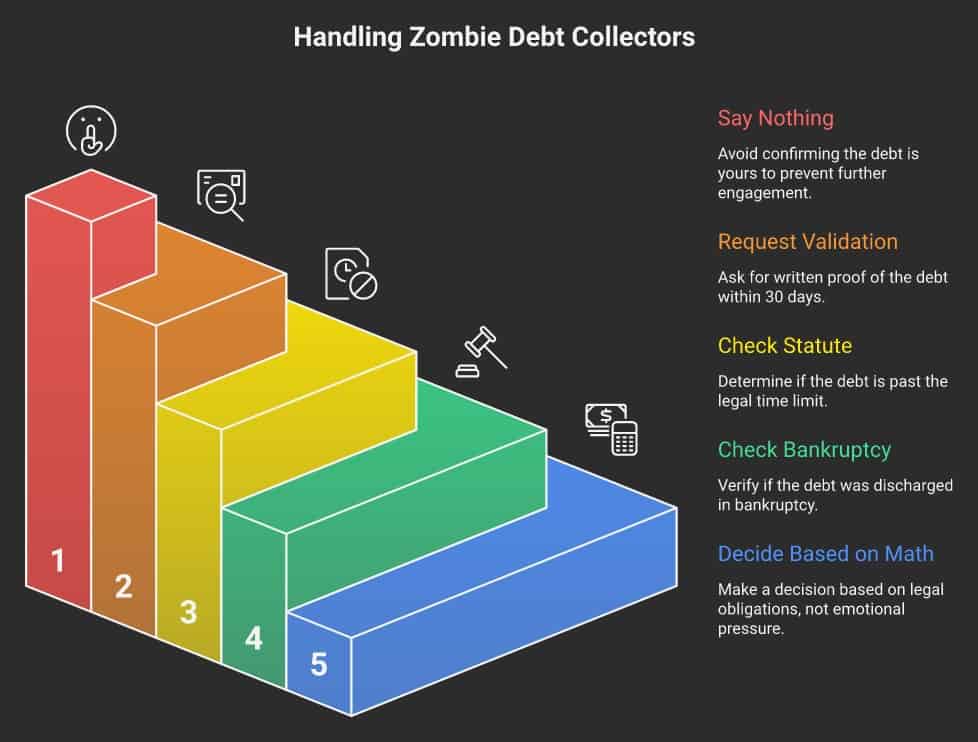
Follow these steps in order. Do not skip any.
- Step 1: Say nothing substantive. Don’t confirm the debt is yours. Don’t promise to pay. Don’t say “I know about that debt.” Simply say: “Send me written verification.” Hang up.
- Step 2: Send a written debt validation request within 30 days of their first contact. Under Regulation F, they must provide the original creditor’s name, the amount, and proof the debt is yours. Use the CFPB’s sample letter.
- Step 3: Check your state’s statute of limitations. If the debt is past the SOL, they cannot sue you. Nolo’s state-by-state guide is a reliable starting point.
- Step 4: Check if the debt was discharged in bankruptcy. If you filed bankruptcy and this debt was included, collection attempts violate the discharge injunction. Your bankruptcy attorney can send a cease letter.
- Step 5: Decide based on math, not shame. If the debt is time-barred, you have no legal obligation to pay. If it’s within the SOL, evaluate whether paying, settling, or filing bankruptcy makes the most mathematical sense for your future.
Common Claim: “Even if the debt is old, you have a moral obligation to pay what you owe.”
What the Data Shows: The collector calling you bought your debt for 4-7 cents on the dollar. The original creditor already wrote it off, deducted the loss, and moved on. Federal Reserve data shows credit card companies price a ~4% annual charge-off rate into their business model. Nobody in this transaction is operating on moral principles except you — and that’s exactly what they’re counting on.
The 1099-C Tax Trap
One legitimate concern with old debt: if a creditor cancels $600 or more of debt, they’re required to send you a 1099-C form, and the IRS may treat the canceled amount as taxable income.
This catches people off guard years later — you get a tax bill for debt you forgot about. But there are exceptions:
- Insolvency exception: If your total debts exceeded your total assets at the time of cancellation, you may exclude some or all of the canceled debt from income. Use IRS Form 982.
- Bankruptcy discharge: Debt discharged in bankruptcy is not taxable income.
- Mortgage debt (primary residence): Under certain conditions, canceled mortgage debt on your primary residence may be excludable.
If you receive a 1099-C for a zombie debt, consult a tax professional before paying. Many people who receive these forms qualify for the insolvency exception and owe nothing.
Key Takeaways
- Never acknowledge or pay a zombie debt without knowing your state’s statute of limitations. A single payment can restart the legal clock.
- Collectors cannot sue you on time-barred debt. Federal Regulation F prohibits it.
- Zombie mortgage collectors are threatening foreclosure on 600,000+ old second liens. The CFPB says these collectors must still follow the FDCPA.
- Debt buyers paid pennies for your old debt. They profit even if you pay a fraction — their tactics rely on shame, not law.
- If you get a 1099-C tax form, check the insolvency exception before assuming you owe taxes on canceled debt.
The Bottom Line
Zombie debt collectors make money by exploiting the gap between what you think you owe and what the law actually requires. A Bloomberg investigation found 600,000+ second mortgages from the 2008 crisis being revived by collectors who bought them for pennies. Federal Regulation F prohibits suing on time-barred debt, but collectors can still call — and they’re counting on shame and confusion to make you pay debts you may have no legal obligation to repay. The single most important rule: say nothing and pay nothing until you’ve checked your state’s statute of limitations, confirmed the debt wasn’t previously discharged, and made a decision based on math, not manufactured guilt. If you’re being contacted about an old debt you thought was resolved, you have more power than the collector wants you to know.
If the debt a collector is chasing you for was actually wiped out in your bankruptcy, that’s a different problem than an ordinary zombie debt — see A Creditor Won’t Stop Collecting After My Bankruptcy Discharge. Here’s What to Do Right Now. for how to get a bankruptcy court to enforce your discharge.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
Frequently Asked Questions
Can a debt collector sue me for a debt that’s 10 years old?
In most states, no. Statutes of limitations on debt range from 3-10 years depending on the state and debt type. Once the SOL expires, the CFPB’s Regulation F prohibits collectors from suing or threatening to sue. However, they can still contact you to request voluntary payment. Check your specific state’s SOL before responding.
What happens if I make a small payment on zombie debt?
In many states, making any payment — even $1 — on a time-barred debt restarts the statute of limitations. This gives the collector the legal right to sue you for the full amount. Some states also restart the clock if you acknowledge the debt in writing. This is why the first rule is: say nothing and pay nothing until you know the rules.
I got a 1099-C for an old debt. Do I owe taxes?
Not necessarily. If your total debts exceeded your total assets at the time the debt was canceled (insolvency), you can exclude some or all of the canceled amount from taxable income using IRS Form 982. Debt discharged in bankruptcy is also not taxable. Consult a tax professional before paying a tax bill on canceled zombie debt.
What should I do if a collector contacts me about a mortgage I thought was forgiven?
This is the zombie mortgage crisis. Request written validation of the debt. Check whether the original lender formally discharged the loan or merely stopped collecting. Review your closing documents and any modification agreements. Contact a housing counselor through the CFPB’s housing resources. If the collector violates the FDCPA, you may have grounds for a lawsuit.
Can zombie debt appear on my credit report?
Only if it’s within the 7-year credit reporting window, which runs from the date of first delinquency — not from when a new collector purchased the debt. If a collector re-ages the debt on your credit report (makes it appear newer than it is), that’s a violation of the Fair Credit Reporting Act. Dispute it with the credit bureau.
Related: If gambling created the debt that collectors are now chasing, read Gambling Destroyed Your Family’s Finances: The Two-Track Recovery Plan. For understanding why creditors use shame as a collection tool, read Your Creditors Already Expected You Might Not Pay.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Sources
- CFPB — “Can Debt Collectors Collect a Debt That’s Several Years Old?”
- CFPB — Debt Collection Rule (Regulation F)
- CFPB — Guidance on Zombie Mortgage Collection Tactics (2025)
- CFPB — “Zombie Second Mortgages: When Collectors Come for Long-Forgotten Home Loans”
- Bloomberg News — “How Debt Collectors Spin Riches from Zombie Loans” (2025)
- Bloomberg News — “How Banks, Regulators Spawned the Zombie Mortgage Nightmare” (2025)
- U.S. Senate Banking Committee — Sen. Warren Letter on Zombie Mortgages (Dec 2025)
- FTC — Debt Collection FAQs
- National Consumer Law Center — Zombie Second Mortgages
- IRS — About Form 1099-C, Cancellation of Debt
- IRS — Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness
If the debt they are chasing is old, read what to do when a collector calls about a debt that’s years old — one wrong move can restart the clock.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If the collector can’t prove the debt exists at all, that’s a different problem — see why a name and an amount don’t make a debt real.
Related myth: Many people believe a debt is gone once it drops off their credit report. It isn’t — see why “seven years and it’s gone” is a myth and what actually happens to old debt.
If you pulled your credit report and found a debt you don’t recognize, here’s exactly what to do in the next 48 hours.



