

Quick Answer: Reselling on Poshmark, eBay, or Mercari can start as decluttering and turn into a compulsive cycle that creates more debt than income. The platforms are engineered with the same variable-reward mechanics that make gambling addictive — every sale notification, every offer alert is an unpredictable dopamine hit. If reselling has put you in debt, the problem is not willpower. It is brain chemistry. And there are evidence-based approaches that actually work.
Expert Context: I founded one of the first programs in the United States for compulsive spenders in 1994. Over 12 years at Myvesta Foundation, I worked with thousands of people whose spending behavior — not laziness, not irresponsibility — was the root cause of their debt. Resale platform addiction is the newest version of a pattern I have been treating for three decades.
A post in r/shoppingaddiction recently got over 130 upvotes and dozens of comments. The title: “Selling on Poshmark Devastated My Financial Life and Massively Stoked Shopping and Auction Addictions.” The comments were filled with people saying the same thing — they started selling to make money and ended up spending far more than they ever earned.
This is not a willpower problem. Research in the Journal of Behavioral Addictions confirms that variable-ratio reinforcement — unpredictable rewards delivered at random intervals — is the most powerful schedule for maintaining compulsive behavior known in psychology. Every Poshmark “offer” ping, every “your item sold” notification, every counter-offer alert operates on exactly this schedule.
How Reselling Becomes an Addiction Cycle
The cycle almost always starts the same way. You clean out your closet. You list a few things. Something sells. You feel a rush — someone valued what you had, and money appeared. That feeling is real. It is a measurable dopamine response. And the platform is designed to make you chase it.
Here is how the cycle works:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- The gateway. You join Poshmark or Mercari to sell things you already own. It works. You make a few hundred dollars.
- The sourcing trap. You run out of your own things to sell. So you start buying inventory — thrift stores, clearance racks, estate sales. You tell yourself it is a business investment.
- The math breaks. You are spending $200 at Goodwill to maybe sell $150 on Poshmark after fees and shipping. But each individual sale feels like a win, so the losses stay invisible.
- The time blindness. You are spending 20-30 hours a week photographing, listing, shipping, responding to lowball offers. If you divided your actual profit by your actual hours, you would be making less than minimum wage — or losing money.
- The buying creep. While sourcing, you start buying things for yourself. The platforms recommend items based on your browsing. The line between inventory and personal purchases disappears.
- The debt. Credit cards are funding the sourcing. Storage units are holding the overflow. Your spouse does not know about the PayPal balance or the credit card statements.
The hiding is the signal. In my experience running Myvesta’s spending program, the moment someone starts concealing purchases — stashing bags in the car, rerouting packages to a friend’s house, opening credit cards their partner does not know about — the behavior has crossed from habit into compulsion. Myvesta’s research found that 49.7% of people knew someone who spends to escape problems, but only 16.3% admitted doing it themselves. The denial gap is massive.
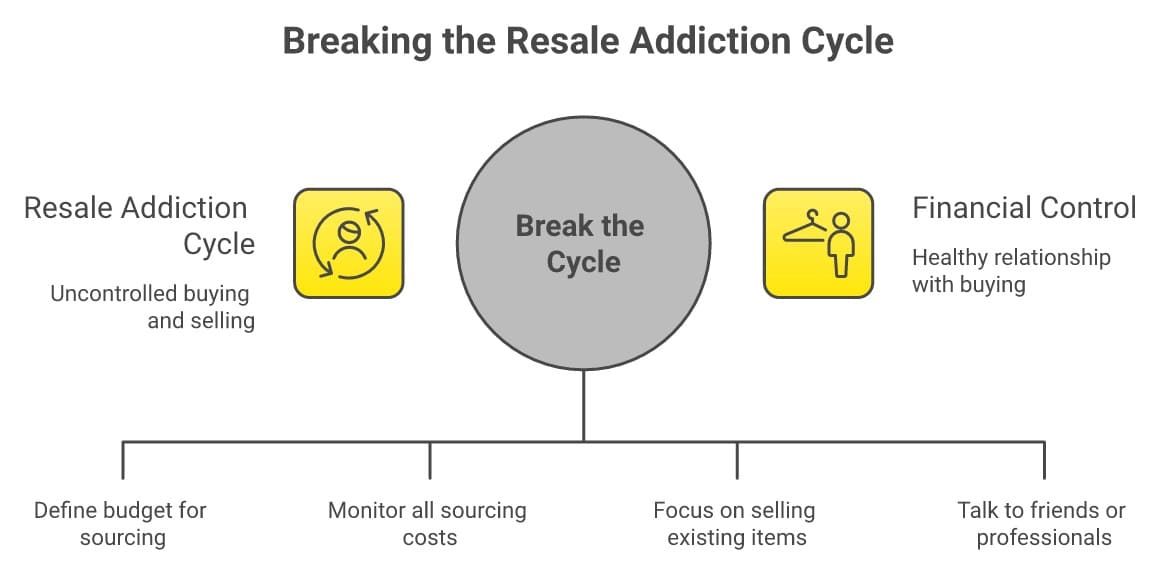
Why Resale Platforms Are Designed Like Slot Machines
This is not a metaphor. The neuroscience is specific.
Researchers studying behavioral addiction have identified that midbrain dopamine neurons stay activated when reward timing is uncertain. When you know exactly when a reward is coming, your brain habituates — the excitement fades. When you do not know — when the next sale could come in 10 minutes or 10 days — your brain stays in a heightened state of anticipation. This is the same mechanism that keeps people at slot machines.
Resale platforms layer multiple variable-reward triggers:
- Sale notifications — unpredictable timing, unpredictable amount
- Offer alerts — someone wants your item, but will they accept your counter?
- “Likes” and “shares” — social validation that mimics social media addiction
- Price drop suggestions — the platform nudges you to engage when activity slows
- Bundled purchases — the thrill of a bigger-than-expected sale
Each of these is a pull on the lever. Each unpredictable outcome keeps you playing.
The Debt Is the Symptom — Not the Problem
“Debt is what is left over when the math is broken. But the math broke for a reason — and that reason is almost never laziness or irresponsibility. It is almost always something emotional that spending temporarily medicates.”
This is the framework I built Myvesta around, and it is the framework that works for resale addiction specifically. The debt on your credit cards is not the disease. The compulsive cycle — the emotional need that sourcing and selling temporarily satisfies — is the disease. If you pay off the credit cards without addressing the cycle, the cards will fill back up.
The research bears this out. A systematic review in the American Journal on Addictions found that budget-based interventions alone — “just stop spending so much” — have essentially no evidence supporting them for compulsive buying. What does work is cognitive behavioral therapy targeting the automatic thought-to-purchase pipeline, combined with financial counseling for the debt symptom.
What Actually Works: The Two-Track Approach
From 12 years of running a compulsive spending program, here is what I know works — and what does not.
What does not work: “Just delete the app.” “Make a budget.” “Have more discipline.” These approaches fail because they treat compulsive spending as a character flaw instead of a behavioral pattern with neurological roots. A systematic review of 24 treatment studies found no evidence that willpower-based approaches produce lasting change.
What does work: A two-track approach — address the behavior AND the debt simultaneously, because they feed each other. Evidence supports CBT (a 12-session protocol shows significant improvement maintained at 6 months), support groups (Debtors Anonymous, Spenders Anonymous), and in some cases, SSRI medication as an adjunct. The debt side needs its own plan that does not depend on sustained willpower over years.
Track 1: Address the Behavior
- Talk to your doctor. Compulsive buying disorder shares neural pathways with OCD, substance addiction, and mood disorders. A mental health professional can identify whether underlying anxiety, depression, or bipolar disorder is driving the spending cycle. This is not weakness — it is diagnosis.
- Start CBT. Cognitive behavioral therapy for compulsive buying has the strongest evidence base. It specifically targets the automatic thoughts (“this is a great deal,” “I can flip this for profit”) that trigger the purchase before your rational brain catches up.
- Join a support group. Debtors Anonymous and Spenders Anonymous offer free, confidential meetings — many now online. They are an accessible first step when CBT is not immediately available.
- Remove the triggers. Uninstall resale apps from your phone. Unsubscribe from thrift haul accounts. Stop following reseller content. The apps are designed to pull you back — removing them is not giving up, it is harm reduction.
Track 2: Address the Debt
Once the cycle is interrupted, deal with the debt honestly. Here are your actual options — all of them, including the ones nobody in the reselling community talks about:
- Sell existing inventory at any price. Get it out of your house. The psychological weight of unsold inventory keeps the cycle alive. A loss on the sale is better than a loss plus ongoing storage costs plus the emotional pull to keep listing.
- Assess total debt honestly. Add up every credit card, every PayPal credit balance, every Buy Now Pay Later account. Most people in this cycle are surprised by the real number because it accumulated across multiple accounts.
- Consider bankruptcy if the debt exceeds what you can pay in 3 years. I filed Chapter 7 myself in 1990. Credit card debt from compulsive spending is fully dischargeable. Your retirement accounts are completely protected. And your credit score will recover faster than the shame narrative suggests — most people see improvement within 12-18 months.
- Check if you are judgment-proof. If your income is primarily from Social Security, disability, or other exempt sources, debt collectors may not be able to collect regardless. Check your state’s protections here.
Key Takeaways
- Resale platform addiction uses the same variable-reward mechanics as gambling — it is brain chemistry, not character
- 5.8% of U.S. adults meet clinical criteria for compulsive buying disorder; 25% likely use spending as emotional self-medication
- The cycle: sell your own stuff → source inventory → spend more than you earn → hide the debt
- Budgets and willpower alone have no evidence base for compulsive buying — CBT and support groups do
- Address the behavior AND the debt simultaneously — they feed each other
- If reselling debt is unmanageable, bankruptcy fully discharges credit card debt and protects retirement
The Bottom Line
If reselling started as a way to make money and turned into a source of debt, shame, and secrecy, you are not broken. You are caught in a cycle that platforms are engineered to create. The debt is real, but it is the symptom — the compulsive behavior is the cause. Treat both. Talk to your doctor, consider CBT, join Debtors Anonymous, and address the debt with all your options on the table — including the ones the shame narrative says you should not consider.
Frequently Asked Questions
Is reselling on Poshmark addictive?
It can be. Resale platforms use variable-ratio reinforcement — unpredictable rewards at random intervals — which neuroscience research identifies as the most powerful driver of compulsive behavior. Every sale notification, offer alert, and like is an unpredictable reward hit. For the 5.8% of adults who meet criteria for compulsive buying disorder and the estimated 25% who use spending as emotional self-medication, these mechanics can trigger genuine addictive behavior.
How do I know if reselling has become a problem?
Three signals from my 12 years running a compulsive spending program: you are spending more on inventory than you earn from sales and rationalizing the losses, you are hiding purchases or credit card statements from your partner, and you feel anxious or irritable when you cannot check the app or source inventory. If you recognize two of these three, the behavior has likely crossed from hobby into compulsion.
Can reselling debt be discharged in bankruptcy?
Yes. Credit card debt accumulated from reselling — inventory purchases, shipping supplies, storage units, platform fees — is unsecured consumer debt, fully dischargeable in Chapter 7 and Chapter 13 bankruptcy. Your retirement accounts are completely protected under ERISA. Bankruptcy also triggers the automatic stay, which immediately stops all collection calls and lawsuits.
What treatment works for compulsive buying?
The strongest evidence supports cognitive behavioral therapy, specifically a 12-session protocol that targets the automatic thoughts driving purchase decisions. A systematic review of 24 treatment studies found that CBT produces significant improvement maintained at 6-month follow-up. Support groups like Debtors Anonymous provide accessible ongoing accountability. SSRI medication may help as an adjunct, particularly when anxiety or depression drives the spending cycle. Budget-only approaches have no meaningful evidence for compulsive buying.
Should I keep reselling to pay off the debt?
Generally no — continuing to engage with the platform while trying to recover is like telling an alcoholic to bartend their way out of debt. The platform mechanics that created the problem will keep reinforcing the behavior. Sell remaining inventory quickly at whatever price moves it, then step away. Address the debt through other means: payment plans, negotiation with creditors, or bankruptcy if the total exceeds what you can reasonably pay in three years.
Reselling is one shape compulsive spending takes; there are others that hide even deeper in shame. If the money is going to an online relationship you can’t stop feeding, I wrote about that here: Findom and the debt nobody talks about.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



