
Part of the Debt After Death Hub: This post is one piece of my complete Debt After Death: Complete Guide — what you actually owe when a family member dies, how to stop collector harassment, joint account rules, community property state rules, and the filial responsibility laws collectors invoke to scare you.
The mechanism that makes this true is the probate claims process — see how the notice to creditors deadline legally erases unsecured debts.
Quick Answer: When a parent dies with credit card debt, their adult children almost never owe that debt — not a single penny. Credit card debt belongs to the person who signed the contract and to their estate, not to their children. The exceptions are narrow: you co-signed the account, you’re a surviving spouse in one of nine community property states (see Spouse Dies With Credit Card Debt: Myth vs Reality for how this plays out), or you’re the executor who mishandled estate funds. Collectors know most families don’t understand this — and they count on that confusion.
Expert Context: I’ve been helping families navigate debt after a parent’s death since 1994. In all that time, the single most common financial crime I’ve witnessed isn’t fraud or forgery — it’s collectors calling grieving families within days of a death and implying, strongly but vaguely, that the children are now responsible for the deceased parent’s credit card balances. I’ve watched families write checks they had absolutely no legal obligation to write. This post exists to make sure that doesn’t happen to you.
Your phone rings two days after your mother’s funeral. A debt collector says she owed $14,000 on three credit cards and asks when you’d like to make a payment arrangement. You’re exhausted, heartbroken, and not sure what the law actually says. Here’s what you need to know right now: you almost certainly do not owe that money, and that collector knows it.
Key Terms Defined
Estate: The legal entity that holds everything a person owned when they died — bank accounts, property, investments, and yes, debts. The estate pays the bills, not the heirs.
Executor (also called Personal Representative): The person legally appointed to manage the estate — paying valid debts from estate assets and distributing what remains to heirs. Being the executor does NOT make you personally liable for the deceased’s debts.
Joint Account Holder vs. Authorized User: A joint account holder signed the credit card agreement and is fully liable. An authorized user simply had charging privileges — they never signed the contract and are not liable for the balance.
Community Property: A legal framework in nine states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin) where debts incurred during marriage may be shared by both spouses.
The Core Rule: Debts Die With the Debtor (Mostly)
Getting calls right now? If a debt collector is calling you about a dead relative’s debt, see the emergency crisis guide for exactly what to say and your rights under the FDCPA.
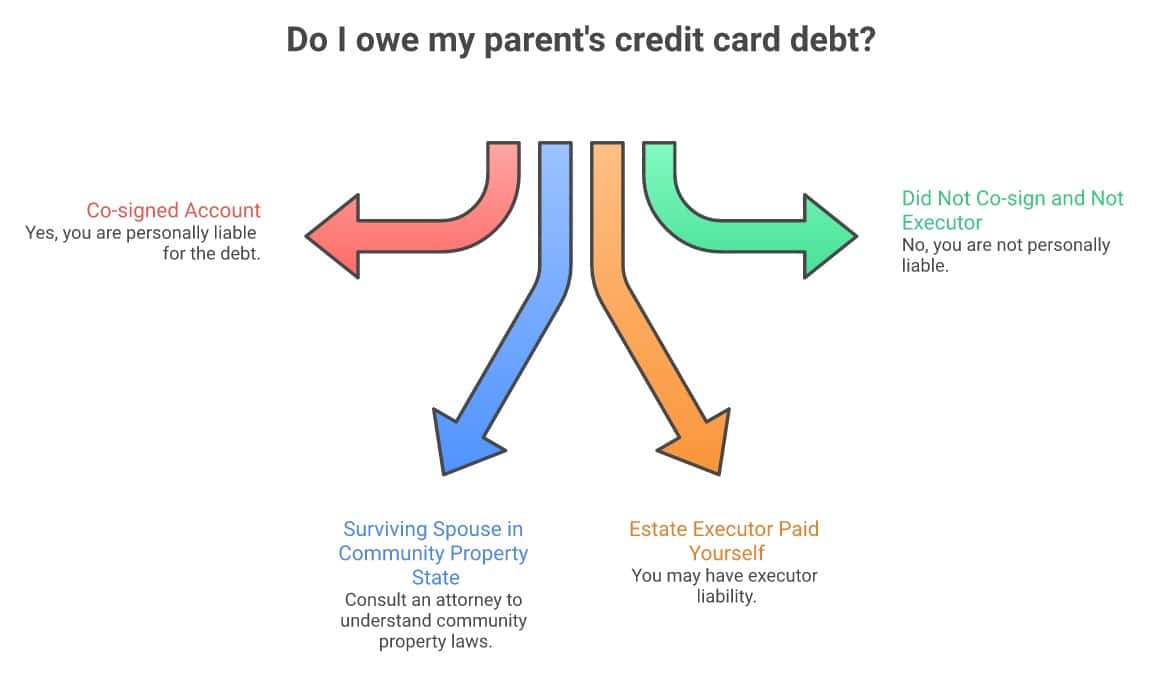
When your parent died, their debts did not transfer to you. That’s not wishful thinking — it’s a fundamental principle of American contract law. According to the CFPB, “family members usually don’t have to pay the debts of a deceased relative from their own money.” The FTC echoes this clearly in its consumer guidance on debts and deceased relatives: generally, no one else has to pay back debts for a person who has died, with limited exceptions.
The debt doesn’t disappear entirely — it becomes a claim against the estate. If your parent had $14,000 in credit card debt and $30,000 in a checking account, the credit card company can file a claim against the estate for that $14,000 before any money flows to heirs. If the estate has no money — if your parent died with more debt than assets — the credit card company typically gets nothing. That loss belongs to the creditor. That’s the deal they signed up for when they extended credit.
What the creditor cannot do is reach into your pocket.
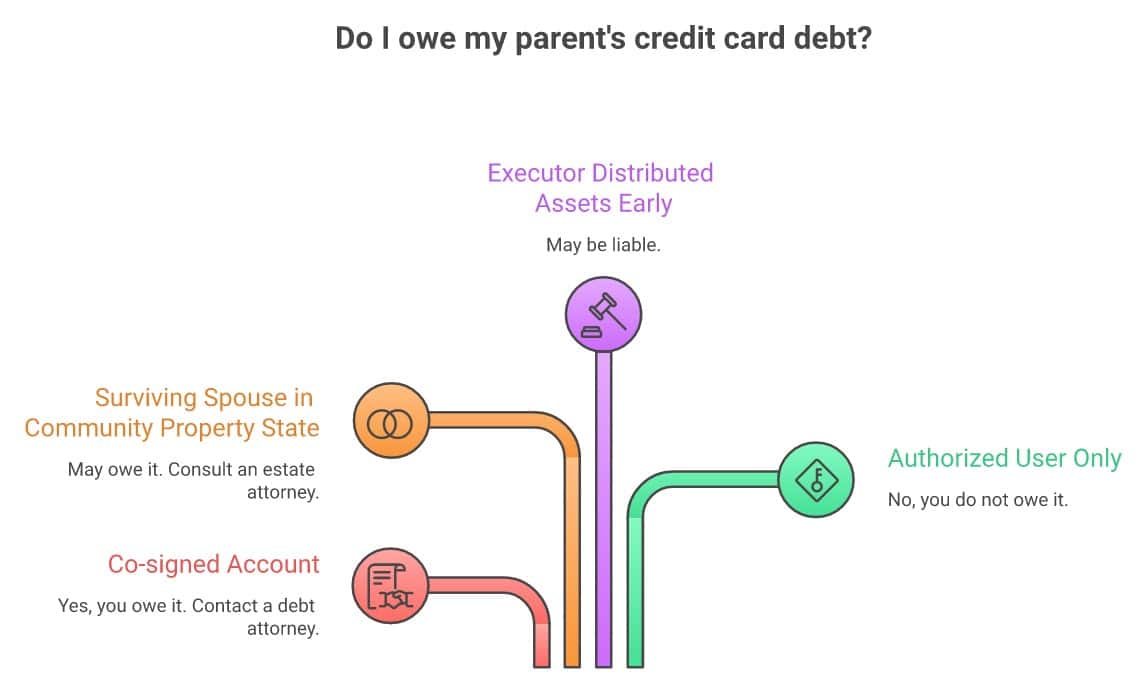
The Three Real Exceptions: When You Actually Do Owe It
I want to be honest with you about this. There are situations where family members do carry real liability. Knowing them protects you in two directions — from paying debts you don’t owe, and from ignoring debts you actually do.
1. You Co-Signed the Account
If you co-signed a credit card application with your parent — your name is on the contract, not just the card — you’re a joint account holder. You owe the debt. Full stop. This is the clearest exception, and it’s the one most likely to catch adult children off guard because many families help aging parents qualify for credit by co-signing without understanding what that means legally.
Being an authorized user is entirely different. If your parent added you to the account so you could use the card, but you didn’t sign the original credit agreement, you’re not liable. The CFPB is explicit about this: authorized users don’t owe the debt.
2. You’re a Surviving Spouse in a Community Property State
This exception applies to spouses, not children — but it’s worth understanding if you’re a surviving spouse reading this.
Nine states follow community property law: Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin. In these states, debts incurred during the marriage may be considered jointly owned by both spouses — which means the surviving spouse may be responsible for paying them even if they never signed the credit card agreement. The rules vary significantly by state, so if you’re a surviving spouse in one of these states, talking with a local estate attorney is worth the time.
Outside community property states, a surviving spouse generally isn’t liable for their deceased spouse’s credit card debt unless they co-signed or were a joint account holder.
3. You’re the Executor Who Distributed Assets Before Paying Creditors
This one is less common but deserves mention. If you were appointed executor of your parent’s estate and you distributed assets to heirs before paying valid creditor claims, you can be held personally liable up to the amount you distributed improperly. This is executor liability, and it’s why probate attorneys always advise: pay the creditors first, then the heirs.
Simply being named executor does not make you liable. Making distributions in the wrong order does.
What Debt Collectors Can and Cannot Legally Do
The Fair Debt Collection Practices Act (FDCPA) and CFPB regulations define exactly who debt collectors can contact and what they can say after a death. (See the full breakdown: A Debt Collector Called About My Dead Spouse’s Debt — here’s what you actually owe.) Under CFPB rules, collectors can contact the executor, administrator, or estate representative to discuss the debt. They can also contact a surviving spouse. They can contact other family members — but only to locate the executor, and generally only once per person.
What they cannot do:
- Imply that adult children are legally responsible when they aren’t
- Pressure non-liable family members to pay from their own funds
- Discuss the details of the debt with anyone except the estate representative or surviving spouse
- Use deceptive, abusive, or harassing tactics — even with estate representatives
The FTC warns specifically that some collectors try to get family members to pay debts they have no legal obligation to pay. This isn’t a theoretical concern. It happens constantly. Collectors aren’t necessarily lying — they may be telling you that the debt exists, which is true. But they’re counting on you not knowing that its existence doesn’t make it your problem.
The Collector Implies: “Your mother had this debt, and as her family, you’ll want to take care of it.”
The Reality: “Taking care of it” is the estate’s job, not yours. This phrasing is designed to trigger your loyalty and grief, not to state a legal fact. Unless you co-signed, you have zero legal obligation.
What to Say When a Collector Calls
You don’t need to be rude or hostile. You just need to be clear. Here’s what I’d tell families to say:
Script for the call: “I am not a co-signer on this account and I am not legally responsible for this debt. Please direct all communications to the estate of [parent’s full name] in writing, addressed to [executor’s name and mailing address]. I am not authorizing any payment from my personal funds.”
Then write it down — the date, the collector’s name, the company name, and what was said. If the calls continue or become harassing, you have the right to send a written cease-and-desist letter. Under the FDCPA, once a collector receives a written request to stop contacting you, they must stop — except to notify you of specific legal actions.
What to Send in Writing
If you’re being pressured, send this by certified mail, return receipt requested:
Cease-and-Desist Letter Template:
[Your Name]
[Your Address]
[Date]
[Collection Agency Name]
[Their Address]
Re: Debt of [Deceased Parent’s Name] (Account ending XXXX)
I am writing to notify you that I am not a co-signer, joint account holder, or otherwise legally responsible for the above-referenced debt. I am requesting that you cease all communication with me regarding this debt immediately, as permitted under the Fair Debt Collection Practices Act, 15 U.S.C. § 1692c(c).
All further communications regarding this debt should be directed to the estate of [Parent’s Name] at [Estate/Executor Address].
Sincerely,
[Your Name]
What About Filial Responsibility Laws?
You may have heard of “filial responsibility laws” — statutes that exist in roughly 30 states and theoretically require adult children to support indigent parents. This comes up in searches about inheriting parent debt, so let me address it directly.
For credit card debt after death, filial responsibility laws are almost never relevant or enforceable. These laws were written primarily for situations where a living parent needs medical care or nursing home support and has no resources. Even in that context, the CFPB has issued guidance clarifying that nursing homes participating in Medicare and Medicaid cannot force family members to assume personal liability for a resident’s costs as a condition of admission.
Credit card companies are not going to invoke filial responsibility law to recover a Visa balance. That’s not what those statutes are for, and enforcement actions under them are vanishingly rare. Don’t let a debt collector raise this as a threat — it almost certainly doesn’t apply to your situation.
The Estate Process: What Actually Happens
When someone dies with unpaid debts, there’s a formal legal process that governs what happens next. Here’s how it generally works:
- The executor opens probate (if required in your state) and inventories the estate’s assets and debts.
- Creditors are notified and given a claim period — typically 3 to 6 months depending on state law — to submit claims against the estate.
- Creditors are paid in priority order from estate assets: funeral expenses and administration costs first, then secured creditors, then unsecured creditors like credit card companies.
- If assets run out before all debts are paid, the remaining unsecured debts go unpaid. The creditors absorb the loss. Heirs receive nothing from those assets, but they also owe nothing from their own pockets.
- Heirs inherit only what remains after debts are settled. You don’t inherit the debt; you inherit whatever is left after it’s addressed.
This process is why it’s worth consulting with a probate attorney if your parent’s estate has significant debt. An attorney can help you navigate the claim period correctly, ensure you’re not distributing assets prematurely, and respond appropriately to creditor inquiries.
Key Takeaways
- Adult children almost never owe a deceased parent’s credit card debt — it belongs to the estate, not the heirs.
- The exceptions are narrow: you co-signed, you’re a surviving spouse in a community property state, or you distributed estate assets before paying creditors.
- Authorized users are NOT liable — only joint account holders who signed the credit agreement are.
- Debt collectors can contact the executor/estate representative. They cannot legally pressure adult children who didn’t co-sign into paying from their own funds.
- If collectors are calling you, use the script above. If they won’t stop, send a written cease-and-desist citing 15 U.S.C. § 1692c(c).
- Filial responsibility laws are rarely enforced for credit card debt — don’t let a collector weaponize them against you.
Bottom Line
If you’re reading this in the middle of grief, with a stack of collection notices sitting next to a sympathy card, I want you to hear this clearly: you are not obligated to write those checks. You loved your parent. That love doesn’t become a legal liability. Credit card companies made a business decision to extend credit; the risk of non-payment is part of their business model, not a burden to be shifted to the bereaved.
The debt belonged to your parent. If the estate can pay it, the estate will. If it can’t, that’s the creditor’s loss to absorb — not yours. (Here’s exactly what happens to debt when someone dies — including what collectors are legally permitted to do.) Grief is hard enough without spending money you don’t owe to a collector who’s counting on your confusion.
If you’re not sure which path forward is right for your family’s full financial picture, take my free Find Your Path quiz — it only takes a few minutes and gives you a personalized starting point.
Frequently Asked Questions
Am I responsible for my parent’s credit card debt after they die?
Generally no — adult children are not legally responsible for a deceased parent’s credit card debt unless they co-signed the account. The debt belongs to the parent’s estate. If the estate lacks sufficient assets to pay it, the credit card company typically absorbs the loss. Collectors may call you, but that doesn’t mean you owe anything from your own funds.
What’s the difference between a joint account holder and an authorized user?
A joint account holder signed the original credit agreement and shares full legal liability for the debt. An authorized user was added to the account for spending purposes only — they never signed a credit agreement and are not liable for the balance. If you were simply added to your parent’s card, you are almost certainly an authorized user, not a joint account holder. Check the original account terms if you’re unsure.
Can a debt collector legally pressure me to pay my deceased parent’s debt?
No. Under the Fair Debt Collection Practices Act and CFPB regulations, collectors can contact the estate’s executor or administrator to collect the debt. They can contact other family members only to locate the executor — not to pressure them into paying. If a collector implies you’re liable when you’re not, that may be a deceptive practice prohibited by the FDCPA. Document the calls and consider filing a complaint with the CFPB at consumerfinance.gov/complaint.
What are community property states and do they affect my parent’s debt?
Community property states — Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin — have laws where debts incurred during a marriage may be shared by both spouses. This is most relevant for surviving spouses, not adult children. If your parent was married when they died and you live in one of these states, the surviving spouse may have some liability. Adult children in community property states are still not responsible for the debt unless they co-signed.
What if I’m the executor of my parent’s estate?
Being the executor does not make you personally liable for your parent’s debts. As executor, your job is to manage the estate — notify creditors, allow the statutory claim period to expire, pay valid creditor claims from estate assets in the proper priority order, and then distribute what remains to heirs. If you distribute assets to heirs before paying creditors, you can be held personally liable for the amount improperly distributed. Consult a probate attorney to navigate this correctly.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If it’s a nursing home bill instead of a credit card, see my crisis guide on what to do when a nursing home bills you personally after your parent’s death — nursing facilities have their own admission-agreement rules that credit card debt doesn’t.



