
Part of the Debt After Death Hub: This post is one piece of my complete Debt After Death: Complete Guide — what you actually owe when a family member dies, how to stop collector harassment, joint account rules, community property state rules, and the filial responsibility laws collectors invoke to scare you.
One key piece of the process: the notice to creditors and the claim deadline that erases unsecured debts.
I’ve been helping people navigate financial emergencies since 1994. I’ve watched families get steamrolled by debt collectors, banks, and creditors in the weeks after a parent dies — not because they were doing anything wrong, but because nobody told them what to do, and they were too grief-stricken to think clearly. The calls come fast. The paperwork is bewildering. And the financial industry is not waiting for you to grieve. Here’s the checklist I wish every family had before they needed it.
When a parent dies with no will and no written instructions — no password list, no account list, no “in case of death” file — you inherit a legal and financial puzzle that most families are completely unprepared to solve. Add debt collectors to the mix and it becomes genuinely frightening. This is the first-30-days roadmap that nobody publishes, because everyone assumes you’ll figure it out. You shouldn’t have to figure it out under pressure.
Key Terms You Need to Know Right Now
- Intestate
- Dying without a valid will. When your parent dies intestate, state law — not your parent’s wishes — determines who inherits what. Probate court oversees the process.
- Probate
- The legal process through which a deceased person’s estate is administered, debts are paid, and assets are distributed. Required in most states when there’s no will or when assets exceed a threshold.
- Estate
- Everything your parent owned at death — money, property, possessions, accounts, and yes, debts. The estate is responsible for paying valid debts. You personally are generally not.
- Executor (or Administrator)
- When there’s a will, the named executor manages the estate. When there’s no will, a court appoints an administrator — often a family member. This person has legal responsibilities and can face personal liability if they handle estate funds incorrectly.
- Creditor Claim Period
- After probate is officially opened and creditors are notified, they have a limited window (typically 3 to 6 months depending on the state) to file a formal claim against the estate. If they miss it, they lose their right to collect.
The First 24 Hours: What Needs to Happen Today
The hours after a parent’s death are disorienting. You’re managing grief, family dynamics, and logistics simultaneously. But certain financial steps cannot wait — because inaction in the first 24 hours can cause real problems that compound over the following weeks.
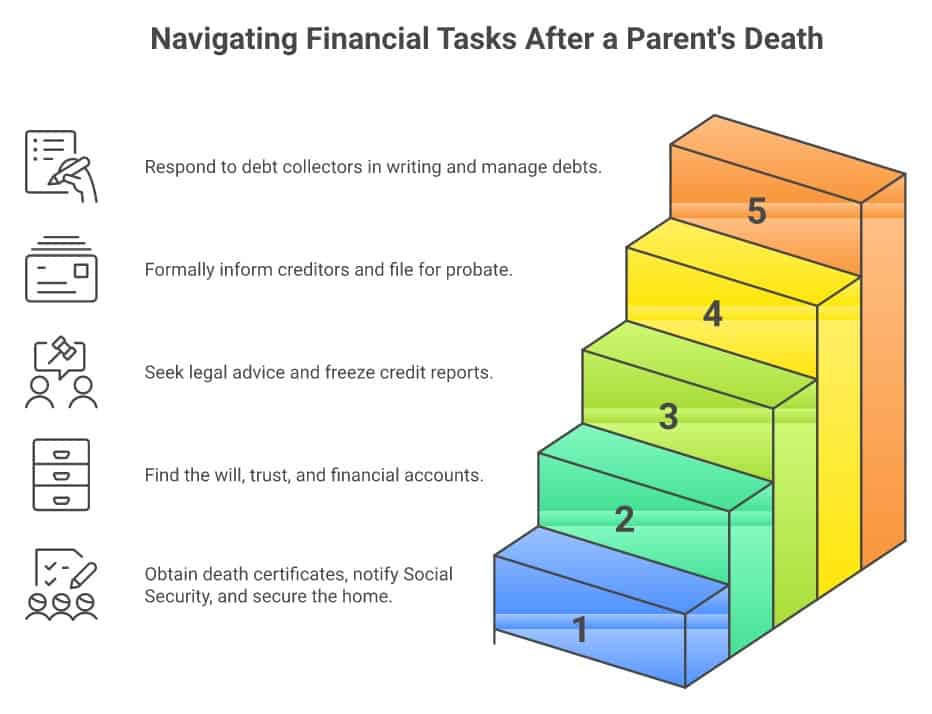
- Order death certificates — order more than you think you need. Get at least 10 certified copies from the funeral home or county vital records office. Banks, each financial institution, the Social Security Administration, the IRS, insurance companies, and the probate court all require originals — not photocopies. Running out means delays measured in weeks.
- Notify Social Security immediately. If your parent was receiving Social Security benefits, any payment that lands in their account after their death must be returned — and SSA will demand it back. The funeral home typically notifies SSA, but verify this happened. Do not spend any Social Security payment received after the date of death.
- Secure the home and physical valuables. Change the locks if needed. Identify and physically secure jewelry, cash, vehicles, and any items of obvious value. Document everything with photos or video before moving anything.
- Note the SSA one-time death benefit. If your parent was receiving Social Security, a one-time $255 death benefit may be available to a surviving spouse or a child who was receiving benefits on the deceased’s record. You must apply — it doesn’t come automatically. You have 2 years.
Days 1–7: Stop, Document, Don’t Pay Yet
This week is about information gathering, not decision-making. Resist pressure from any direction — family members, banks, or collectors — to take action before you have a full picture.
- Search for a will, trust documents, or any estate planning materials. Check filing cabinets, fireproof safes, safety deposit boxes, and digital files. Contact any attorney your parent used — they may have a copy on file. A will found after probate has started can complicate things; find it now if it exists.
- Build a financial account inventory. Gather every account statement you can find — bank accounts, investment accounts, retirement accounts, credit cards, loans, mortgages. Look for mail, email, and any saved login credentials. Note which accounts have named beneficiaries (these pass outside probate).
- Make a list of incoming automatic payments and subscriptions. Your parent’s bank account may have autopay set up for utilities, subscriptions, insurance premiums, and more. Some of these will need to be canceled; others (like homeowner’s insurance on an estate property) may need to continue temporarily.
- Do NOT pay any debts. Not yet. Not to be kind, not to stop the calls, not because a collector sounds urgent. Creditors have a formal claim process and a legal deadline. Paying before understanding the estate’s full picture — and before probate determines the priority order — can create legal problems for you as executor/administrator.
If you are named executor (or appointed administrator) and you pay yourself, pay family members, or pay low-priority creditors before paying valid secured creditors and higher-priority claims, you can become personally liable for those unpaid debts. This is not a hypothetical risk — it is a real legal exposure. Get an estate attorney consultation before paying anything from estate funds.
Days 7–14: Freeze Credit and Get Legal Advice
By the end of week two, you should have a clearer picture of the estate’s assets and debts. Now it’s time to take two critical protective steps.
- Freeze your parent’s credit reports at all three bureaus immediately. Deceased identity theft is a serious and growing problem. Criminals search obituaries and public death records to open fraudulent accounts in the name of recently deceased people. Contact Equifax, Experian, and TransUnion directly to report the death and request a “deceased flag” on the file. Bring a death certificate.
- Consult an estate attorney before doing anything irreversible. Many estate attorneys offer free or low-cost initial consultations. You need to know: whether probate is required in your state for this estate, who has authority to act, and in what order debts get paid. This call is worth more than any other action you’ll take in this process.
- Address the password problem. If your parent left no written password list, you’ll need to contact each institution individually with a certified death certificate and proof of your authority (letters testamentary or letters of administration from probate court). Apple has a Digital Legacy process. Google has an Inactive Account Manager. For financial accounts, the institution’s estate department handles access — expect delays and paperwork.
Days 14–30: Formal Notification and Probate
With legal guidance in hand, you’re now in position to take formal action. This phase is about establishing your legal authority and putting creditors on notice through proper channels.
- File for probate if required. Your estate attorney will advise whether probate is needed. If your parent owned real estate in their name alone, or had assets above your state’s small-estate threshold, probate is typically required. The court will issue “letters testamentary” or “letters of administration” — the document that gives you legal authority to act on behalf of the estate.
- Formally notify creditors in writing. Once probate is open, most states require published notice to creditors in a local newspaper, plus direct written notice to known creditors. This starts the clock on the creditor claim period. Creditors who don’t file within the statutory window typically lose their right to collect from the estate.
- Inventory and protect estate assets. Open an estate bank account (separate from your personal finances — this is critical). All estate funds move through this account. Keep meticulous records of every transaction.
- Respond to debt collectors in writing only. Once you have legal authority, respond to collector contacts in writing and only in your capacity as executor or administrator. Never respond in a personal capacity if you did not co-sign the debt.
When Debt Collectors Call
Debt collectors will call. Some will call within days of the death — they monitor obituaries and public records. Understanding your rights under the Fair Debt Collection Practices Act (FDCPA) is essential. (For a deeper look at what collectors can legally do in this situation, see A Debt Collector Called About My Dead Spouse’s Debt — here’s what you actually owe.)
Under the FDCPA and FTC guidance, debt collectors may contact the executor or administrator of an estate about a deceased person’s debts. They may also contact a surviving spouse in states where community property laws create joint liability. What they cannot legally do is pressure, deceive, or harass adult children who did not co-sign the debt into believing they personally owe it. Source: FTC Debt Collection FAQs
When a collector calls:
- Ask for the collector’s name, company name, mailing address, and the amount they claim is owed.
- Do not confirm any personal liability. Say only: “I am not the debtor. I am handling the estate. Please send all communications in writing.”
- Do not provide your personal financial information, Social Security number, or bank account details.
- Document every call — date, time, caller ID, name of collector, what was said.
- If a collector continues to harass you personally after you’ve made clear you’re not the debtor, they may be violating the FDCPA. Keep records and consult an attorney.
- Do NOT pay a debt just to stop the calls
- Do NOT give a collector access to estate funds without legal guidance
- Do NOT let a collector convince you that you personally owe your parent’s credit cards, medical bills, or personal loans if you didn’t co-sign
- Do NOT ignore written correspondence — some deadlines matter legally
The Legal Reality: Do You Owe Your Parent’s Debt?
Here’s how estate debts are prioritized (order varies slightly by state):
- Funeral and burial expenses
- Estate administration costs (attorney fees, court costs)
- Federal taxes owed
- State taxes owed
- Secured debts (mortgages, car loans)
- Medical debts (in some states)
- Unsecured debts (credit cards, personal loans)
If your parent’s estate runs out of money before reaching credit card debt — which is common — those creditors get nothing. You do not have to make up the difference.
The Bottom Line
Losing a parent is hard enough. The financial chaos that follows — with no will, no password list, and collectors calling — can feel like a second emergency. It doesn’t have to overwhelm you. Get death certificates in bulk, don’t pay anything yet, freeze the credit reports, and talk to an estate attorney before anyone else. The collectors have deadlines and legal constraints. They are not as powerful as they sound on the phone. You have more rights than most families realize — starting with the fact that you almost certainly don’t owe your parent’s unsecured debts personally.
If you’re not sure where to start, find your path here — and let’s figure out the right next step together.
Frequently Asked Questions
Can debt collectors call me about my deceased parent’s debt?
Yes — but only in limited circumstances. Collectors may contact the executor or administrator of the estate. They may not legally pressure adult children who did not co-sign the debt into believing they are personally responsible. Under the FDCPA, using false or misleading representations to collect a debt is illegal. If a collector tells you that you personally owe your parent’s credit cards and that’s not true, that’s a potential FDCPA violation. Document the calls and consult a consumer attorney.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
What happens to my parent’s debt if there’s no estate to pay it?
If your parent died with no significant assets — no home equity, no savings, no investment accounts — creditors generally have no recourse. They can file a claim in probate, but if there’s nothing to pay from, the unsecured debts are discharged. You are not required to make up the difference from your own money unless you co-signed or are a surviving spouse in a community property state.
Do I need a probate attorney, or can I handle this myself?
That depends on the size and complexity of the estate. If your parent owned real estate in their sole name, had significant assets, or had debts in dispute, an estate attorney is worth every dollar. If the estate is small (most states have simplified procedures for estates under $50,000–$200,000), you may be able to use a simplified affidavit process without formal probate. An attorney consultation — even a single hour — will clarify which path applies to your situation.
How do I access my parent’s digital accounts and financial apps if I don’t have the passwords?
Each institution has its own process. For bank accounts, bring a certified death certificate and your letters of administration (from probate court) to the bank’s estate department. For Apple devices and iCloud, Apple has a Digital Legacy program that allows designated legacy contacts or court-ordered access. Google’s Inactive Account Manager works similarly. For apps without a legacy process, the institution’s customer service or estate team handles access requests. Expect delays of weeks to months for some institutions — start these processes early.
What if my parent’s will turns up after probate has already started?
A will found after probate begins can complicate the process significantly, but it doesn’t necessarily invalidate what’s already happened. The will needs to be filed with the probate court immediately. The court will determine whether and how to incorporate it, depending on how far along the process is and the laws of your state. This is one reason to search thoroughly for estate planning documents before probate is filed — once the machine starts, redirecting it takes legal effort and expense.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



