
Quick Answer: Private student loans cannot be discharged through federal forgiveness programs — not IBR, not PSLF, not the IDR account adjustment. But private student loans can be discharged in bankruptcy, and the legal environment has shifted in your favor since 2022. If you are drowning in private student loan debt with no realistic path to repayment, bankruptcy is a legitimate option worth a serious conversation with a bankruptcy attorney.
Expert Context: I’ve been guiding people through debt crises since 1994, and I’ve watched the student loan industry sell a lie for decades: that bankruptcy is impossible for student loans. The truth is more nuanced — and more hopeful — than the lenders want you to know. I’ve seen this trap destroy people’s financial lives unnecessarily.
Part of the Chapter 7 Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
If you’re drowning in private student loan debt and desperately searching for a forgiveness program that applies to you, I need to tell you something the lenders won’t: there is no forgiveness. But there is a way out — and it’s called bankruptcy.
Key Terms Defined
Private student loans: Loans issued by banks, credit unions, or private lenders — not the federal government. Sallie Mae, Navient, Discover, College Ave, and similar companies. These have no connection to federal forgiveness programs.
If Navient serviced your federal loans, you may also be eligible for a payment from the CFPB enforcement action — see the latest on Navient settlement checks going out now.
Federal student loans: Loans issued or guaranteed by the U.S. Department of Education. These qualify for IBR, PSLF, IDR account adjustment, and other federal programs. If your servicer is MOHELA, Aidvantage, or Nelnet, your loans are likely federal.
Undue hardship discharge: The legal standard under 11 U.S.C. § 523(a)(8) for discharging student loans in bankruptcy. You must prove that repayment would impose an undue hardship on you and your dependents.
Adversary proceeding: A separate lawsuit filed inside your bankruptcy case to specifically request discharge of student loans. It doesn’t happen automatically — you have to ask.
The Lie You’ve Been Told About Private Student Loans
For years, borrowers were told that student loans — all student loans — were essentially impossible to discharge in bankruptcy. That was never quite true, but it was close enough to true that most bankruptcy attorneys didn’t even bother trying. The stigma became the policy.
The result? Millions of people with private student loans they cannot possibly repay spent years, sometimes decades, in financial paralysis — too scared to file bankruptcy, too broke to pay, trapped.
The Myth: “You can’t discharge student loans in bankruptcy.”
The Reality: Student loans can be discharged in bankruptcy under the undue hardship standard. Private loans — which have no government attorney fighting against you — are in some ways easier to discharge than federal loans. And the legal environment shifted meaningfully in 2022.
What Changed in 2022 (And Why It Matters for Private Loans)
In November 2022, the Department of Justice and Department of Education issued new guidance changing how government attorneys handle federal student loan bankruptcy cases. Instead of automatically opposing every discharge request, government lawyers were told to evaluate borrowers’ actual circumstances and, where the facts supported it, to stop fighting the discharge.
The DOJ acknowledged something important: there are likely far more borrowers who qualify for undue hardship discharge than currently file for it. The barrier wasn’t legal — it was fear and misinformation.
For private loans, the 2022 guidance doesn’t directly apply — there’s no government attorney on the other side. You’re dealing with a private lender, typically represented by their own lawyers. But the shift in culture matters: bankruptcy attorneys nationwide are now more willing to file adversary proceedings for student loan discharge, and courts are evaluating cases with more compassion than they did a decade ago.
Why Private Loans Are Different (And Not in a Good Way — Until They Are)
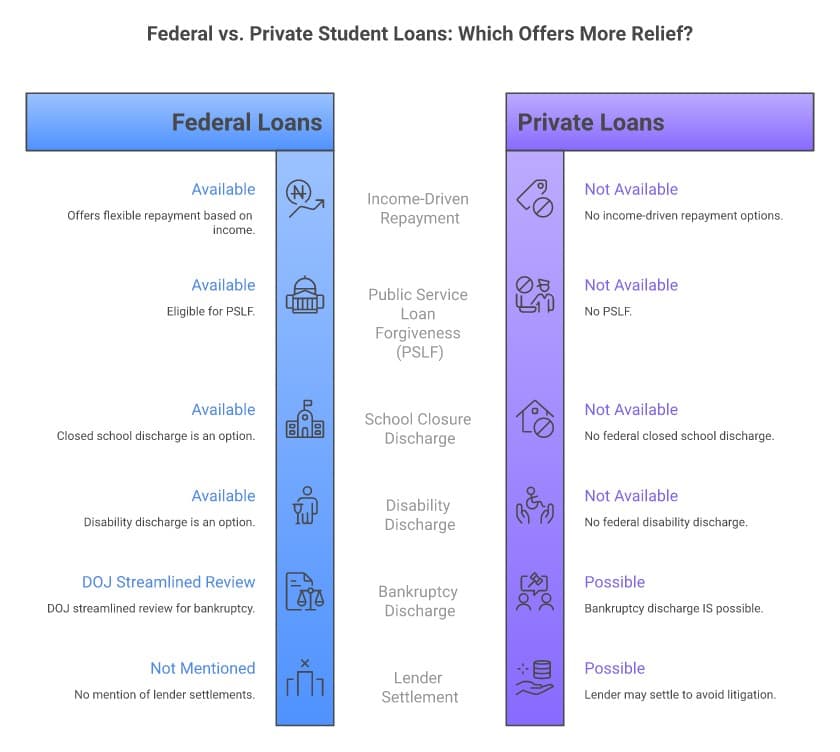
Private student loans occupy a strange middle ground. They’re not eligible for any federal relief program — not income-driven repayment, not Public Service Loan Forgiveness, not the payment pause. Nothing. When federal borrowers had payment relief during COVID, private loan borrowers kept paying.
But in bankruptcy, private loans face a different adversary than federal loans. You’re not fighting the Department of Justice — you’re fighting Sallie Mae’s lawyers or Navient’s collection attorneys. Private lenders, unlike the federal government, have to weigh the cost of litigation against the probability of collecting from someone who genuinely cannot pay. Many private lenders will settle or consent to discharge rather than litigate a case they’re likely to lose.
Important: Not all “private” loans are the same. Some older loans made by private lenders but guaranteed by a state agency or FFELP (Federal Family Education Loan Program) may have different rules. Ask your bankruptcy attorney specifically about the nature of each loan before assuming anything.
The Undue Hardship Test: What You Actually Need to Show
Most courts use the Brunner test, which requires you to show three things:
- You cannot maintain a minimal standard of living while repaying the loan — right now.
- Your financial situation is likely to persist — not temporary hardship, but a durable circumstance (chronic illness, disability, age, limited earning potential in your field).
- You’ve made good faith efforts to repay — you didn’t ignore the loans; you tried.
Courts are not looking for perfection. They’re looking for honesty and evidence. If you’re 58 years old with $170,000 in private student loan debt, earning $42,000 a year, and your field doesn’t pay more than that — you may well have an undue hardship case.
The National Consumer Law Center, which tracks these cases closely, has documented a growing number of successful discharge cases in recent years, including cases where borrowers reached negotiated settlements with lenders mid-adversary-proceeding.
What Forgiveness Programs Actually Cover (Spoiler: Not You)
I want to be direct about this because so many private loan borrowers waste years chasing relief that was never available to them:
Federal Loans ✓
- Income-Driven Repayment (IBR, PAYE, SAVE)
- Public Service Loan Forgiveness (PSLF)
- IDR account adjustment
- Borrower defense to repayment
- Closed school discharge
- Total and permanent disability discharge
Private Loans ✗
- Income-Driven Repayment — not available
- PSLF — not available
- IDR adjustment — not available
- Borrower defense — not available
- Federal disability discharge — not available
- Any forgiveness program — not available
The only federal relief for private loan borrowers is the bankruptcy discharge process — which, ironically, private loans may be better positioned for than federal loans in some circumstances.
What Bankruptcy Actually Does to Private Student Loan Debt
If you file Chapter 7 bankruptcy and successfully discharge your private student loans through an adversary proceeding, the debt is gone. Permanently. No more payments, no more interest accruing, no more collection calls.
If you file Chapter 13, you may be able to reorganize — paying what you can afford over 3-5 years, with remaining balances discharged at the end. This can be powerful for people who have income but can’t sustain the original loan payments.
Even if full discharge isn’t granted, courts sometimes grant partial discharge — eliminating some of the principal or reducing the loan to a manageable amount. Settlement during the adversary proceeding process is also common. Private lenders, looking at a borrower who genuinely cannot pay, often prefer a negotiated outcome to expensive litigation they may lose.
“Bankruptcy rates diminish the social stigma associated with being declared bankrupt. The falling stigma of bankruptcy has been widely cited as a reason why the bankruptcy filing rate increased rapidly in both the UK and US during the early 2000s, despite little change in the number of individuals who might benefit financially from filing.”
— John Gathergood, Debt and Depression: Evidence on Causal Links and Social Stigma Effects (2011)
Gathergood’s research points to something I’ve observed firsthand: the stigma around bankruptcy is the primary barrier — not the law. When people stop being afraid of the word “bankruptcy,” they discover options that were available to them all along.
Free Tool — Debt Stress Test: Is your debt causing more than financial damage? This free 2-minute screening interleaves financial questions with the PHQ-9 clinical depression tool used by doctors worldwide. 49% of debt counseling clients show depression symptoms — find out if your debt stress has crossed that line. Take the Free Screening →
What to Do Next If You Have Private Student Loan Debt You Can’t Pay
- Stop looking for federal forgiveness programs that cover private loans. They don’t exist. Redirect that energy.
- Get a free consultation with a bankruptcy attorney who has experience with student loan adversary proceedings specifically. Not every bankruptcy attorney does this work — ask explicitly before you schedule.
- Document your financial situation. Income, expenses, medical records if relevant, history of payments made. The Brunner test is evidence-based.
- Ask about the Navient private loan settlement precedent. The class action against Navient established that certain private loans — those that exceeded the cost of attendance — may be dischargeable as a matter of contract law, not even requiring the undue hardship test.
- Consider the Find Your Path quiz below — it can help you identify whether bankruptcy, consolidation, or another approach makes the most sense for your full debt picture.
Not sure which debt solution fits your situation? Take the Find Your Path quiz — it asks about your specific debt types, income, and goals and gives you a personalized recommendation.
Key Takeaways
- Private student loans are excluded from every federal forgiveness program — full stop
- Private student loans can be discharged in bankruptcy through an adversary proceeding
- The 2022 DOJ guidance shifted the culture around student loan bankruptcy, and courts are more receptive than they were a decade ago
- Private lenders often prefer to settle rather than litigate an adversary proceeding against a borrower who genuinely can’t pay
- The Brunner test requires showing present hardship, likely persistence, and good-faith repayment history
- A bankruptcy attorney who specifically handles student loan adversary proceedings is worth consulting before you give up
The Bottom Line
If you’ve been searching for a forgiveness program that covers your private student loans, I understand the desperation behind that search. But the honest answer is that no such program exists — and I’d rather tell you that clearly than let you spend another year chasing something that isn’t there. What does exist is a bankruptcy pathway that more people qualify for than anyone realizes, in a legal environment that has genuinely shifted in borrowers’ favor. You are not trapped. You are not out of options. You are, quite possibly, a conversation with the right bankruptcy attorney away from a way out. That conversation is free. Make the call.
Frequently Asked Questions
Can private student loans be forgiven without bankruptcy?
In rare cases, lenders will settle for less than the full amount owed — particularly on very old defaulted loans or loans that may be legally questionable. But there is no program, federal or state, that forgives private student loans the way federal forgiveness programs work. Bankruptcy is the primary legal mechanism for eliminating private student loan debt permanently.
How hard is it to discharge private student loans in bankruptcy?
Harder than discharging credit card debt (which discharges automatically in Chapter 7), but not as hard as many people assume. You must file a separate adversary proceeding and meet the undue hardship standard. A bankruptcy attorney experienced in student loan adversary proceedings can evaluate whether your situation qualifies. Many cases settle before a court ruling.
Does the 2022 DOJ guidance help private loan borrowers?
Not directly — the guidance applies to federal loans held by the Department of Education, not private lenders. But it changed the overall culture around student loan bankruptcy, making attorneys more willing to try and courts more receptive. Private loan borrowers benefit indirectly from a legal environment where student loan discharge is taken seriously again.
What if I can’t afford a bankruptcy attorney?
Many bankruptcy attorneys offer free initial consultations. Some work on payment plans. Legal aid organizations in many states handle bankruptcy cases for low-income borrowers. The National Consumer Law Center maintains resources for finding legal help. Don’t let cost stop you from at least having the conversation.
Will bankruptcy destroy my credit?
Bankruptcy does affect your credit — but research consistently shows that credit scores begin recovering within 12-24 months of filing, and many filers have better credit two years post-bankruptcy than they did while drowning in debt they couldn’t pay. The Federal Reserve has documented this recovery pattern. Defaulting on private student loans damages your credit too — the question is which path leads to recovery faster.
Still hearing that student loans can never be wiped out in bankruptcy? That’s a myth — see what actually changed in 2022 and who qualifies now.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
The same “here’s what’s actually true” lens applies to federal loans too — see why “paused” SAVE loans haven’t stopped growing.



