

If you’re stuck in a house you can’t afford, you have more options than your mortgage servicer will tell you: loan modification, forbearance, short sale, deed-in-lieu, Chapter 13 bankruptcy (to keep the house), or Chapter 7 (to walk away without owing the deficiency). The right choice depends on whether you want to stay or go — and what the math actually says about your future.
Update (April 2026): Queens just had more Q1 2026 foreclosures than every other NYC borough combined — new developments that affect what I wrote below.
I filed bankruptcy in 1990 after a period when the math on my own finances completely broke down. I know the shame of feeling trapped — like the house you once dreamed of owning has become a cage. I’ve also spent 30 years helping people navigate exactly this situation, including running a nonprofit credit counseling organization. What I’ve learned is that the options that feel unthinkable — walking away, filing bankruptcy — are often the ones that actually work. The options that feel “responsible” often drag people into a five-year grind that costs them their retirement and their mental health.
About 3% of mortgaged U.S. homes are “seriously underwater” right now — meaning the homeowner owes at least 25% more than the home is worth, according to ATTOM’s Q4 2025 data. In Louisiana, that number is 10.7%. In Mississippi, 8.3%. And the equity cushion that protected homeowners during the post-pandemic boom has been eroding since mid-2024.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
If you’re reading this, you probably already know your situation. The question is what to do about it. Let me walk you through your real options — not the ones designed to protect the lender.
“The options that feel unthinkable are often the ones that actually work. The math doesn’t care about your feelings — and neither does your mortgage.”
First: What Kind of Problem Is This?
There are two different versions of “stuck in a house you can’t afford,” and the right answer depends on which one you’re in:
You want to keep the house — you just can’t afford the payments
- Temporary hardship (job loss, medical, divorce)
- Rate adjustment made payments jump
- Income dropped but you’re otherwise stable
- The home has equity or sentimental value worth fighting for
You want out — you’re just not sure how to leave
- Deeply underwater (you owe much more than it’s worth)
- The math will never work even if you stretch payments out
- You’ve been making payments for years and the debt barely moves
- The house has become a financial anchor, not an asset
I’m going to cover both scenarios below. Skip ahead to whichever fits your situation.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
If You Want to Keep the House
Option 1: Mortgage Forbearance
If your loan is backed by the federal government — FHA, VA, USDA, Fannie Mae, or Freddie Mac — your servicer is required to offer you forbearance when you request it due to financial hardship. This temporarily pauses or reduces your payments.
Here’s what forbearance is not: it’s not forgiveness. The missed payments get tacked onto the end of your loan or rolled into a repayment plan. You don’t escape them — you defer them. But if your hardship is genuinely temporary (you lost a job and have a new one starting in three months, for example), forbearance can be the bridge you need.
Free help available now. The HOPE Hotline — (888) 995-HOPE — connects you with a HUD-approved housing counselor 24/7 at no cost. They’re independent of your lender and can help you apply for forbearance or modification. The CFPB’s housing counselor locator can also find someone near you.
Option 2: Loan Modification
A loan modification permanently changes the terms of your mortgage — the interest rate, the loan term, or both — to make the payment affordable. HAMP, the government program that ran through 2016, has been replaced by the Flex Modification for Fannie Mae and Freddie Mac loans.
The goal of a Flex Modification is to reduce your monthly principal and interest payment by 20%. If your servicer is required to review you for it (generally when you’re 90–105 days delinquent), they must offer it if you qualify. FHA borrowers have the FHA Payment Supplement option. VA and USDA have their own programs.
Never negotiate a modification alone if you don’t understand mortgage servicing. Servicers have entire loss mitigation departments whose job is technically to help you — but their interests don’t perfectly align with yours. A HUD-approved housing counselor can review any modification offer for free and tell you if it’s actually a good deal.
Option 3: Refinance (If You Have Equity or Qualify for Special Programs)
If your loan-to-value ratio is very high but you’re not deeply underwater, you may still qualify for a refinance. HARP ended in 2018, but its replacements are still available:
- Fannie Mae HIRO (High LTV Refinance Option): No maximum LTV cap on fixed-rate loans originated on or after October 1, 2017
- Freddie Mac FMERR (Enhanced Relief Refinance): Same structure as HIRO
- FHA Streamline Refinance: No appraisal required, limited documentation, existing FHA borrowers only
- VA IRRRL: No credit check or appraisal required, VA loans only
The catch: HIRO and FMERR require the loan to be at least 15 months old and no late payments in the past 6 months. If you’ve already missed payments, this route is likely closed.
Option 4: Chapter 13 Bankruptcy — The Option Nobody Tells You About
If you’re facing foreclosure and want to keep the house, Chapter 13 bankruptcy is the most powerful tool available to you — and it’s the one your mortgage servicer will never mention.
Filing Chapter 13 creates an automatic stay that immediately halts foreclosure, even if a sale is scheduled for tomorrow. You then enter a 3–5 year court-supervised repayment plan that lets you catch up on the mortgage arrears while continuing to make your regular monthly payments going forward.
Chapter 13 can also do something else that almost nothing else can: if your home is worth less than your first mortgage balance, it can eliminate (or “strip”) a second mortgage or HELOC entirely. That’s called lien stripping, and it’s a legitimate, court-approved process.
Chapter 13 also handles your other debts. If you’re behind on the mortgage AND carrying $20,000 in credit cards, Chapter 13 restructures everything in one plan. You’re not just buying time on the house — you’re potentially discharging most of the unsecured debt that’s been drowning you simultaneously.
If You Want to Walk Away
Sometimes the math is just broken beyond repair. You’re deeply underwater — you owe $280,000 on a house worth $190,000, and you live in an area where values aren’t coming back. Staying means pouring money into a hole. The honest answer isn’t “try harder.” It’s “exit strategically.”
The myth: “Walking away is irresponsible and will ruin you financially.”
The reality: Walking away from an underwater asset is what corporations do every time it makes financial sense. It’s called a strategic default. Your lender is a business — they make calculated decisions about risk every day. You can too. The stigma around strategic default is manufactured to protect lender interests, not yours.
Option 5: Short Sale
In a short sale, you sell the home for less than you owe, and the lender agrees to accept that as payment. The process requires lender approval — you can’t do it unilaterally.
The critical thing to get in writing: a full deficiency waiver. This means the lender agrees not to pursue you for the difference between what you owed and what the house sold for. In most states, lenders are not automatically prohibited from collecting that gap. If you don’t have a waiver in writing, you could finish a short sale and still have a debt collector calling you for years.
Option 6: Deed-in-Lieu of Foreclosure
You voluntarily sign the deed to your home over to the lender, and they cancel the mortgage. It’s faster and cleaner than foreclosure — for the lender. That’s your leverage.
Same warning as the short sale: the deed-in-lieu agreement must explicitly state that your debt is fully satisfied. California and Oregon automatically prohibit deficiency judgments after a deed-in-lieu. Most other states don’t. If you’re in Florida, Illinois, or any other full-recourse state, you need that waiver in writing before you sign.
Credit impact is similar to foreclosure — roughly 100+ point drop, stays on your report for 7 years. The benefit is that it’s faster and often less stressful than going through the full foreclosure process.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Option 7: Chapter 7 Bankruptcy — Walk Away Without Owing the Deficiency
Here’s the scenario: you’re in a full-recourse state, you’re deeply underwater, and you want to walk away — but you’re afraid the lender will come after you for the $90,000 difference after they sell the house at auction.
Chapter 7 bankruptcy eliminates that threat. It discharges your personal liability for the mortgage deficiency. Even after the foreclosure eventually happens, the lender can’t pursue you for what you owed versus what they recovered.
Chapter 7 doesn’t save the house — that’s important to understand. The foreclosure will still proceed. But if you also have credit card debt, medical bills, or personal loans that are contributing to your financial picture, Chapter 7 wipes all of it in about 4–6 months.
“I filed bankruptcy in 1990. It wasn’t the end of my financial life — it was the beginning of understanding what had gone wrong. The credit score comes back. The retirement savings you protect by not spending five years ‘grinding it out’ never do.”
The Credit Score Reality Nobody Explains Honestly
I hear this all the time: “I can’t file bankruptcy — it’ll ruin my credit for 10 years.” Let me show you the actual math.
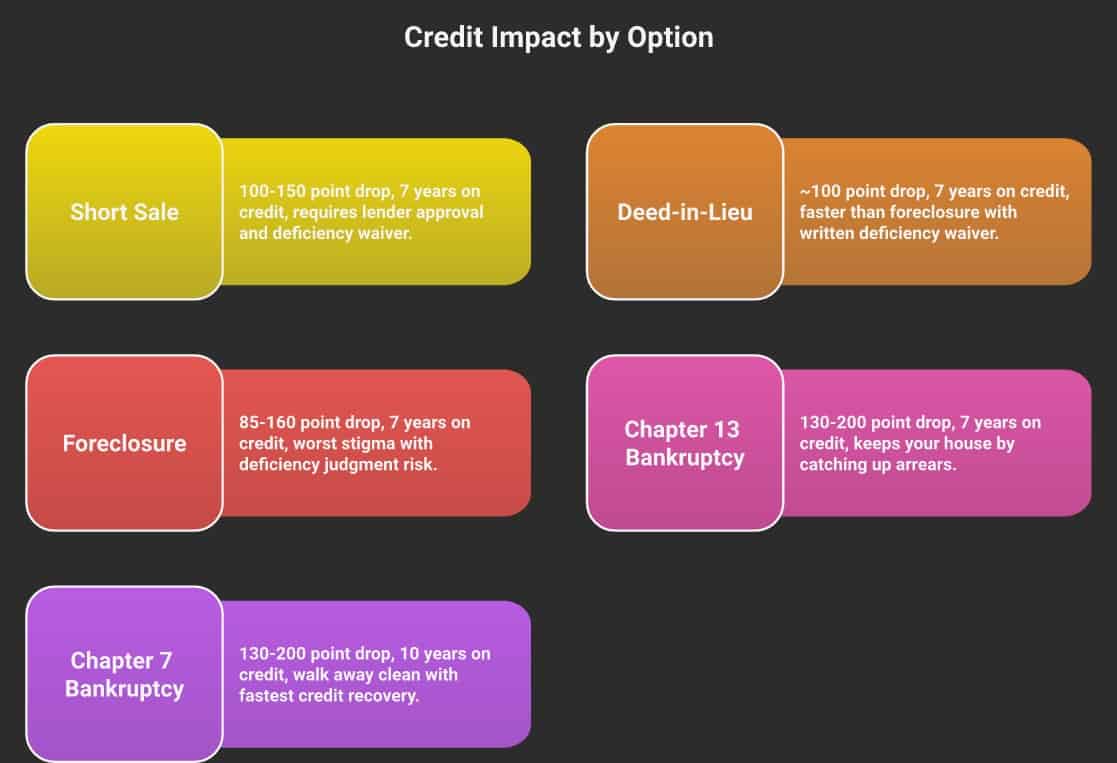
Compare the credit damage:
- Foreclosure: 85–160 point drop, stays 7 years
- Short sale: 100–150 point drop, stays 7 years (same as foreclosure per FICO’s own research)
- Deed-in-lieu: ~100+ point drop, stays 7 years
- Chapter 13 bankruptcy: 130–200 point drop, stays 7 years
- Chapter 7 bankruptcy: 130–200 point drop, stays 10 years — but real-world recovery is often faster because the discharged debts eliminate the ongoing drag on your score
The number that gets cited against bankruptcy is “10 years on your credit.” What doesn’t get mentioned: foreclosure, short sale, and deed-in-lieu all do comparable damage, stay on your report for 7 years, and don’t actually fix your financial situation. Bankruptcy fixes the financial situation. The credit score comes back either way — usually meaningfully within 12–24 months as your debt-to-income ratio improves.
There’s another counterintuitive fact from Nolo’s analysis of FICO research: people with higher starting scores lose more points to foreclosure (140–160 points for a 780 score) than people with lower scores (85–105 points for a 680 score). The people who feel like they have the most to lose actually don’t.
The Question Nobody Asks: What Does Staying Cost You?
Most of the conversation about underwater mortgages focuses on credit scores and monthly payments. Almost nobody runs the retirement math.
If you’re spending $500–$1,000 a month more than you should be on a house you can’t afford — money that’s not going into a 401(k) — you’re not just losing that money. You’re losing what it becomes over 20–30 years of compound growth. That’s potentially $200,000–$400,000 in retirement savings you’ll never recover.
I’ve been saying for years: the hidden cost of grinding through debt instead of resolving it is almost always paid out of retirement. Credit counseling, debt management plans, making-it-work on an underwater mortgage — the credit score recovers either way. The retirement window doesn’t.
Before You Decide
- Know whether you’re in a recourse or non-recourse state — it changes everything about the strategic default math
- Never sign a short sale or deed-in-lieu agreement without a written deficiency waiver
- Talk to a bankruptcy attorney before ruling it out — most offer free consultations, and you may qualify for Chapter 7 without realizing it
- Use a HUD-approved housing counselor (free) before negotiating with your servicer
- Don’t drain your retirement to keep a house that the math says you should leave
Free Tool — Bankruptcy Means Test: Wondering if you qualify for Chapter 7 bankruptcy? The free Bankruptcy Means Test checks eligibility based on your state, household size, and income — including state exemptions. Check My Eligibility →
FAQ
What happens if I just stop paying my mortgage?
Your lender will begin the foreclosure process, typically 90–120 days after your first missed payment. The timeline varies by state — judicial foreclosure states like Florida can take 12–24 months; non-judicial states like California can move in 4–6 months. Stopping payments without a plan exposes you to deficiency judgments in recourse states. If you’re going to stop paying, do it strategically with legal advice, not by default.
Can I keep my house if I file bankruptcy?
Chapter 13 bankruptcy is specifically designed to let you keep your home. You must be able to afford your ongoing mortgage payments and have income to fund a repayment plan for the arrears. Chapter 7 does not save the house — it eliminates your personal liability for any deficiency after foreclosure but doesn’t stop the process.
Is it better to do a short sale or just let the bank foreclose?
The credit impact is nearly identical. A short sale gives you more control over the timeline and outcome, and some buyers/lenders look more favorably on a short sale than a straight foreclosure. The bigger issue is deficiency risk: a short sale with a written waiver is better than foreclosure in a recourse state because you get the waiver in writing. Foreclosure leaves you exposed to a deficiency judgment.
Will being underwater on my mortgage hurt my credit forever?
No. The damage is significant but time-limited. Foreclosure, short sale, and deed-in-lieu all fall off your credit report after 7 years. Chapter 7 bankruptcy falls off after 10 years. But real-world credit recovery typically begins much sooner — most people see meaningful improvement within 12–24 months as the discharged debts stop dragging down their debt-to-income ratio.
What is strategic default and is it legal?
Strategic default means deliberately stopping mortgage payments because the investment math no longer makes sense — typically when you’re deeply underwater and continuing to pay means throwing money away. It is legal. The consequences are the same as any other default: damaged credit and potential foreclosure. The additional risk in recourse states is a deficiency judgment. If you’re considering strategic default in a recourse state, talk to a bankruptcy attorney first — Chapter 7 can eliminate your deficiency exposure before you stop paying.
Part of the Chapter 7 Bankruptcy Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
Bottom Line
Being stuck in a house you can’t afford is a math problem, not a moral failing. Your mortgage servicer has options to offer you — but only the ones that protect the lender’s interests. A HUD-approved housing counselor and a bankruptcy attorney will give you the full picture. The options that feel unthinkable — walking away, filing bankruptcy — are often the ones that actually work. The retirement savings you protect by resolving this quickly are worth more than the credit score points you’re trying to preserve.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If you’re past that point and a foreclosure has already started, here’s my crisis guide on what to do right now if you’re facing foreclosure.



