

Before you sign a debt settlement agreement, your settlement company is legally required to tell you that forgiven debt may be reported to the IRS on a Form 1099-C. Most don’t explain what that means. Here’s what they hope you won’t ask: for most people who settle debt, the insolvency exclusion on IRS Form 982 eliminates the tax entirely. But you only know to claim it if someone tells you it exists.
This same tax trap applies when nonprofit programs erase medical debt — and the same Form 982 escape hatch works.
Update (April 2026): Class action settlement checks have a similar tax trap — most are taxable income, and the IRS will catch unreported payments. File a 1040-X now to avoid penalties.
I ran a credit counseling organization for twelve years and watched thousands of clients go through debt settlement — many with companies that never mentioned the tax consequence until it arrived in the mail the following January. I’ve seen people panic, pay taxes they didn’t owe, and rack up new debt trying to cover a bill that Form 982 would have zeroed out. This post is what I wish someone had handed every one of them before they signed.
The 1099-C arrives in January. The settlement company’s commission arrived months ago. There’s nobody left with a financial incentive to explain what happens next.
What Happens After a Debt Settlement
When a creditor settles a debt for less than you owe — say you owe $10,000 and they accept $4,000 — they’ve forgiven $6,000. Under IRS rules, that $6,000 is technically income. The creditor reports it to the IRS on a Form 1099-C. You receive a copy in January or February of the following year.
If you do nothing, the IRS expects you to include that $6,000 as ordinary income on your tax return. At a 22% tax bracket, that’s a $1,320 tax bill. On a $40,000 settlement, it could be $8,800 — far more than you can afford after fighting your way out of debt.
What Most Settlement Companies Tell You (and What They Leave Out)
Reputable debt settlement companies are supposed to disclose the 1099-C consequence before you sign. Many do — briefly, in the fine print. What almost none of them explain is that most clients who go through debt settlement are already insolvent at the time, which means the insolvency exclusion on Form 982 likely eliminates their entire tax liability. That one-sentence disclosure would save clients thousands of dollars in taxes they never needed to pay.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
The Insolvency Exclusion: The Exit Most People Miss
The IRS provides specific exclusions that eliminate or reduce the tax on forgiven debt. The most important one for most debt settlement clients is the insolvency exclusion.
You are insolvent if your total liabilities exceeded your total assets immediately before the debt was canceled. If you were in debt settlement, you were almost certainly insolvent. That’s why you were doing debt settlement instead of paying the debt.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Insolvency Calculation
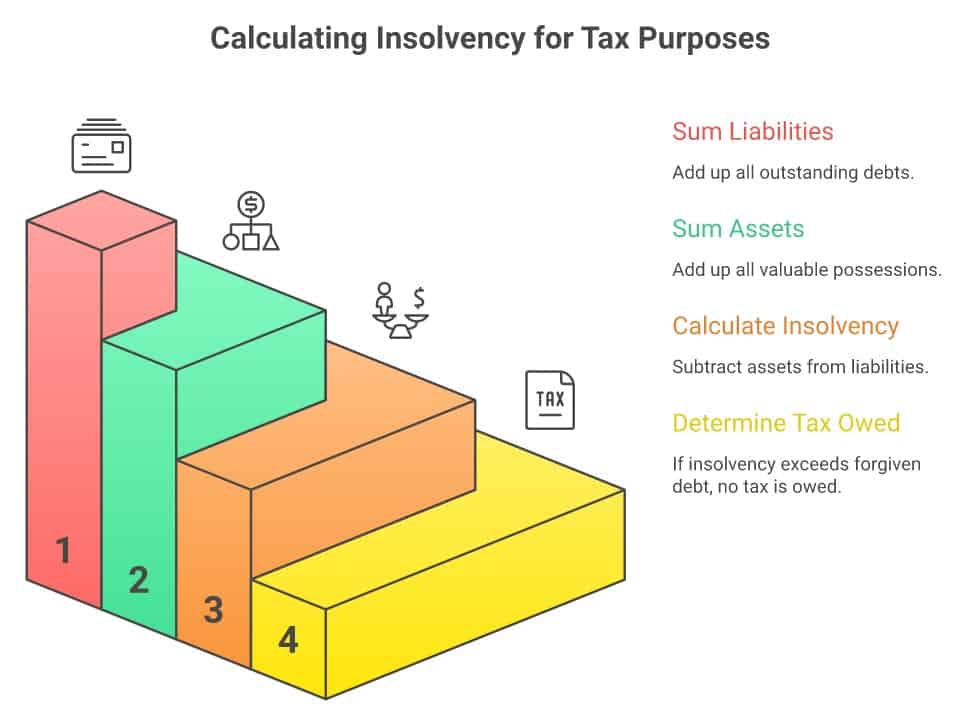
Total liabilities (all debts: credit cards, medical, student loans, car loans, mortgage) minus total assets (bank accounts, retirement accounts, car value, home equity, personal property) = insolvency amount.
If your insolvency amount equals or exceeds the forgiven debt amount, you owe zero tax on the 1099-C. If your insolvency amount is less than the forgiven debt, you only owe tax on the difference.
Example: You settle $15,000 in debt. Your liabilities totaled $60,000. Your assets totaled $40,000. You were insolvent by $20,000. Since $20,000 > $15,000 forgiven, you owe zero tax on the 1099-C.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
How to Claim the Exclusion (Form 982)
You claim the insolvency exclusion by filing IRS Form 982 with your tax return for the year the debt was canceled.
- Download Form 982 from IRS.gov — it’s a one-page form
- Check Box 1b (Discharge of indebtedness to the extent insolvent)
- Enter the excluded amount on Line 2 — the amount of forgiven debt you’re excluding (up to your insolvency amount)
- Attach to your Form 1040 — this is the only documentation required; you don’t submit your insolvency calculation, just keep it in your records
- Do not include the forgiven amount as income on your 1040
If you used a tax preparer who wasn’t aware of your debt settlement situation and included the 1099-C as income, you can file an amended return (Form 1040-X) to claim the exclusion retroactively. The statute of limitations is three years from the original filing date.
The Other Exclusions That Can Help
Insolvency is the most common exclusion for debt settlement clients, but two others may apply:
What to Ask Before You Sign a Settlement Agreement
These are the four questions every debt settlement client should ask before signing:
- “Will you send me a 1099-C?” — Yes, they will. Get confirmation of when and how.
- “Do I need to file Form 982 to avoid taxes on this?” — If they can’t answer this, find a new company or consult a tax professional.
- “Can you provide a written disclosure of the tax consequences?” — If it’s not in writing before you sign, it doesn’t exist.
- “Do you recommend I speak with a tax professional before settling?” — A legitimate company will say yes.
The Retirement Account Rule
One important note: if you had to cash out a 401(k) or IRA to fund your debt settlement, you’ve traded one tax problem for another — and usually a worse one. Early retirement account withdrawals incur income tax plus a 10% penalty, and unlike the 1099-C situation, there’s no exclusion. This is one of the reasons I advise against using retirement funds for debt settlement. The 1099-C tax is often avoidable. The 401(k) early withdrawal tax is not.
If You Already Paid Taxes on Forgiven Debt You Didn’t Owe
If you received a 1099-C in a prior year, included it as income, and paid taxes on it — and you were insolvent at the time — you may be able to recover that money.
File Form 1040-X (Amended U.S. Individual Income Tax Return) to claim the insolvency exclusion retroactively. You have three years from the date you filed the original return, or two years from the date you paid the tax, whichever is later.
This is not complicated to do — Form 982 is a single page. If the amount is significant, a tax professional can file the amendment for a fraction of what you’d recover.
The One Thing to Know Before You Settle
Most people who do debt settlement are insolvent at the time — which means the 1099-C tax consequence the company mentions in its disclosures can likely be eliminated entirely with Form 982. Ask about it before you sign. If you’ve already settled and received a 1099-C, check whether you were insolvent before you write a check to the IRS.
FAQ
Does debt settlement always result in a 1099-C?
Yes, if the creditor forgives $600 or more, they are required by IRS rules to send you a Form 1099-C. Some smaller forgiveness amounts may not generate a 1099-C, but any forgiven debt over $600 will be reported to the IRS and to you.
How do I avoid taxes on a 1099-C from debt settlement?
File IRS Form 982 with your tax return and check Box 1b (insolvency exclusion). Calculate your insolvency at the time the debt was canceled by subtracting your total assets from your total liabilities. If you were insolvent by at least as much as the forgiven amount, you owe zero tax. Keep your insolvency worksheet in your records — you don’t submit it, but you may need it if audited.
What if my debt settlement company didn’t warn me about the 1099-C?
CFPB rules require settlement companies to disclose certain fee and consequence information before you sign. If the company failed to make required disclosures, you may have a complaint worth filing with the CFPB. More practically: if you’ve already received the 1099-C and paid taxes on it, file an amended return (Form 1040-X) to claim the insolvency exclusion if you qualify.
Can I claim the insolvency exclusion if I already filed my taxes?
Yes. File Form 1040-X (amended return) to correct the original filing. You have three years from the original filing date. Include Form 982 with the amended return and claim the exclusion on Line 2.
Is the insolvency exclusion different from a bankruptcy discharge?
Yes, but the outcome is similar — both eliminate the tax on forgiven debt. A bankruptcy discharge uses Box 1a on Form 982. The insolvency exclusion uses Box 1b. The insolvency exclusion requires a calculation showing your liabilities exceeded your assets at the time of cancellation. Bankruptcy is simpler — the discharge itself is the qualifying event.
The Complete Form 982 Guide
For step-by-step instructions on filling out Form 982 and all five exclusion types, see: IRS Form 982: How to Avoid Taxes on Forgiven Debt.
Bottom Line
The 1099-C from debt settlement is real — but the tax bill usually isn’t, because the insolvency exclusion on Form 982 eliminates it for most people who were in debt settlement. Your settlement company collected their fee months ago. They have no financial incentive to explain this to you. Now you know.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



