
Quick Answer: Paying off debt when you have no extra money starts with one question most advice skips: is the math actually fixable with your current income? If it is, negotiate directly with creditors and use government assistance to free up cash. If it isn’t — and for many people it genuinely isn’t — bankruptcy eliminates the debt in months and costs less than most people think. Here’s every real option, ranked by what they actually cost you.
Expert Context: I’ve been helping people with debt since 1994 — and I filed bankruptcy myself in 1990 after my real estate business collapsed. The majority of people who contact me through Ask Steve are in this exact situation: not lazy, not irresponsible, just genuinely out of money. The standard “cut your lattes” advice doesn’t work when there are no lattes to cut. Here’s what does.
Most debt advice assumes you have money you can redirect. But what if you don’t? What if every dollar is already spoken for, the minimums are impossible, and the interest is growing faster than you can pay? That’s not a budgeting problem — it’s a math problem. And math problems have solutions.
The Claim: “If you just budget better and stop spending on things you don’t need, you can pay off any amount of debt.”
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
The Reality: For most people in serious debt, budgets are — as I like to say — a page of lies. You already know what you’re spending. The problem isn’t awareness; it’s that income minus necessities equals less than minimum payments. No budget fixes that equation. What fixes it is changing the equation itself.
Step 1: Stop the Bleeding (Free, Do This Today)
Before anything else, stop the situation from getting worse:
- Call your creditors now. Ask for hardship programs. Most credit card companies have them — reduced interest, lower minimums, skipped payments. They’d rather work with you than send you to collections.
- Prioritize survival expenses. Housing, food, utilities, transportation to work, medication. Everything else is negotiable. Creditors can wait; your landlord and your health cannot.
- Stop paying minimums you can’t afford. This sounds counterintuitive, but making partial payments that leave you unable to eat or keep the lights on isn’t a strategy — it’s harm.
Step 2: Claim Every Dollar You’re Entitled To
Government assistance exists specifically for this situation. These programs free up money that can go toward debt — or simply let you survive while you address the debt separately:
- SNAP (food stamps): Covers groceries for households under 200% of the poverty line. Apply at your state SNAP office.
- LIHEAP: Pays heating and cooling bills. Saves $500-$2,000/year for qualifying households. Find your state program.
- Section 8 housing vouchers: Reduces rent to 30% of income. Long waitlists, but worth applying now.
- Medicaid: Free health coverage under ~138% of poverty in expansion states. Eliminates medical bill risk.
- Dial 211: Call or text 211 from any phone. A real person connects you to every local program you qualify for — utility assistance, food banks, rent help, everything.
Free Tool — Benefits & Free Money Finder: There may be government programs, creditor hardship options, or nonprofit grants available to you. The free Benefits Finder personalizes results by state and situation — SNAP, Medicaid, LIHEAP, and more. Find Your Benefits →
Step 3: Evaluate Your Real Options
Once you’ve stabilized, here are your paths forward — honest trade-offs included:
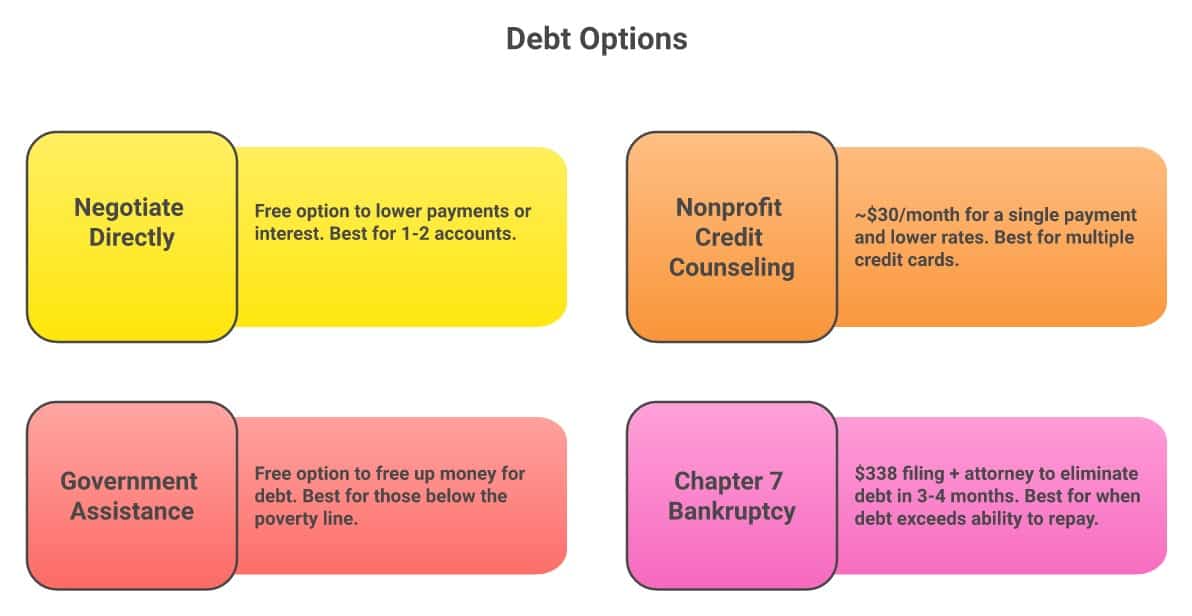
Negotiate Directly With Creditors
Cost: Free
Best for: 1-2 accounts behind, temporary hardship
What happens: You call each creditor and ask for a hardship plan — reduced interest, lower payments, or settlement for less than owed. Many will agree if you’re upfront.
The catch: This only works if your income can cover reduced payments. If the total debt is the problem, not the interest rate, this is a band-aid.
Nonprofit Credit Counseling (DMP)
Cost: ~$30/month management fee
Best for: Multiple credit cards, income can cover reduced payments
What happens: A nonprofit negotiates lower rates and consolidates your payments into one. Takes 3-5 years.
The catch: I ran a credit counseling organization, so I know what I’m about to tell you is uncomfortable for the industry: a 5-year DMP costs roughly $400,000+ in lost retirement savings when you account for the money not going into a 401(k) during those years. That’s the number nobody in credit counseling wants to advertise.
Debt Settlement
Cost: 15-25% of enrolled debt + tax risk
Best for: Already behind on payments, want to avoid bankruptcy
What happens: You stop paying creditors and save up a lump sum to offer as settlement (typically 40-60% of the balance).
The catch: Destroys your credit during the process, you may get sued, and the forgiven amount may be taxable income (the 1099-C “tax bomb”). Settlement companies charge 15-25% of enrolled debt. Run any contract through our Contract Decoder before signing.
Chapter 7 Bankruptcy
Cost: $338 filing fee (fee waivers available) + attorney $1,000-$2,500
Best for: Debt exceeds realistic ability to repay
What happens: Unsecured debt (credit cards, medical bills, personal loans) is eliminated. Done in 3-4 months. Your retirement accounts are 100% protected.
The reality: Federal Reserve research shows that people who file bankruptcy recover faster than those who don’t. Credit scores typically return to average within 2-3 years. I filed in 1990 and rebuilt everything.
Warning: Avoid any company that charges upfront fees for “debt relief” or “debt elimination.” Legitimate nonprofit credit counseling is free for the initial consultation. The FTC and CFPB both warn against for-profit debt relief companies that charge before delivering results.
The Question Nobody Else Will Ask You
Here’s what I’ve learned after helping people with debt for over 30 years: the debt is the symptom, not the problem. Something broke the math — a job loss, a medical crisis, a divorce, a business failure, an addiction, a pandemic. The debt is just the charred wood left after the fire.
So before you pick a repayment strategy, ask yourself: what broke the math? If the underlying cause is still active — if your income still can’t cover your expenses — then no debt repayment plan will work. You’ll just accumulate new debt paying off old debt.
Sometimes the answer isn’t “pay this off slowly.” Sometimes the answer is “eliminate this debt, protect your retirement, and start building forward.” That’s not failure. That’s treating the problem instead of the symptom.
Not sure which path fits your situation? Take the free Find Your Path quiz to get a personalized recommendation based on your income, debt level, and goals — not someone else’s one-size-fits-all advice.
Key Takeaways
- If there’s truly no extra money, the first move is government assistance (SNAP, LIHEAP, 211) to free up cash
- Call creditors directly — hardship programs are free and widely available
- A 5-year DMP costs ~$400K in lost retirement — weigh that before committing
- Chapter 7 bankruptcy costs as little as $338, eliminates debt in months, and protects retirement 100%
- Debt is the symptom, not the problem — address what broke the math first
The Bottom Line
If you’re reading this because the money genuinely isn’t there, you’re not failing — the math is failing. No amount of discipline fixes an equation where expenses exceed income. That’s not a character flaw; it’s arithmetic. The options on this page are real, they’re legal, and they work. Bankruptcy isn’t the end of anything — it’s where my own financial life started over in 1990, and I rebuilt everything from there. Forty-nine percent of people in serious debt show signs of depression, so if you’re feeling crushed, that’s the debt talking, not reality. Deal with the math, protect your future, and let the shame belong to the creditors who designed a system that profits from your desperation.
Frequently Asked Questions
Can I really file bankruptcy if I have no money?
Yes. The Chapter 7 filing fee is $338, and fee waivers are available if your income is below 150% of the federal poverty level. Many bankruptcy attorneys offer payment plans or pro bono services for low-income filers. Legal aid organizations in your area may also provide free bankruptcy assistance — call 211 to find them.
Will paying minimums eventually get me out of debt?
On a $10,000 credit card balance at 24% APR, paying only the minimum takes over 30 years to pay off — and you’ll pay over $25,000 in interest. If the minimum is all you can afford, you’re on a treadmill. The math needs to change, not just the effort.
What if I don’t qualify for government assistance?
Income limits vary by program and state. Even if you’re slightly over the SNAP threshold, you may qualify for LIHEAP, Medicaid, or local assistance programs. Calling 211 is the fastest way to check every program you might qualify for. Additionally, many utility companies, hospitals, and even creditors have their own hardship programs with different income requirements.
Will creditors actually negotiate with me?
Yes — especially if you’re already behind on payments. Credit card companies would rather get 50% of what you owe than 0% after you file bankruptcy. Call the hardship department (not regular customer service) and be honest about your situation. Get any agreement in writing before making a payment.
How do I choose between a DMP and bankruptcy?
Ask one question: can I realistically complete a 3-5 year payment plan while still contributing to retirement? If yes, a DMP may work. If the plan requires sacrificing all retirement savings for years, bankruptcy is likely the better financial decision. The Federal Reserve research is clear: bankruptcy filers recover faster. Take the Find Your Path quiz for a recommendation based on your specific numbers.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



