
Quick answer: Kevin Warsh just told the Senate he plans to keep fighting inflation “without excuse or equivocation.” If you carry variable-rate debt — credit cards, HELOCs, adjustable-rate mortgages — that means your rates aren’t coming down anytime soon. The window to convert variable debt to fixed is right now, before the market prices in “higher for longer” permanently.
Why I’m writing this: I’ve been helping people with debt since 1994 and I ran a credit counseling organization with 70 employees. I’ve watched three Fed chairs come and go, and every time, the people who got hurt worst were the ones who waited to see what would happen instead of locking in what they could control. Today’s hearing isn’t just political theater — it’s a signal about what your credit card statement will look like for the next two years.
What Kevin Warsh Just Said — and What It Means for Your Wallet
On April 21, 2026, Kevin Warsh sat before the Senate Banking Committee as President Trump’s nominee to lead the Federal Reserve. His message was clear: inflation was a policy failure, and he intends to fix it.
In his prepared testimony, Warsh said the Fed must “ensure price stability, without excuse or equivocation, argument or anguish.” He called the post-Covid inflation — which raised prices 25-35% across virtually all income levels — a legacy of policy errors from 2021 and 2022 that the country is still dealing with.
Translation: the next Fed chair is telling you he plans to keep rates where they are — or push them higher — until inflation is thoroughly beaten.
“When someone tells you what they plan to do with interest rates, believe them. Don’t wait to see if they’re bluffing.”
The Math Nobody Is Doing Right Now
Here’s what the political coverage of this hearing isn’t telling you. Every variable-rate debt instrument in America is tied to the federal funds rate. Right now:
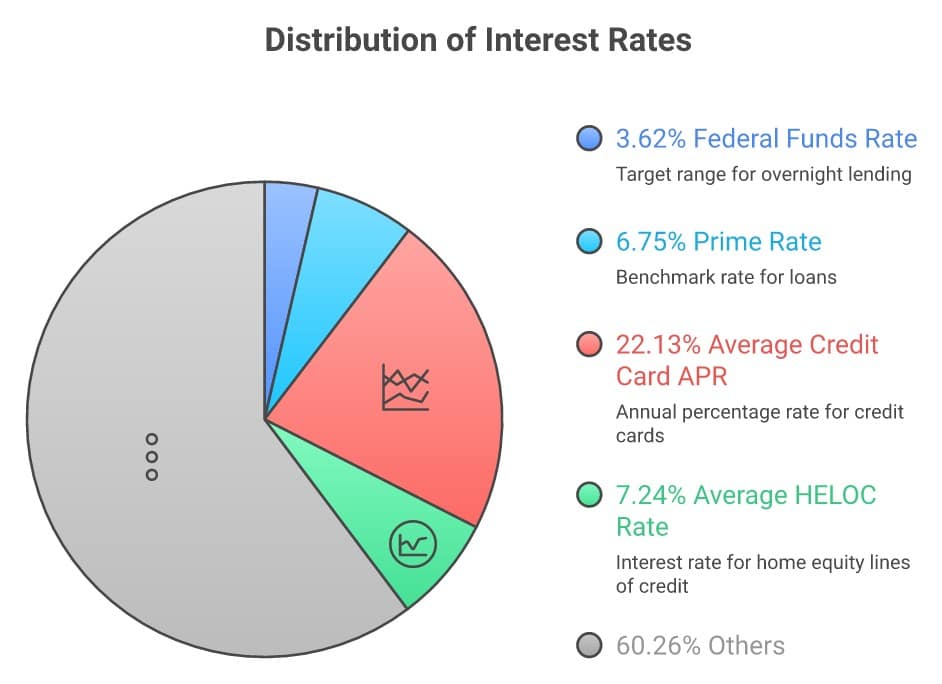
Your credit card APR is the prime rate plus a margin your bank sets. When the prime rate stays at 6.75% — or goes higher — your 22% credit card rate stays at 22% or goes higher. There’s no magic rate cut coming to rescue you.
If Warsh is confirmed and holds steady on rates through 2027 (which is exactly what his testimony signals), here’s what that costs you on a $10,000 credit card balance making minimum payments:
The cost of waiting for rate cuts that aren’t coming:
- At 22% APR, minimum payments on $10,000 take 28+ years to pay off
- You’ll pay roughly $18,000 in interest alone
- Every month you wait for rates to drop costs you another $183 in interest
- Six more months of waiting = $1,100 gone — money that could have gone toward a fixed-rate consolidation
Free Tool — Cost of Inaction Calculator: Thinking about waiting to deal with your debt? The free Cost of Inaction Calculator shows exactly how much more you'll owe — in interest and lost retirement savings — for every month you delay. Calculate the Cost →
I’ve Seen This Movie Before
When I ran my credit counseling organization, I watched this exact pattern play out. The Fed would signal “higher for longer” and people would freeze. They’d keep making minimum payments on variable-rate cards, hoping for a rate cut that was always six months away.
Meanwhile, the math was grinding them down. Not because they were doing anything wrong — because variable-rate debt is designed to benefit the lender when rates stay high. Every month you carry a balance at 22%, your credit card company is having a great quarter. Synchrony Financial just posted a profit surge this week. That profit came from somewhere — and that somewhere is your statement.
Update (July 2026): At his first FOMC meeting, Warsh went further — eliminating forward guidance entirely. What that means for your debt plan is the subject of a separate post.
Here’s what I’d tell my own family today: Stop waiting for a rate environment that Warsh just told you isn’t coming. The next Fed chair has made it clear — he’d rather keep rates high and crush inflation than give you relief on your credit card APR. That’s actually rational monetary policy. But it means you have to make the move, because the Fed isn’t going to make it for you.
Three Types of Variable-Rate Debt to Check Tonight
1. Credit cards (the most common trap)
Almost every credit card in America carries a variable APR. Pull your statements tonight and look at the rate. If it says “prime rate plus” anything — that rate moves with the Fed.
Your move: Call each issuer this week. Ask for a fixed-rate hardship plan or a balance transfer to a fixed-rate card. Many issuers will negotiate — they’d rather keep you paying at a lower fixed rate than lose you entirely. If they won’t negotiate, look into a fixed-rate consolidation that locks your rate regardless of what the Fed does next.
2. HELOCs (the quiet danger)
Home equity lines of credit adjust as often as monthly when the prime rate changes. At 7.24% average, a $50,000 HELOC balance costs you about $362 a month in interest alone. If Warsh pushes rates higher, that number climbs with zero notice.
Your move: Contact your lender about converting your HELOC balance to a fixed-rate home equity loan. Many lenders offer this conversion — you keep the same balance but lock the rate. If your HELOC has an unused line you’re holding “just in case,” be aware that lenders can freeze or reduce that line if home values soften. D.R. Horton, the nation’s largest homebuilder, just reported declining profits today — a signal that housing is cooling. Don’t assume that credit line will be there when you need it.
3. Adjustable-rate mortgages (the ticking clock)
If your ARM has a rate adjustment coming in the next 12 months, you’re about to feel the full weight of “higher for longer.” Check your mortgage documents for the adjustment date and the rate cap.
Your move: Contact your lender about refinancing to a fixed rate before Warsh is confirmed and the market prices in his stance permanently. Yes, fixed rates are higher than they were in 2021. But a known fixed payment you can plan around is worth more than an adjustable payment that could spike with every Fed meeting.
The Bigger Picture: What “Inflation Is a Choice” Really Means
When Warsh says inflation is a choice, he means the Fed chose to let it happen by keeping rates too low for too long. He’s right — the post-Covid inflation that raised your grocery bill 25-35% was a preventable policy failure.
But here’s the part nobody in the hearing room is saying: the cure is also expensive. Keeping rates elevated to kill inflation means every American carrying variable-rate debt pays a tax for a policy mistake they didn’t make. The Fed let inflation run. Now you’re paying for the cleanup through your credit card APR.
What you’re hearing: “Just wait — rate cuts are coming in the second half of 2026.”
What Warsh just told you: He plans to fight inflation “without excuse or equivocation.” Goldman Sachs released its 2026 outlook today projecting elevated inflation through Q4. When both the incoming Fed chair and Wall Street’s biggest bank agree rates stay high — stop waiting and start moving.
What to Think About Doing This Week
- Pull every credit card statement tonight. Identify which cards have variable APRs (most do). Write down the rate and the balance.
- Call your credit card issuers this week. Ask for a fixed-rate hardship plan or balance transfer offer. The worst they can say is no.
- Check your HELOC terms. If you have one, find out when your rate adjusts and whether your lender offers a fixed-rate conversion.
- Review your mortgage. If it’s adjustable, check your next adjustment date. Contact your lender about fixed-rate refinance options.
- Run your numbers. Use the debt relief options calculator to see what a fixed-rate strategy looks like compared to staying on the variable-rate treadmill.
- Don’t panic — act. This isn’t a crisis. It’s a signal. Warsh just told you the plan. The smart response is to convert what you can control to fixed while the market is still digesting his testimony.
The Bottom Line
Kevin Warsh’s confirmation hearing today sent a clear message: rates are staying high to fight inflation. If you carry variable-rate debt — credit cards, HELOCs, adjustable mortgages — waiting for relief that isn’t coming costs you real money every month. The move is to convert variable rates to fixed rates this week, before the market fully prices in “higher for longer.” You can’t control the Fed. You can control whether your debt is tied to their decisions.
FAQ
How does the federal funds rate affect my credit card APR?
Most credit cards have variable APRs calculated as the prime rate (currently 6.75%) plus a margin set by your bank. When the Fed keeps rates high, your APR stays high automatically — no action required on the bank’s part.
Can I ask my credit card company to switch me to a fixed rate?
Yes. Call the number on the back of your card and ask for a fixed-rate hardship plan or fixed-rate balance transfer. Not every issuer will agree, but many will negotiate rather than lose you as a customer.
What happens to my HELOC if the Fed raises rates further?
HELOC rates adjust with the prime rate, sometimes monthly. A rate increase goes directly to your payment amount with little or no advance notice. Ask your lender about converting to a fixed-rate home equity loan to protect against further increases.
Should I refinance my adjustable-rate mortgage right now?
If your ARM adjustment date is within the next 12 months, it’s worth getting a fixed-rate quote now. Compare the cost of refinancing to the potential payment increase at your next adjustment — in most cases, the certainty of a fixed rate is worth the upfront cost.
Is it too late to lock in fixed rates?
No. The market is still absorbing Warsh’s testimony and hasn’t fully priced in a “higher for longer” stance. Once he’s confirmed and sets policy, fixed-rate products will adjust upward. Moving this week gives you the best available terms.
More from today: Goldman released its 2026 inflation outlook today too Also see: D.R. Horton’s earnings dropped the same day.
Update (April 22, 2026): Here’s what “inflation is a choice” looks like in practice — P&G just confirmed price increases on 25% of their products. Here’s the grocery budget trap nobody’s warning you about.
This is what I’m seeing after 30 years in the debt space. The new Fed chair just showed you his cards — he’s keeping rates high to kill inflation, and that means your variable-rate debt stays expensive. Take this as one informed perspective and run the numbers for your own situation. Only you can decide what’s right for you. Use this as input, not instruction. Nobody — not me, not the Fed, not anyone — gets to tell you what to do with your money.
Update: Has now been confirmed as fed chair — read the full breakdown.
Update (July 2026): At his first FOMC meeting, Warsh went further — eliminating forward guidance entirely. What that means for your debt plan is the subject of a separate post.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



