
Quick answer: Synchrony Financial just reported $805 million in quarterly profit — up 20% from last year. If you have a store credit card from Lowe’s, Amazon, CareCredit, PayPal Credit, or JCPenney, that profit came partly from you. And if you opened a “no interest” promotional deal during the holidays, the deferred interest trap is about to spring. Here’s how to check and what to do before it hits. (See also: holiday travel debt trap.) (See also: economy squeezing the middle class.)
Why I’m writing this: I ran a credit counseling organization with 70 employees. Synchrony store cards were one of the most common accounts we saw — and deferred interest was the single most misunderstood feature in consumer credit. People would come in shocked that a $1,200 furniture purchase suddenly had $400 in retroactive interest charges. The “no interest” promotion wasn’t no interest. It was deferred interest. And that distinction has destroyed more household budgets than any late fee ever could.
Synchrony Just Had a Very Good Quarter — at Your Expense
On April 21, 2026, Synchrony Financial reported first quarter earnings of $805 million — a 20% jump in earnings per share over the same quarter last year. Net interest income grew 4% to $4.64 billion. Their net interest margin hit 15.50%.
Let me translate those numbers into plain English: Synchrony made more money from the interest on your store credit card balance than they did a year ago. Their “resilient consumer spending” narrative means your balances are growing and you’re paying more interest on them.
“When a credit card company posts record profits, that money didn’t appear from nowhere. It came from someone’s statement. Check if it came from yours.”
The Deferred Interest Trap You Don’t See Coming
Here’s the part of Synchrony’s earnings call that nobody in the financial press is going to explain to you.
Synchrony issues store credit cards for hundreds of retailers: Lowe’s, Amazon Store Card, CareCredit, PayPal Credit, JCPenney, Rooms To Go, Ashley Furniture, Guitar Center, Mattress Firm, and dozens more. Most of these cards offer “promotional financing” — typically “no interest if paid in full within 6/12/18/24 months.”
That sounds like 0% interest. It’s not. It’s deferred interest.
The critical difference nobody explains at checkout: With deferred interest, interest accrues from day one on the full purchase price. If you pay it off during the promo period — great, they waive it. If you have even $1 left on the promotional balance when the period expires, you owe all the accumulated interest from the original purchase date. Not interest on the remaining $1. Interest on the entire original purchase.
The Math That’s About to Hit Millions of Cardholders
Holiday 2025 was Synchrony’s biggest promotional season. Millions of people opened “no interest for 12 months” or “no interest for 18 months” deals between October and December 2025.
Those 12-month promotions? They expire between October and December 2026. We’re in April. You have months, not years.
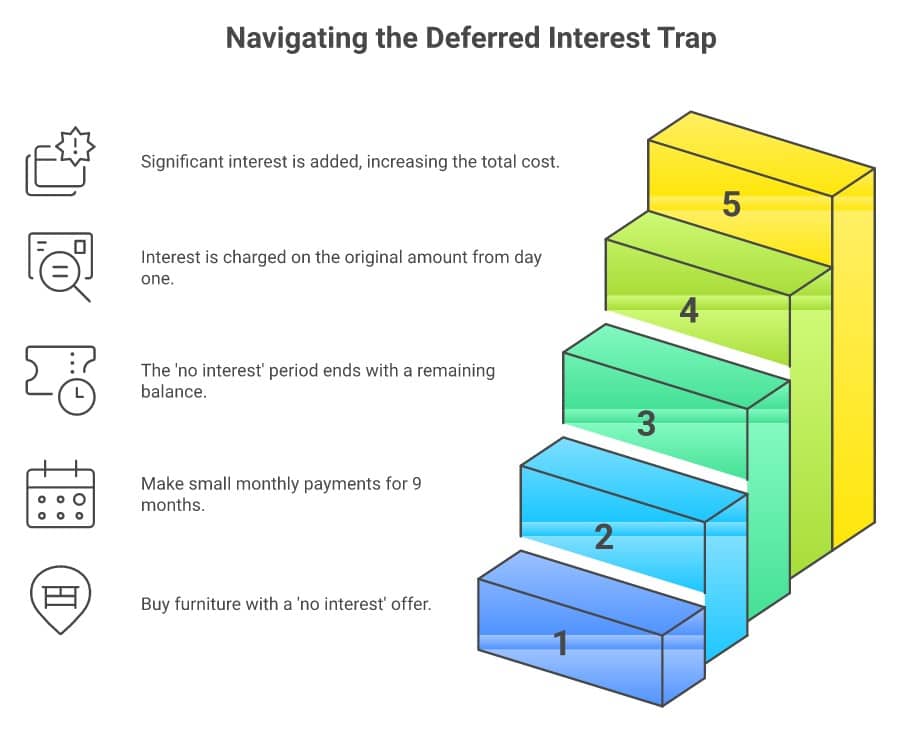
Let me show you what deferred interest looks like on a real purchase:
A $2,000 furniture purchase on a “no interest for 12 months” deal:
- You’ve been making minimum payments of ~$50/month for 9 months
- You’ve paid $450, leaving a remaining promo balance of ~$1,550
- Interest has been silently accruing at 29.99% on the original $2,000 since day one
- When the promo expires with $1,550 remaining: you owe ~$600 in retroactive interest
- That $2,000 purchase just became a $2,600 purchase — and now you’re paying 29.99% on the full balance going forward
What I Saw Running a Credit Counseling Organization
I ran a credit counseling agency. We saw this pattern every single spring. People would come in with their Synchrony or other store card statements, completely blindsided. They’d been making payments. They thought they were in good shape. Then the promotional period ended and their statement showed hundreds of dollars in interest they didn’t expect.
The store clerk at checkout never explained deferred interest. The promotional materials said “no interest.” The monthly statements showed a minimum payment that felt manageable. Everything about the experience was designed to make you think you had more time than you actually do.
This is the part that makes me angry: Synchrony’s $805 million quarterly profit is partly built on the mathematical certainty that a percentage of promotional cardholders won’t pay off their balance in time. They’ve modeled it. They know exactly how many people will get hit with retroactive interest. It’s not a bug — it’s their business model. And you need to know that before your promo period expires.
How to Check If You’re in the Trap Right Now
- Log into every store credit card account you have. Synchrony cards include Lowe’s, Amazon Store Card, CareCredit, PayPal Credit, JCPenney, Rooms To Go, Ashley Furniture, Guitar Center, Mattress Firm, Sam’s Club, Dick’s Sporting Goods, and many more.
- Look for “promotional balance” or “deferred interest” on your statement. It may be a separate section from your regular balance. The promo expiration date should be listed there.
- Check your promo expiration date. If it’s within the next 90 days and you can’t pay the full promotional balance, you need to act now.
- Calculate what the retroactive interest charge will be. Take the original purchase amount, multiply by the APR (usually 29.99%), divide by 12, multiply by the number of months since purchase. That’s what hits your account if you miss the deadline.
What to Do Before the Trap Springs
If you can pay it off: do it now
Don’t wait until the month it expires. Payments can take days to process, and if your payment posts one day after the promo deadline, you owe all the retroactive interest. Pay the full promotional balance at least two weeks before the expiration date.
If you can’t pay it off: call Synchrony today
Call the number on the back of your card and ask for a payment plan that clears the promotional balance before expiration. Some representatives can extend the promotional period or convert to a reduced-interest payment plan. They’d rather get paid at a lower rate than trigger a retroactive charge that pushes you into default.
If the promo already expired: negotiate
If retroactive interest has already been charged, call and ask for a one-time interest reversal. Explain that you’ve been making payments and ask if they’ll reinstate the promotional terms. Not everyone gets a yes, but enough people do that it’s worth 15 minutes on the phone.
If the total debt feels unmanageable
If your store card debt is part of a bigger picture — multiple cards, medical bills, collections — step back and look at the whole situation. Run your numbers through the debt relief options calculator to see all your options, not just the ones Synchrony wants you to consider. Sometimes the smartest move isn’t paying off one card — it’s addressing the whole pile at once.
What the store told you: “No interest for 12 months — just make the minimum payments.”
What the fine print actually says: Interest accrues from day one on the full purchase price. If you don’t pay the entire promotional balance before the period ends — even if you’re $10 short — you owe all accumulated interest retroactively. The minimum payment is designed to NOT pay off the balance in time.
The Bottom Line
Synchrony’s $805 million quarterly profit tells you exactly who’s winning in the store credit card game. If you opened a promotional “no interest” deal during the 2025 holidays, your deferred interest deadline is approaching. Log in today, find your promo expiration date, and either pay it off early or call to negotiate before the retroactive interest hits. The worst time to find out about deferred interest is when it shows up on your statement.
FAQ
Which store credit cards are issued by Synchrony?
Synchrony issues cards for Lowe’s, Amazon Store Card, CareCredit, PayPal Credit, JCPenney, Rooms To Go, Ashley Furniture, Guitar Center, Mattress Firm, Sam’s Club, Dick’s Sporting Goods, and hundreds more retailers. Check the back of your card — if it says Synchrony Bank, these rules apply.
What’s the difference between deferred interest and 0% APR?
With true 0% APR, no interest accrues during the promotional period. With deferred interest, interest accrues from day one but is waived only if you pay in full by the deadline. Miss the deadline by even one day, and you owe all the accumulated interest retroactively.
Can I negotiate with Synchrony to extend my promotional period?
Yes — call the number on the back of your card and ask. Not every representative will agree, but Synchrony sometimes extends promotions or converts to reduced-interest plans for cardholders who ask before the deadline passes.
How much retroactive interest will I owe if I miss my promotional deadline?
Calculate it: original purchase amount times the APR (typically 29.99%) divided by 12, times the number of months since purchase. On a $2,000 purchase after 12 months, that’s roughly $600 in retroactive interest — charged on the original full amount, not your remaining balance.
Should I do a balance transfer to avoid deferred interest?
A true 0% balance transfer card can save you from the deferred interest trap — but check the transfer fee (usually 3-5% of the balance) and make sure the new card is actual 0% APR, not another deferred interest offer. The math only works if the transfer fee is less than the retroactive interest you’d owe.
More from today: the new Fed chair just signaled rates stay high.
I’ve watched deferred interest blindside people for 30 years. It’s not complicated once you see it — but the entire system is designed so you don’t see it until it’s too late. Take this as a heads-up from someone who’s seen it from the inside. Check your statements tonight. Only you can decide what to do next — but you deserve to make that decision with your eyes open, not after the charge shows up.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



