
Quick answer: Goldman Sachs just released its updated 2026 inflation forecast: headline PCE inflation peaking at 3.6% and the first Fed rate cut pushed to September at the earliest. This forecast was written for clients with $10 million portfolios. I’m going to translate what it means for your credit card balance, your minimum payments, and the “wait for rate cuts” strategy that’s costing you real money every month.
Why I’m writing this: I’ve been helping people with debt since 1994. Every time Goldman publishes an inflation forecast, the financial press turns it into a markets story. Nobody translates it into what it means for the person carrying $8,000 in credit card debt at 22%. That’s my job. When Goldman tells its wealthy clients that inflation stays elevated, they’re also telling you — indirectly — that your credit card APR isn’t coming down. The difference is that Goldman’s clients profit from that information. You need to use it differently.
What Goldman Sachs Just Told Its Rich Clients
Goldman Sachs released its updated 2026 economic outlook projecting headline PCE inflation peaking at 3.6% in April, driven by oil price shocks pushing gasoline costs up 12%. Core PCE — the measure the Fed cares about most — was raised to 2.5%.
The bottom line of their forecast: the first Fed rate cut has been pushed from June to September 2026, with a second possible cut in December. Under their baseline scenario, Brent crude averaging $105-115 before easing to $80 in Q4.
What Goldman is telling portfolio managers: position for a longer inflation fight. What I’m telling you: stop waiting for rate cuts to solve your debt problem.
“Goldman writes playbooks for people with $10 million. The same data tells you something too — you just have to read it differently.”
What Goldman’s Forecast Actually Means for Your Debt
Every credit card APR in America is tied to the prime rate, which follows the federal funds rate. Goldman just told you the Fed isn’t cutting rates until at least September — and maybe not until December. Kevin Warsh, the incoming Fed chair, signaled today that he’s in no rush either.
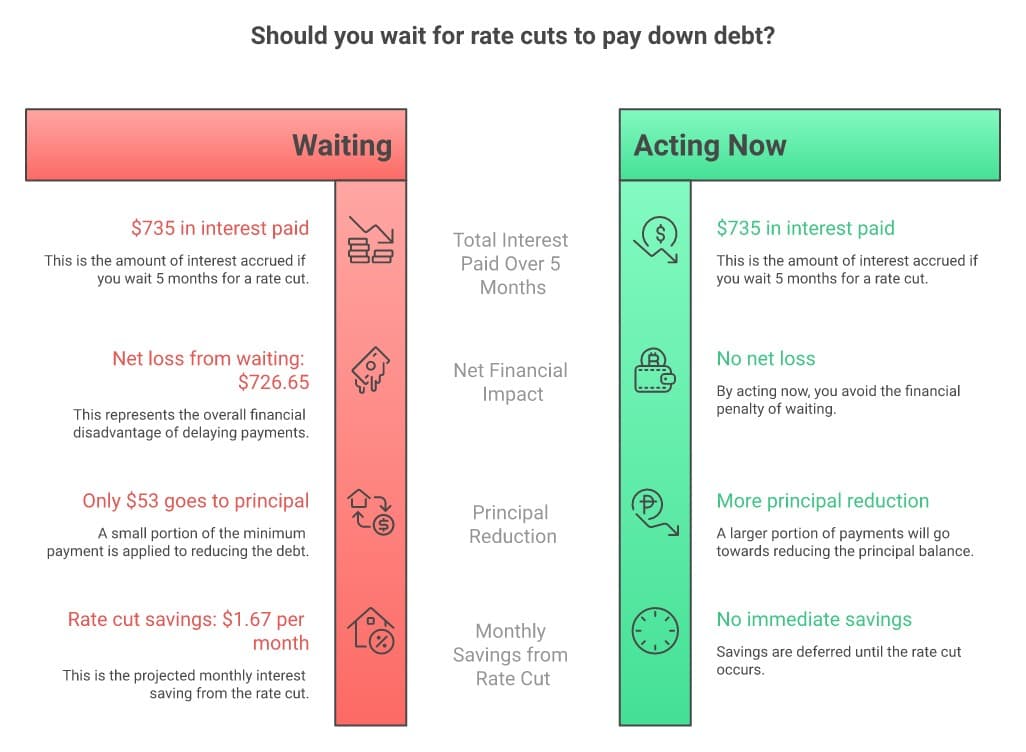
Here’s the math Goldman’s clients never have to think about but you do:
The cost of waiting for rate cuts on $8,000 in credit card debt at 22% APR:
- Monthly interest charge: $147
- If minimum payment is $200, only $53 goes to principal — the rest is interest
- Waiting 5 months for a September rate cut: $735 in interest paid
- Even if the Fed cuts by 0.25%, your APR drops to ~21.75% — saving you $1.67/month
- That rate cut you waited 5 months for saves you less than a coffee per month
Read that last line again. Five months of waiting. $735 in interest. For a rate cut that saves you $1.67 a month. That’s the math nobody is doing for you.
The Rich-People Playbook vs. The Debt-People Reality
Goldman’s clients hear “inflation stays elevated” and they rotate into Treasury Inflation-Protected Securities, commodity funds, and floating-rate loans where they’re the lender, not the borrower. They profit from the same environment that’s crushing your credit card balance.
You can’t do what Goldman’s clients do. But you can use the same information to stop making a costly mistake: waiting for a rate environment that isn’t coming anytime soon.
Here’s the honest math: If Goldman is projecting inflation above 3% through Q3, the Fed isn’t cutting rates meaningfully before Q4 — and even then, a quarter-point cut barely touches your credit card APR. The difference between acting now and waiting six months isn’t a better rate. It’s $800-1,200 in additional interest you’ll never get back.
What the “Wait for Rate Cuts” Strategy Is Actually Costing You
I’ve helped people with debt for 30 years and the “I’ll wait for rates to drop” mindset is one of the most expensive mistakes I see. It sounds rational. It’s not. Here’s why:
What people believe: “If I just keep making minimum payments, rates will drop eventually and my debt will get easier to pay off.”
What the math says: On $8,000 at 22%, minimum payments take 25+ years to pay off. Even two full percentage points of rate cuts — which Goldman isn’t projecting — would shave about 2 years off that timeline. Meanwhile, you’d pay $14,000+ in interest either way. The rate isn’t the problem. The strategy is the problem.
What to Think About Doing With Goldman’s Data
- Stop waiting for rate cuts to make your debt cheaper. Goldman just told you it’s not happening until at least September, and the savings when it does are negligible on consumer debt. The cost of waiting is real and measurable.
- Calculate your personal “cost of waiting.” Take your total credit card balance, multiply by your APR, divide by 12. That’s your monthly interest cost. Multiply by 5 (months until the earliest possible cut). That’s what waiting costs you. Compare it to the cost of acting now.
- Look at fixed-rate alternatives today. A balance transfer to a true 0% APR card or a fixed-rate consolidation loan locks your rate regardless of what the Fed does. The transfer fee (typically 3-5%) is almost always less than 5 months of interest at 22%.
- If debt consolidation doesn’t work for your situation, use the debt relief options calculator to see what does. Maybe it’s a debt management plan. Maybe it’s settlement. Maybe it’s bankruptcy — which Federal Reserve research shows leads to faster financial recovery than grinding it out. The point is: use Goldman’s data to stop waiting and start deciding.
- Protect your retirement while you figure out the debt. Goldman’s inflation forecast means your 401(k) contributions are more important, not less. Never cash out retirement to pay credit card debt. That money is protected in bankruptcy. The credit card debt isn’t protected from compound interest.
The Bottom Line
Goldman Sachs wrote its 2026 inflation forecast for wealthy clients who profit from high rates. The same data tells you something simpler: your credit card APR isn’t dropping meaningfully anytime soon. Every month you wait for a rate cut that saves you $1.67 costs you $147 in interest on an $8,000 balance. Goldman gave you the numbers. Now use them to stop waiting and start moving.
Free Tool — Cost of Inaction Calculator: Thinking about waiting to deal with your debt? The free Cost of Inaction Calculator shows exactly how much more you'll owe — in interest and lost retirement savings — for every month you delay. Calculate the Cost →
FAQ
When will credit card interest rates actually go down?
Goldman projects the first Fed rate cut in September 2026 at the earliest, with a second possible cut in December. Even then, each quarter-point cut reduces your credit card APR by about 0.25% — saving roughly $1.67/month on an $8,000 balance. Meaningful relief from rate cuts alone is unlikely before 2027.
How does Goldman’s inflation forecast affect my debt strategy?
It tells you to stop planning around falling rates. If inflation stays elevated, the Fed holds rates steady, and your variable-rate debt stays expensive. The smart move is to lock in fixed rates now or pursue debt relief options that don’t depend on what the Fed does next.
Should I consolidate my credit card debt if rates aren’t dropping?
Run the math: compare the cost of a balance transfer fee (3-5% of the balance) to your monthly interest charges. If 5 months of interest at your current rate exceeds the transfer fee, consolidating now saves money even if rates drop later.
Why do wealthy investors profit from the same inflation that hurts my debt?
Wealthy investors buy assets that gain value during inflation — TIPS, commodities, floating-rate investments where they’re the lender. When your credit card charges 22%, the card issuer (and its investors) earn that interest. You’re on the paying side of the same trade.
Is it better to wait for a rate cut or act now on my debt?
Act now. Waiting 5 months for a rate cut that saves $1.67/month while paying $147/month in interest is a net loss of over $700. The rate cut doesn’t change your situation. Changing your strategy does.
More from today: Kevin Warsh told the Senate today Also see: Synchrony just reported $805 million in quarterly earnings.
Goldman’s forecast isn’t secret knowledge — it’s just written in a language designed for people who don’t carry credit card debt. I’ve translated it for you: rates stay high, inflation stays elevated, and every month you wait costs you more than any rate cut will save. That’s the math. What you do with it is your call — but at least now you’re making that call with the same information the wealthy clients have.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



