
Quick Answer: The FTC shut down a student loan debt relief operation — NERD Solutions Inc. and ED REF Inc. — that allegedly collected at least $8.8 million by impersonating the U.S. Department of Education, cold-calling borrowers on the Do Not Call list, and charging illegal upfront fees as high as $1,400 a month for loan forgiveness that did not exist. A federal court issued a temporary restraining order on April 13, 2026. The operators face charges under the FTC Act, the Telemarketing Sales Rule, the Impersonation Rule, and the Gramm-Leach-Bliley Act.
Deadline periods like the July 1, 2026 repayment overhaul are prime hunting season for these scams — see what legitimate steps to take before the July 1 changes.
Expert Context: I spent 30 years as an investigative writer tracking financial criminals — Ponzi schemers, embezzlers, corporate fraudsters. I’ve documented how these schemes work from the inside. Student loan relief scams use the same predatory playbook I’ve seen recycled for decades: find people in pain, impersonate authority, collect fees before anyone notices nothing was delivered. The recycling never stops.
The FTC just stopped a company that was cold-calling student loan borrowers, pretending to be the Department of Education, and charging them up to $1,400 a month for loan forgiveness that was never going to happen.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 15): A number you don’t look at is not an asset
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Key Terms Defined
Telemarketing Sales Rule (TSR): An FTC regulation that bans charging upfront fees for debt relief services before results are delivered. Any company that takes your money before actually getting a result has likely broken this rule.
Impersonation Rule: An FTC rule that prohibits impersonating a government agency or business to deceive consumers. Pretending to be the Department of Education or your loan servicer is a federal violation.
National Do Not Call Registry: A federal registry maintained by the FTC. Telemarketers are legally prohibited from calling numbers on this list. The defendants allegedly ignored it entirely.
Gramm-Leach-Bliley Act: A federal law governing how financial institutions handle consumer financial data. It’s notable that this was included — it signals alleged misuse of financial information collected from borrowers.
What the FTC Says Happened
According to the FTC’s complaint, NERD Solutions Inc. and ED REF Inc. — operated by Natalie Rodriguez and Pablo Ortiz — ran this scheme from at least February 2022 through April 2026. That’s over four years of targeting people who were already drowning in student loan debt.
The operation worked in a specific sequence. First, they cold-called consumers, thousands of whom were on the National Do Not Call Registry — a list the law explicitly says telemarketers must honor. Then they impersonated either the U.S. Department of Education or the consumer’s actual loan servicer to establish false credibility. Then came the pitch: false promises of loan forgiveness in exchange for recurring monthly fees.
The Claim: “We work with the Department of Education and can get your loans forgiven for a monthly fee.”
The Reality: The Department of Education does not call you. It does not charge fees for loan programs. Everything these companies “offered” is free at StudentAid.gov. Any company claiming to be the Department of Education on an unsolicited call is running a scam.
Who Was Targeted
People with student loans who were actively searching for relief. That matters. These weren’t random cold calls — the defendants allegedly targeted borrowers who were already in distress, already looking for options. That’s the predatory design: find people at their most vulnerable, promise exactly what they’re looking for, and collect before reality catches up.
The Consumer Affairs report on this action noted that the operation gathered financial information from borrowers during the pitch — which is likely why the Gramm-Leach-Bliley Act (the financial data privacy law) was included in the charges.
The Rules These Operators Allegedly Broke
The complaint charges violations of four separate federal laws:
- FTC Act: The foundational prohibition on deceptive and unfair trade practices.
- Telemarketing Sales Rule: The rule that bans charging upfront fees for debt relief before delivering results — this is the one that catches most debt relief scammers.
- Impersonation Rule: The 2023 FTC rule specifically targeting companies that impersonate government agencies or real businesses.
- Gramm-Leach-Bliley Act: The financial data privacy law — suggesting the operators may have mishandled borrowers’ financial information.
The U.S. District Court for the Central District of California entered a temporary restraining order on April 13, 2026. The Ohio Attorney General’s office also substantially assisted the FTC’s investigation, which suggests the operation had a geographic footprint well beyond California.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
How Student Loan Relief Scams Actually Work
I’ve covered these scams for years and the mechanics rarely change. They exist because the real federal relief programs are genuinely confusing — forgiveness programs, income-driven repayment plans, servicer changes, deferrals — and scammers exploit that confusion by positioning themselves as experts who can cut through it.
The pitch usually sounds like this: “We work directly with the government. We can get your loans forgiven or significantly reduced. All we need is a monthly payment to handle everything for you.” The fees accumulate. The paperwork gets submitted, sometimes just to trigger a deferment that any borrower could get for free. The “forgiveness” never comes.
What the Government Will Never Do: The real Department of Education and your actual loan servicer will never cold-call you with an unsolicited offer. They will never ask you to pay a fee to access a loan program. If someone calls claiming to be from the government and asking for money, that is a scam. Full stop.
What to Do If You Were Targeted
If you paid NERD Solutions, ED REF, or any similar company, here’s what matters right now:
- File a complaint with the FTC at ReportFraud.ftc.gov — this is how the FTC builds redress cases and potentially returns money to victims
- Contact your state attorney general’s office — the Ohio AG already helped with this case, and state-level action often moves faster
- Call your actual loan servicer directly (find the real number at StudentAid.gov) to find out what, if anything, was actually done with your loans
- Dispute any charges with your bank or credit card company if fees were taken recently
- Check if any paperwork was submitted to your servicer — sometimes scammers do file forms, but ones that don’t help or may cause problems
The FTC’s temporary restraining order freezes the defendants’ assets, which is the prerequisite to eventually returning money to victims. The FTC has returned money in past student loan scam cases, so filing a complaint is genuinely worth doing.
The Actual Free Options
Everything these companies charge for is available for free. I want to say that plainly because the scam works by making people believe otherwise:
- Income-Driven Repayment (IDR): Free at StudentAid.gov/idr
- Public Service Loan Forgiveness (PSLF): Free at StudentAid.gov/pslf
- Deferment and forbearance: Free, through your servicer
- Borrower Defense to Repayment: Free at StudentAid.gov
If you were affected by Navient, the $120 million Navient settlement has checks going out now. And if you’ve also looked at the possibility of eliminating student loans in bankruptcy, that’s a real option worth understanding — and it has nothing to do with these scammers.
Is a Student Loan Company Legit? Before paying anyone for student loan help, run them through the Scam-O-Meter and check the Debt Relief Scam Reporter for complaint patterns. If they cold-called you or claimed to work for the government, stop the conversation immediately.
Key Takeaways
- NERD Solutions Inc. and ED REF Inc. allegedly collected $8.8 million by impersonating the Department of Education and charging upfront fees of up to $1,400/month
- A federal court issued a temporary restraining order on April 13, 2026; operators Natalie Rodriguez and Pablo Ortiz face charges under four federal laws
- The real Department of Education never cold-calls borrowers or charges fees for loan programs
- Every federal student loan program is free to access at StudentAid.gov
- Victims should file complaints at ReportFraud.ftc.gov to participate in potential refunds
The Bottom Line
If you’re carrying student loan debt right now, you are already under enough pressure — and scammers know it. They build operations specifically designed to find you at that pressure point and collect money before you realize the help they promised was never coming. The FTC shutting down NERD Solutions and ED REF is one less trap in the market, but it won’t be the last. The single most important protection you have is this: no one you didn’t call first should ever be charging you to access federal loan programs. Those programs exist, they’re real, and they’re free. Your debt is a math problem, not a reflection of your worth — and the solution is out there without paying anyone $1,400 a month for nothing.
Frequently Asked Questions
How do I know if a student loan company is legitimate?
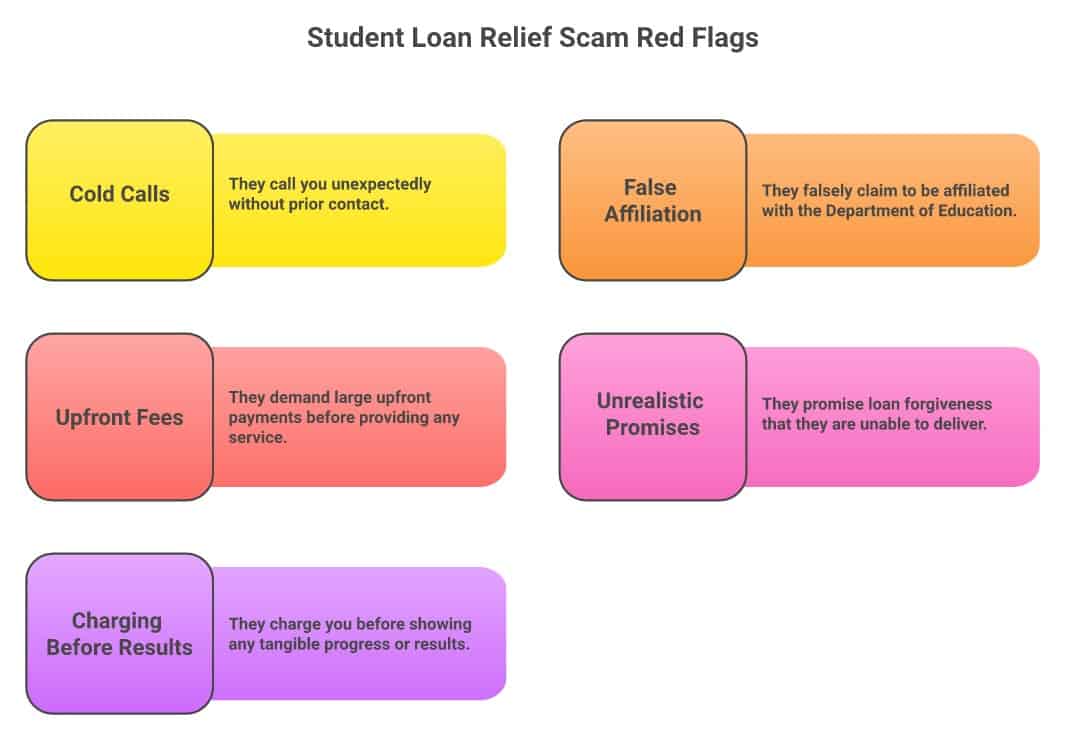
Legitimate organizations will never cold-call you with unsolicited offers, claim to work for or be affiliated with the Department of Education, or charge fees before delivering results. Any upfront fee for student loan relief is illegal under the FTC’s Telemarketing Sales Rule. Verify any company through the FTC’s complaint database and your state attorney general’s office before paying anything.
What are the signs of a student loan relief scam?
The clearest red flags: an unsolicited call, claims of government affiliation, promises of immediate or guaranteed forgiveness, upfront fees before any results, and pressure to act immediately. Real federal programs have application processes — they don’t call you with offers.
Can I get my money back if I paid a student loan scam?
File a complaint at ReportFraud.ftc.gov and with your state AG immediately. When the FTC secures a judgment, it often returns money to victims who filed complaints. Also dispute the charges with your bank or credit card company if the payments were recent — you may have more recourse there than you expect.
Is it illegal for student loan companies to charge upfront fees?
Yes. The FTC’s Telemarketing Sales Rule prohibits debt relief companies from collecting any fee until they’ve actually delivered the promised results. Charging before results = illegal. Full stop.
What can the Department of Education actually do about my loans?
The Department of Education administers federal loan programs including income-driven repayment, Public Service Loan Forgiveness, and borrower defense to repayment. All of these are free to apply for at StudentAid.gov. No company can do anything through these programs that you can’t do yourself for free.
Part of the Debt Scam Alert Hub: This post is one piece of my complete Debt Relief Scams guide — the red flags to know, how to research any company, and what the FTC and CFPB data show about the most common fraud patterns.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



