

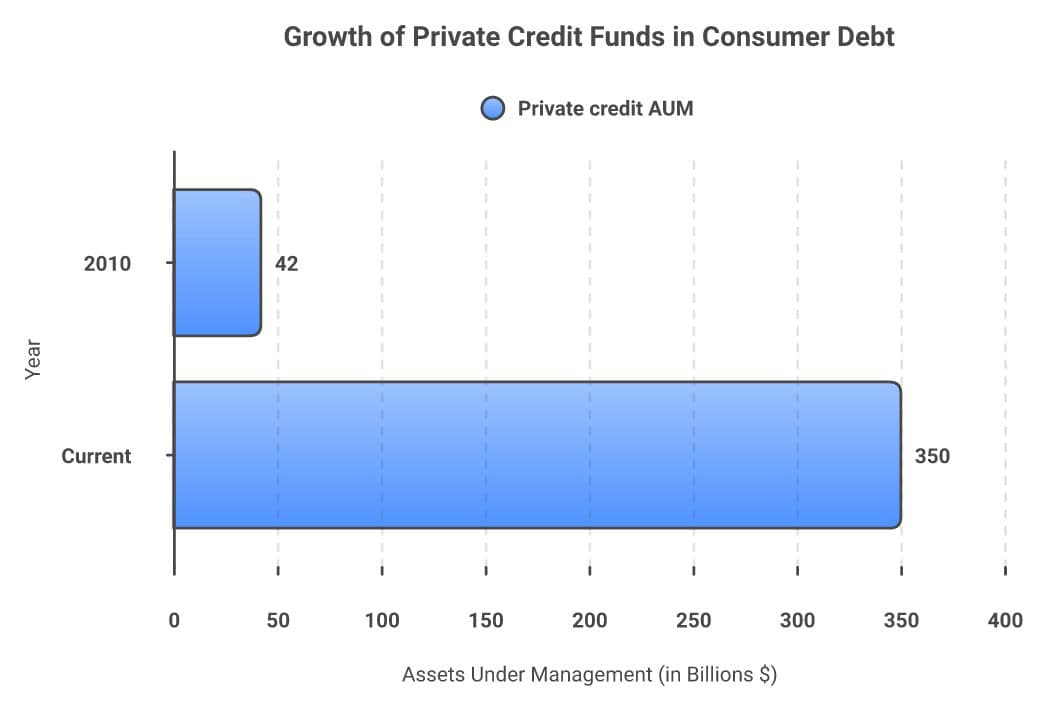
Quick Answer: Private credit firms — hedge funds, private equity, and shadow lenders outside the banking system — now hold $350 billion in consumer debt, up $150 billion since 2019. These firms buy your credit card balances, personal loans, and fintech debt from the companies that originally issued them. When these investors get squeezed, collection gets more aggressive because they need returns. Your rights under the FDCPA don’t change when your debt gets sold — but the entity trying to collect may not know that.
Expert Context: I’ve been tracking who holds consumer debt since 1994 — and I’ve watched the same pattern repeat every cycle. When debt moves from regulated banks to less-regulated investors, collection practices get worse. I saw it after 2008 when junk debt buyers flooded the market. This is the same playbook, bigger numbers, less oversight.
If you have a credit card, a personal loan, or a buy-now-pay-later balance, there’s a growing chance that a private credit fund — not a bank — holds your debt right now. Private credit firms held $350 billion in consumer loan balances last year, up from less than $200 billion in 2019. And CNN reported this week that skittish investors in private credit are asking for their money back — which means the funds holding your debt are under pressure to generate returns fast.
What Is Private Credit and Why Should You Care?
When you get a credit card from a bank, your bank is regulated. Federal examiners check their books. The CFPB can fine them. There are rules about how they contact you, what they can report, and how they collect.
Private credit is different. These are investment funds — firms like Blue Owl Capital, Apollo, Blackstone, and Ares — that raise money from wealthy investors and pension funds, then use it to buy or fund consumer loans. They operate outside the traditional banking system. Wall Street banks are fighting to get back into this business because private credit has been so profitable.
Here’s a real example from this month: Bilt, a rent rewards fintech, moved $1.2 billion in credit card balances with funding arranged by Blue Owl Capital, Stone Point Capital, and Goldman Sachs. That means your Bilt credit card balance isn’t held by a bank — it’s held by a private equity fund.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Key Terms Defined
Private Credit: Non-bank lending by investment funds that raise capital from institutional investors. Unlike banks, these funds are not subject to the same federal examination and capital requirements. The market grew to $1.8 trillion globally as of 2025.
Debt Buyer: A company that purchases delinquent debt from the original lender at a discount — often pennies on the dollar — then attempts to collect the full amount. Private credit funds are increasingly acting as or funding debt buyers.
Why the Squeeze Matters to You
Private credit was Wall Street’s hottest investment for years. Now it’s showing cracks. Fortune called it a “$265 billion meltdown.” JPMorgan CEO Jamie Dimon warned of “weak underwriting” and said losses will be worse than people expect if there’s a credit cycle.
When the investors behind these funds want their money back, the fund managers need to generate cash. Fast. And the assets they’re sitting on are your loans.
What this means in practice: When a bank holds your debt, they have long time horizons and multiple business lines. They can afford to work with you. When a private credit fund holds your debt and their investors are pulling money out, they have one lever: collect harder. That means more aggressive calls, faster escalation to lawsuits, and less willingness to negotiate reasonable payment plans.
Your Rights Don’t Change — But the Collector’s Behavior Might
This is the critical thing to understand: no matter who holds your debt, your rights under the Fair Debt Collection Practices Act are the same. A private equity fund collecting on your credit card balance has to follow the exact same rules as a bank-hired collector.
But here’s what I’ve seen in 30 years: when debt changes hands — especially to entities that are under financial pressure — collection practices tend to push legal boundaries. The debt buyer doesn’t always know (or care about) the original terms. They may not have complete documentation. They may try to collect amounts you don’t legally owe.
- You have the right to demand debt validation — proof that the debt is yours and the amount is correct. Use the free Debt Validation Letter Generator
- You have the right to stop collector calls — a written cease-and-desist letter limits them to written communication only
- You have the right to dispute inaccurate reporting — if a debt buyer reports wrong information to credit bureaus, you can challenge it
- You have the right to sue for FDCPA violations — collectors who break the rules can be held liable for damages
How to Find Out Who Holds Your Debt
- Check your credit card or loan statements for the current servicer name
- Pull your free credit report at AnnualCreditReport.com — look for unfamiliar company names reporting on your accounts
- If a new company contacts you about an old debt, demand a validation letter before paying anything
- Search the company name in the Scam-O-Meter to check their complaint history
The Claim: “If your debt gets sold, you owe the new company whatever they say you owe.”
Related: Does a Debt Collector Have to Prove the Debt? · How to Verify a Debt Collector Is Legitimate.
The Reality: You owe the original amount under the original terms. Debt buyers frequently add fees, inflate balances, or attempt to collect on debts past the statute of limitations. Always demand written verification of the amount, the original creditor, and the date of last activity before paying anything.
Key Takeaways
- Private credit funds now hold $350 billion in consumer debt — and they’re under financial pressure from their own investors
- When these funds get squeezed, they collect harder on the debt they hold — your loans, your credit card balances
- Your FDCPA rights don’t change when debt changes hands — but you may need to enforce them more actively
- If a new company contacts you about a debt, demand validation before paying a cent
- The shift from bank-held to fund-held debt means less oversight and more aggressive collection tactics
The Bottom Line
If you’re dealing with collectors who seem more aggressive than they used to be, you’re not imagining it. The money behind your debt has changed owners — from regulated banks to pressured investment funds that need returns now. That doesn’t change your rights, but it does mean you need to know your rights and be willing to use them. Demand validation. Document every contact. And if the math is broken and the debt is unmanageable, know that bankruptcy filers recover faster than those who struggle through. Your debt found a new owner. You can find a new start.
I’ve been watching debt change hands for 30 years — from banks to junk debt buyers to private equity funds. The names change, the pattern doesn’t. Take this as one informed perspective from someone who’s seen every version of this story. Only you know your full situation. Use this as input, not a directive.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
Frequently Asked Questions
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Can a private credit fund collect on my debt differently than a bank?
No. The FDCPA applies to all third-party debt collectors regardless of who funds them. If a private credit fund or its collection agent violates the law — calling at prohibited hours, using threats, misrepresenting amounts — you can file complaints with the CFPB and your state attorney general, and potentially sue for damages.
How do I know if a private credit fund holds my debt?
Check your latest loan or credit card statement for the servicer name. If it’s a company you don’t recognize — especially a name with “Capital,” “Partners,” or “Holdings” in it — that’s a sign your debt was sold or funded by a private credit entity. Pull your credit report and look for unfamiliar reporting entities.
Should I be worried about buy-now-pay-later debt?
Yes. BNPL platforms like Affirm, Klarna, and Afterpay are heavily funded by private credit. If the private credit market tightens further, these platforms may reduce credit availability or accelerate collection on late payments. If you have BNPL balances, prioritize paying them down.
Does this affect my mortgage?
Mortgages sold to Fannie Mae or Freddie Mac have federal protections regardless of who services them. But non-conforming loans, HELOCs, and second mortgages can be held or funded by private credit. Check with your servicer if you’re unsure about your loan’s ownership.
What should I do right now?
Pull your credit report, identify who holds each of your debts, and make sure you have documentation. If any collector is being aggressive, know your rights — start with the FDCPA violation examples page and use the Debt Validation Letter Generator if you’re being contacted about a debt you don’t recognize.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



