
Quick Answer: The SBA’s own COVID EIDL program rules did not require personal guarantees on loans under $200,000. The CARES Act specifically authorized the SBA to waive personal guarantees on EIDL loans and advances of $200,000 or less. If you signed one anyway — and many borrowers did — whether it’s enforceable is a legal question worth real money to answer before you pay a dime to Treasury.
If you’re weighing legal help, here’s how to find the right attorney for your EIDL — and how to avoid the “loan relief” scams targeting EIDL borrowers.
For a crisis-focused walkthrough of what happens step by step when you default — including the Treasury referral timeline, the 30% penalty, and your full range of options — see: I Can’t Repay My SBA EIDL Loan. What Happens to Me?
Related crisis help: if your business closed and you personally guaranteed the loan, here’s exactly what to do right now — before you sign or pay anything.
Expert Context: I filed bankruptcy myself in 1990 after my real estate development company failed. I know what it feels like to sit across a table wondering whether you’re personally on the hook for a business debt. I’ve spent 30 years since then helping people figure out what they actually owe versus what creditors claim they owe — and the gap is often wider than anyone expects.
If you took out a COVID EIDL loan under $200,000, your business has since closed, and you’re now getting letters from the U.S. Treasury demanding payment — with tens of thousands in “administration costs” tacked on — you’re not alone, and you need to understand exactly where you stand before you respond.
I’m hearing from more and more people in exactly this situation through Ask Steve. The question keeps coming back to the same thing: I signed a personal guarantee on a loan that wasn’t supposed to require one. Am I stuck?
The answer is: maybe not. But finding out requires an attorney, not a chat window.
For a crisis-focused walkthrough of what happens step by step when you default — including the Treasury referral timeline, the 30% penalty, and your full range of options — see: I Can’t Repay My SBA EIDL Loan. What Happens to Me?
Key Terms Defined
Personal Guarantee: A legal commitment that makes you — the individual — personally liable for a business debt if the business can’t pay. Without one, creditors can only pursue business assets, not your personal wages, tax refunds, or bank accounts.
EIDL (Economic Injury Disaster Loan): SBA disaster loans offered to small businesses during COVID-19. Maximum $2 million, with terms up to 30 years at 3.75% interest.
Treasury Cross-Servicing: When the SBA refers a defaulted loan to the U.S. Department of the Treasury’s Bureau of Fiscal Service for collection. Once transferred, the SBA can no longer negotiate with you — Treasury handles everything, and a 28-30% administration fee is added to your balance.
Treasury Offset Program (TOP): The mechanism Treasury uses to intercept federal payments owed to you — including tax refunds and Social Security benefits — to recover the debt.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
What the SBA’s Own Rules Actually Said
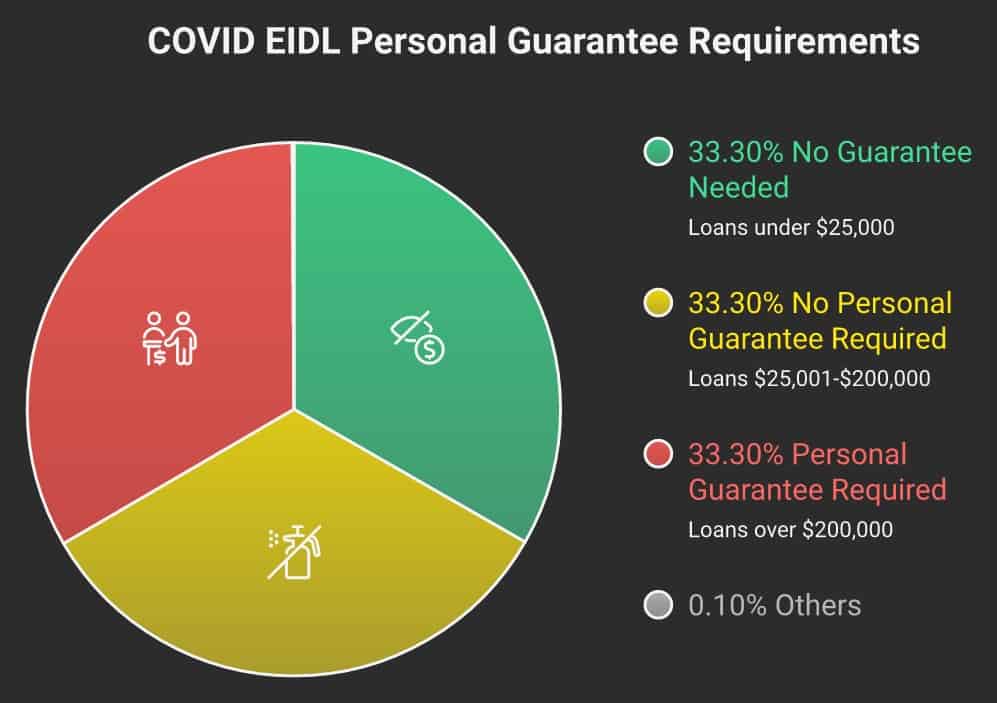
The SBA set up clear tiers for COVID EIDL loans. These weren’t suggestions — they were the program’s published requirements:
- Loans up to $25,000: No collateral, no personal guarantee
- Loans $25,001 to $200,000: Collateral required (UCC lien on business assets), but no personal guarantee
- Loans over $200,000: Collateral required AND personal guarantee required (for owners with 20%+ stake)
On top of that, the CARES Act specifically authorized the SBA Administrator to waive rules related to personal guarantees on loans and advances of $200,000 or less.
Put plainly: if your EIDL was under $200,000, the SBA’s own policy said you should not have been required to sign a personal guarantee.
So Why Did Some Borrowers Sign One?
This is the question I keep hearing. And the honest answer is: the SBA’s rollout of 3.9 million EIDL loans was fast, chaotic, and inconsistent.
Some loan officers presented personal guarantee documents as standard procedure. Some borrowers signed everything placed in front of them without understanding what each document meant — which is understandable when you’re trying to keep a business alive during a pandemic. Some guarantee language was embedded in the loan note itself rather than presented as a separate document.
The result is a large number of borrowers who signed personal guarantees on loans that, according to the SBA’s own published rules, should never have required one.
The Claim: “I signed it, so I’m stuck with it. A contract is a contract.”
The Reality: Whether a signed personal guarantee is enforceable depends on multiple factors — including whether the guarantee was required under the program rules, whether it was properly executed under your state’s law, and whether the SBA can even produce the signed document. The American Bankruptcy Institute has documented cases where the SBA cannot locate signed guarantees — and without a signed document, there’s no enforceable guarantee.
What Happens When the Business Is Closed
If your business entity (LLC, corporation, or partnership) has closed, the business itself can’t pay. That makes the personal guarantee question the entire ballgame.
Without a Valid Personal Guarantee
- Debt belongs to the business entity, not you
- Treasury cannot garnish your personal wages
- Treasury cannot intercept your personal tax refund
- Treasury cannot offset your Social Security
- Your personal assets are generally protected
With an Enforceable Personal Guarantee
- You are personally liable for the full balance
- Treasury can garnish 15% of disposable wages
- Treasury can intercept your tax refunds
- Treasury can offset Social Security payments
- The 28-30% admin fee applies to your personal liability
Sole proprietors: If you operated as a sole proprietorship (no LLC, no corporation), the business IS you legally. There’s no entity separation. You are personally liable for the EIDL regardless of whether a personal guarantee exists — because you borrowed the money as an individual. The personal guarantee question primarily matters for borrowers whose businesses were structured as LLCs, corporations, or partnerships.
The Treasury Administration Fee: What the $41,000 Surprise Actually Is
When the SBA refers your defaulted loan to Treasury, something happens that shocks most borrowers: your balance jumps by 28-30%.
This is the “cross-servicing collection cost” — authorized under the Debt Collection Improvement Act. It’s not a penalty in the traditional sense. It’s a fee Treasury charges to cover the administrative cost of collecting the debt.
On a $133,000 EIDL, that’s roughly $37,000 to $40,000 added to your balance — before any additional interest accrual. That’s how a $133,000 loan becomes a $174,000 demand.
For a crisis-focused walkthrough of what happens step by step when you default — including the Treasury referral timeline, the 30% penalty, and your full range of options — see: I Can’t Repay My SBA EIDL Loan. What Happens to Me?
Can you challenge the administration fee? Disputing the fee itself is rarely successful — it’s authorized by federal statute. But an attorney can evaluate whether the underlying debt is actually yours to pay. If the personal guarantee isn’t enforceable, the fee built on top of it isn’t enforceable either.
Treasury’s Collection Tools — No Court Order Needed
Unlike private debt collectors, Treasury doesn’t need to sue you to collect. Their tools are administrative, not judicial:
- Administrative Wage Garnishment: Up to 15% of your disposable income, without a court order
- Tax Refund Offset: Your federal and state tax refunds intercepted automatically
- Social Security Offset: A portion of your Social Security benefits seized
- Federal Payment Seizure: Any federal salary, contractor payment, or benefit offset
- Credit Bureau Reporting: The default appears on your credit report
This is why the personal guarantee question matters so much. If you’re not personally liable, none of these tools can be used against you as an individual. If you are, all of them can — and they don’t need a judge’s permission.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What You Should Do Right Now
If you’re in this situation — sub-$200K EIDL, personal guarantee signed, business closed, Treasury collecting — here are the steps that actually matter:
- Do not agree to any payment plan with Treasury before talking to an attorney. Entering a payment plan can waive defenses you currently have. This is not a “wait and see” situation.
- Find an SBA loan attorney or consumer attorney in your state. Not a general business lawyer — someone who specifically handles SBA loan defaults and Treasury referrals. Search for “SBA loan attorney [your state]” or “EIDL default attorney [your state].” Many offer free initial consultations.
- Gather your documents. The original EIDL loan note, anything labeled “personal guarantee,” all correspondence from the SBA and Treasury, and the demand letter showing the administration fee. These documents are the foundation of everything.
- Ask the attorney one specific question: “Was a personal guarantee on a sub-$200K COVID EIDL legally required, and is mine enforceable?” That single question is worth more than any amount of Googling.
- If Treasury contacts you before you have an attorney, tell them you’re seeking legal counsel and are not prepared to discuss terms at this time. You have that right.
Need help thinking through this? Do me a favor — reach out to Damon Day. I’ve mentored him for more than 20 years and he’s the best independent debt consultant I know. He can help you figure out what kind of attorney you need and what questions to ask. No products, no agenda. First conversation is free.
Bankruptcy Is Still on the Table
If the personal guarantee is enforceable — or if you were a sole proprietor and personal liability isn’t in question — bankruptcy may be the cleanest path through this.
I know that word scares people. It scared me too, in 1990, when my real estate business collapsed and I had to file. But here’s what I learned from living it: Federal Reserve research shows bankruptcy filers recover faster than people who spend years grinding through repayment plans. SBA debt — including EIDL loans — can be discharged in both Chapter 7 and Chapter 13.
“Owners of small businesses are personally liable for their business debts (this is often the case even if the businesses are incorporated), so that they end up with high debts if their businesses fail. A pro-debtor bankruptcy law encourages self-employment by discharging both business and personal debts in bankruptcy.”
— Michelle J. White, Bankruptcy Reform and Credit Cards (2007)
A bankruptcy attorney consultation is free. It costs you nothing to sit down and hear exactly what would happen in your specific situation. Many attorneys offer payment plans starting around $200-300 down. You can’t afford NOT to make that one free phone call.
For a deeper look at your options if your EIDL is already in default, read my full guide: SBA COVID EIDL in Default: Your Options Before Panic Sets In.
Key Takeaways
- SBA rules did not require personal guarantees on COVID EIDL loans under $200,000 — the CARES Act authorized waiving them
- If you signed one anyway, whether it’s enforceable depends on your state’s law, the specific language of what you signed, and whether the SBA can produce the document
- If your business is closed and there’s no valid personal guarantee, Treasury generally cannot pursue your personal assets, wages, or tax refunds
- Treasury adds a 28-30% administration fee when it takes over collection — but if the underlying personal liability isn’t valid, the fee isn’t either
- Do not enter a payment plan with Treasury before an SBA attorney reviews your documents — paying can waive defenses you currently have
- Bankruptcy can discharge EIDL debt if personal liability exists — and the consultation is free
The Bottom Line
If you’re staring at a Treasury demand letter right now, feeling like you have no options — I need you to hear this: the fact that you signed something doesn’t automatically mean you owe it. Federal policy said your loan shouldn’t have required a personal guarantee. That matters. The single most important thing you can do this week is get the documents you signed in front of an SBA attorney and ask one question: “Is this enforceable?” That 30-minute conversation could be the difference between owing $174,000 and owing nothing. I rebuilt my entire life after bankruptcy in 1990. Whatever the answer turns out to be, there is a path through this — and you deserve to know what it is before you write a check.
Frequently Asked Questions
Was a personal guarantee required on COVID EIDL loans under $200,000?
No. The SBA’s published program requirements only required personal guarantees on EIDL loans exceeding $200,000 for owners with 20% or more stake in the business. The CARES Act further authorized the SBA to waive personal guarantee requirements on loans and advances of $200,000 or less. However, some borrowers were asked to sign personal guarantees despite this policy.
If I signed a personal guarantee on a sub-$200K EIDL, is it automatically enforceable?
Not necessarily. Enforceability depends on several factors including your state’s laws governing guarantees, the specific language and execution of the document, and whether the SBA can produce a properly signed copy. An SBA loan attorney can evaluate your specific situation — many offer free initial consultations.
My business is closed. Can Treasury still come after me personally?
It depends entirely on whether you have an enforceable personal guarantee — or whether you operated as a sole proprietorship (where you and the business are legally the same). If you had an LLC or corporation and there’s no valid personal guarantee, Treasury’s options against you personally are limited. If the guarantee is valid, Treasury can garnish wages, intercept tax refunds, and offset Social Security without a court order.
What is the 28-30% Treasury administration fee?
When the SBA refers a defaulted loan to Treasury for collection, a “cross-servicing collection cost” of approximately 28-30% is added to your outstanding balance under the Debt Collection Improvement Act. On a $133,000 loan, that’s roughly $37,000-$40,000 added before any additional interest. This fee is authorized by federal statute and is difficult to challenge directly — but if the underlying personal liability isn’t valid, the fee built on top of it isn’t either.
Should I enter a payment plan with Treasury while I figure this out?
Talk to an attorney first. Entering a payment plan or making payments can potentially waive legal defenses you currently have. If Treasury contacts you, you have the right to tell them you’re seeking legal counsel and aren’t prepared to discuss terms. Use that time to get an attorney review of your documents.
For a crisis-focused walkthrough of what happens step by step when you default — including the Treasury referral timeline, the 30% penalty, and your full range of options — see: I Can’t Repay My SBA EIDL Loan. What Happens to Me?
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



SBA contact me to offer help and they said I do not have to pay back the money and everything done online and the money $12000to pay my apartment rent and I am not working because of health issues, only $830 from SSA