

Quick Answer: A New Jersey mother’s class-action lawsuit against a medical debt collector exposes a pattern of illegal tactics that millions of Americans face silently — and each violation can cost the collector up to $1,000 in statutory damages, plus attorney’s fees paid to you. If a medical debt collector has threatened you, misrepresented themselves, or ignored your written requests, the law may have just handed you leverage to eliminate the debt entirely. (See also: 52% of Americans falling behind in the E-shaped economy.)
Expert Context: I’ve studied debt collector tactics since the 1990s — including as someone who was on the receiving end after my own bankruptcy in 1990. I’ve reviewed thousands of collection call complaints and seen every intimidation playbook. What happened to this New Jersey mom isn’t a one-off. It’s standard operating procedure at bottom-tier collection agencies, and most consumers never learn that the law protects them. Older adults are especially vulnerable — if you’re dealing with an elderly parent who was charged for something over the phone, that’s a separate playbook.
Part of the FDCPA Rights Hub: This post is one piece of my complete Debt Collectors and Your FDCPA Rights: The Complete Guide — what collectors can and cannot do, how to stop calls, demand validation, fight back in court, and sue collectors who cross the line.
Gabby Lomas of Magnolia, New Jersey, owed $3,300 in medical bills from her daughter’s birth. Months later, a Pennsylvania-based debt collector named Apex Asset Management started calling. When she asked them to stop — in writing — they didn’t. They called her husband instead. They sent letters signed by a “Legal Collection Coordinator” to make it look like an attorney was involved. They threatened to report the debt to credit bureaus. Every one of those actions may have been illegal — and right now, she’s suing them in a proposed class-action.
Here’s what matters for you: if a medical debt collector has done any of these things to you, they may have broken federal law. And every violation can shift the balance of power from them to you.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
What This Collector Actually Did — and Why It’s Illegal
According to CBS News Philadelphia, Gabby Lomas’s lawsuit against Apex Asset Management alleges five specific violations of the Fair Debt Collection Practices Act and New Jersey consumer protection laws:
- Continued calling after a written cease-and-desist. Once you send a written request to stop contact, the collector must comply. Period. Continuing to call is a federal violation.
- Contacted her husband after the cease-and-desist. Contacting third parties — including family members — to collect a debt after being told to stop is prohibited under the FDCPA.
- Letters signed by a “Legal Collection Coordinator.” Implying attorney involvement when none exists is a deceptive practice. If no attorney reviewed your file, that title on a letter is designed to scare you.
- Threatened to report medical debt to credit bureaus. Under New Jersey’s Louisa Carman Medical Debt Relief Act, medical debt from services after July 22, 2024, cannot be reported to credit agencies. Threatening to do so is a violation of state law.
- Ignored requests for debt validation. Under the FDCPA, a collector must provide written verification of the debt within 30 days of your request. Ignoring that request and continuing collection activity is illegal.
As Lomas told CBS: “I’m more than willing to pay my debt back. I just want to hold them accountable.”
That quote tells you everything about why these laws exist. The issue isn’t whether a debt is owed. It’s whether a collector followed the rules while collecting it.
Your FDCPA Rights: What Most People Don’t Know
The Fair Debt Collection Practices Act gives you specific, enforceable rights against third-party debt collectors. Here’s what matters most when you’re dealing with a medical debt collector:
Key Terms Defined
FDCPA (Fair Debt Collection Practices Act): Federal law (15 U.S.C. § 1692) that prohibits abusive, deceptive, and unfair debt collection practices by third-party collectors. Does not apply to the original creditor (your hospital).
Cease-and-desist letter: A written request telling a collector to stop contacting you. Once received, the collector can only contact you to confirm they’re stopping or to notify you of a specific legal action.
Debt validation: Your right under the FDCPA to demand written proof that the debt is yours, the amount is correct, and the collector has legal authority to collect it. The collector must stop all collection activity until they provide it.
Statutory damages: A court-ordered payment to you for the violation itself — you don’t have to prove you lost money. Up to $1,000 per lawsuit under the FDCPA.
- You can demand validation. Within 30 days of first contact, send a written request for proof of the debt. The collector must stop until they provide it. Use my free Debt Validation Letter Generator to create the letter.
- You can stop the calls. A written cease-and-desist legally requires the collector to stop contacting you. This doesn’t erase the debt, but it stops the harassment.
- You can sue for violations. Each FDCPA violation can result in up to $1,000 in statutory damages per lawsuit, plus actual damages (financial losses and emotional distress), plus attorney’s fees. Many FDCPA attorneys work on contingency — free to you.
- You can file complaints. Report violations to the CFPB, your state attorney general, and the FTC. These complaints create the enforcement record that gets bad collectors shut down.
The Claim: “A debt collector can report your medical debt to the credit bureaus and ruin your credit score.”
The Reality: It depends on where you live and when the services were provided. In New Jersey, the Louisa Carman Medical Debt Relief Act prohibits reporting medical debt from services after July 22, 2024 — and if a collector reports it anyway, the debt is automatically voided. No other state has a provision that cancels the debt for violating the reporting ban. Even outside New Jersey, the three major credit bureaus voluntarily stopped reporting medical debt under $500 in 2023.
Free Tool — Debt Validation Letter Generator: Being contacted by a debt collector? The free Debt Validation Letter Generator creates a personalized FDCPA validation letter in seconds — forcing the collector to prove the debt is real before they can continue. Generate My Letter →
The Charity Care Crisis Makes This Worse
Here’s the part that isn’t getting enough attention. On the same day the Lomas lawsuit hit the news, NPR published an investigation showing that charity care — the financial assistance hospitals are supposed to provide to patients who can’t pay — is becoming harder to access at the exact moment more Americans are losing health coverage.
The numbers are staggering:
- 100 million Americans are currently burdened by healthcare debt, according to the CFPB
- Uninsured rates are expected to climb further as Medicaid cuts force states to pare back coverage
- Many hospitals require applicants to submit bank statements, retirement accounts, and mortgage documents just to apply for charity care
- Some states’ hospitals provide a third of the national average in charity care as a percentage of operating budgets
What this means in practice: more people are getting medical bills they can’t pay, fewer are qualifying for financial help from the hospitals that billed them, and the bills are ending up with third-party collectors who may not follow the rules.
Don’t wait for collectors to find you. If you have an outstanding medical bill, call the hospital’s billing department now and ask specifically about their financial assistance policy (also called “charity care”). Ask for the written policy. Hospitals that receive federal funding are required to have one. Apply before the bill goes to collections — once a third-party collector has it, the hospital’s financial assistance program may no longer apply.
What This Means for You Right Now
I’ve been helping people with debt since 1994. The pattern I see over and over is this: a medical bill arrives, the person is overwhelmed, they don’t respond, and by the time a collector is calling at dinner, they feel like they’ve already lost.
They haven’t. The law is specifically designed to give you power in this situation — but only if you use it.
“Debtor and creditor confront each other like a peasant before a feudal lord. The law of precedent takes hold.”
— David Graeber, Debt: The First 5,000 Years (2011)
That’s exactly the dynamic these collectors are counting on. They want you to feel like a peasant. The FDCPA exists to make sure you don’t have to be one.
Your Step-by-Step Action Plan
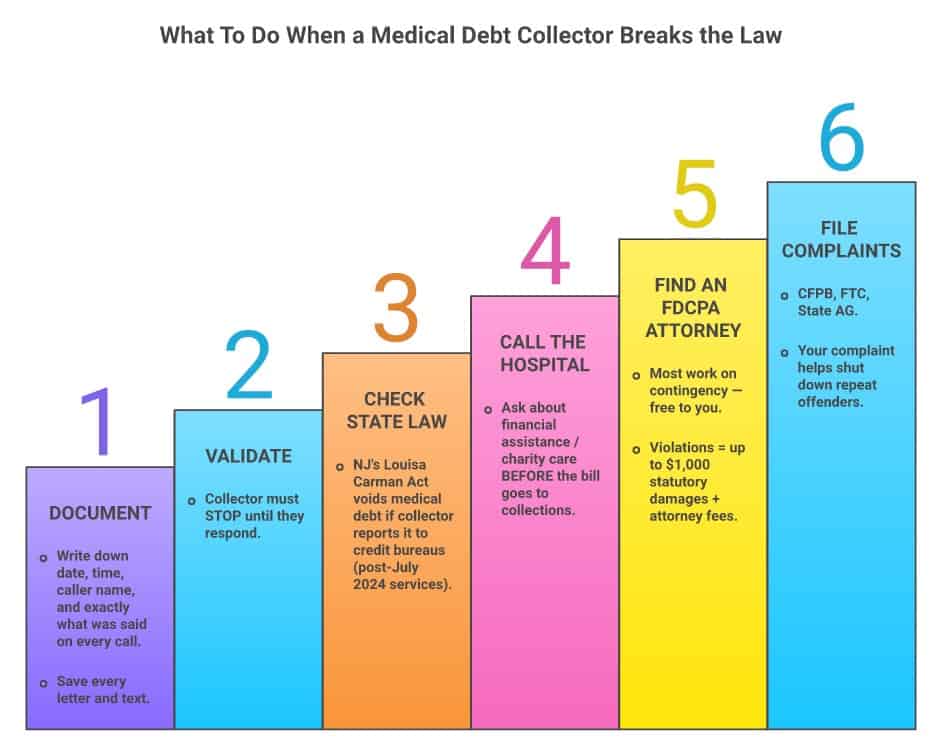
If a medical debt collector has contacted you — or if you have a medical bill heading toward collections — here’s exactly what to do:
- Document everything. Write down the date, time, caller’s name, and exactly what was said on every call. Save every letter and text message. This documentation becomes your evidence if they’ve violated the law.
- Send a debt validation letter. Use my free Debt Validation Letter Generator to demand proof of the debt. Send it certified mail, return receipt requested. The collector must stop all collection activity until they respond.
- Check your state’s medical debt laws. New Jersey’s Louisa Carman Act is the strongest in the country, but other states have protections too. If you’re in NJ and the services were after July 22, 2024, a collector who reports the debt to credit bureaus automatically voids it.
- Call the hospital first. Before dealing with the collector at all, call the original hospital billing department and ask about their financial assistance policy. You may qualify for a partial or full write-off. In New Jersey, 1.5 million residents have benefited from over $1.1 billion in medical debt relief.
- Find an FDCPA attorney. If the collector violated any of the rules above — continued calling after a cease-and-desist, threatened credit reporting in a state that bans it, used fake attorney titles — contact a consumer rights advocate or search the National Association of Consumer Advocates for an FDCPA attorney. Most work on contingency, meaning you pay nothing unless you win.
- File complaints. Report violations to the CFPB, the FTC, and your state attorney general. Even if you don’t sue, your complaint joins the record that regulators use to shut down repeat offenders.
Not sure where you stand? Run the collector’s name through the Scam-O-Meter to check their complaint history, or take the Find Your Path quiz if the medical debt is part of a larger problem. If you received a contract from a debt relief company, use the free Contract Decoder to spot hidden fees before you sign.
Key Takeaways
- Every illegal debt collection tactic — fake attorney titles, ignored cease-and-desist letters, threats to report protected medical debt — can cost the collector up to $1,000 in statutory damages plus your attorney’s fees
- New Jersey’s Louisa Carman Act is the strongest medical debt law in the country: if a collector reports medical debt from post-July 2024 services, the debt is automatically voided
- Charity care is getting harder to access just as more Americans are losing health coverage — apply for hospital financial assistance before your bill goes to collections
- Document every call, send a debt validation letter, and file complaints even if you don’t sue — these complaints are how bad collectors get shut down
- FDCPA attorneys typically work on contingency — the collector pays your legal fees if you win, not you
The Bottom Line
If you’re staring at a medical bill you can’t pay while a collector calls you at dinner, I need you to hear this: you have more power in this situation than they want you to believe. The law exists specifically to stop the intimidation, the fake attorney letters, and the threats. Every violation they commit is leverage you can use. I filed bankruptcy in 1990 after my own financial collapse, and I rebuilt everything — not because I was special, but because I stopped feeling powerless and started using the tools the law gave me. Those same tools are available to you right now. The medical bill is a math problem. The collector’s behavior is a legal problem. And legal problems have solutions.
This is what I’m seeing after 30 years of watching debt collectors cross the line. Take it as one informed perspective — but only you know your full situation. My advice is input for your decision, not a directive. Nobody — not a collector, not a financial guru, and not me — gets to tell you what to do with your money. But please, do something. Don’t let the fear win.
If you are reading this because a medical collector just called you for the first time, I have a separate emergency guide that walks through the first 48 hours, the deadlines, and the nonprofit-hospital rules most collectors never mention: A Medical Bill Went to Collections and Nobody Warned Me.
Frequently Asked Questions
Can a medical debt collector threaten to report the debt to credit bureaus?
It depends on your state and when the services were provided. In New Jersey, the Louisa Carman Medical Debt Relief Act prohibits reporting medical debt from services after July 22, 2024, and violations automatically void the debt. Even outside New Jersey, the three major credit bureaus stopped reporting medical debt under $500 in 2023. If a collector threatens to report when they legally can’t, that’s an FDCPA violation worth up to $1,000 in statutory damages.
How much can I sue a debt collector for if they break the law?
Under the FDCPA, you can recover up to $1,000 in statutory damages per lawsuit (not per violation), plus actual damages for financial losses and emotional distress, plus reasonable attorney’s fees and court costs. In class-action cases, statutory damages can reach up to $500,000 or 1% of the collector’s net worth, whichever is less.
What should I do if a debt collector calls after I sent a cease-and-desist letter?
Document the date, time, and what was said on every subsequent call. Each contact after a valid written cease-and-desist is an FDCPA violation. Save your certified mail receipt proving they received your letter. Then contact an FDCPA attorney — most work on contingency, so you pay nothing upfront. The continued calls are evidence that strengthens your case.
Does sending a cease-and-desist letter make my debt go away?
No. A cease-and-desist letter stops the collector from contacting you, but the debt still exists. The collector can still sue you for the debt — they just can’t call, write, or text you (except to notify you of a lawsuit). If you owe the debt, you’ll still need to address it through payment, negotiation, financial assistance, or potentially bankruptcy.
How do I apply for hospital charity care or financial assistance?
Call the hospital billing department directly and ask for their financial assistance application. Hospitals that receive federal funding are required to have a financial assistance policy. You’ll typically need income documentation (pay stubs or tax returns). Apply before the bill goes to a third-party collector — once it’s been sold to a collection agency, the hospital’s program may no longer cover it. In New Jersey, providers must wait 120 days after the first bill before engaging collectors, giving you time to apply.
Know Your Rights: If a debt collector is contacting you, you have legal protections. See the complete list of FDCPA violations collectors commit most often. Use the free Debt Validation Letter Generator to demand proof of the debt, or check this collector’s complaint history with the Scam-O-Meter.
Update: The federal medical debt protections you may have been counting on are now dead — read the full breakdown.
Related: If you live in Virginia, the Virginia’s new Medical Debt Protection Act adds new protections starting July 2026 — including a 3% interest cap and a ban on arrest over hospital debt.
Dealing With Debt? Before you pay a collector, understand all your debt relief options — including ones the collector won’t tell you about. If the debt feels unmanageable, take the 2-minute bankruptcy quiz to see if the math favors a fresh start. Federal Reserve research shows filers recover faster than those who don’t file.



